- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
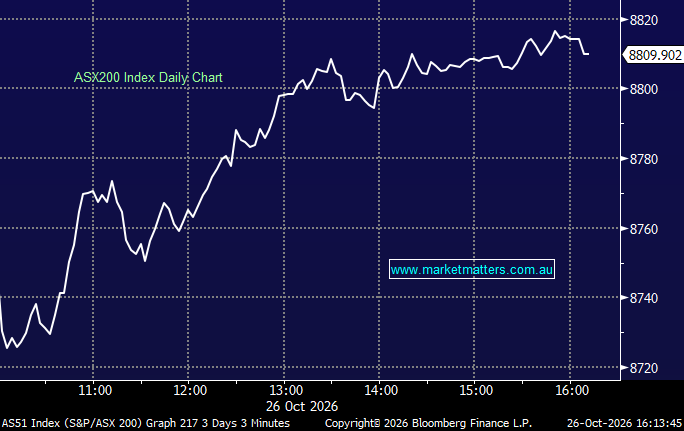
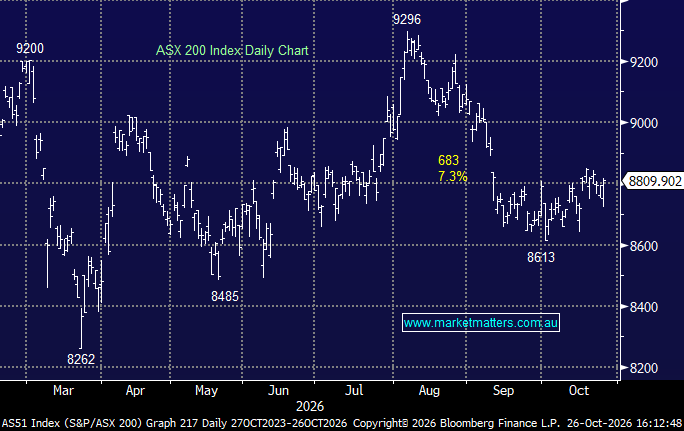
The ASX staged a sharp intraday recovery, rallying ~85 points from its morning low to finish higher as technology, resources and property shares turned higher. The rebound followed early weakness as the market weighed the risk of higher interest rates against a busy week of Australian inflation data, US earnings and central bank decisions. Materials recovered some ground after last week’s selloff, while the major banks pared their early losses.
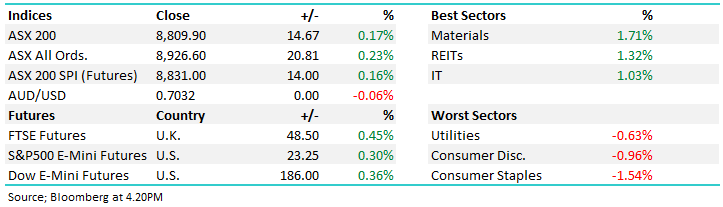
- ASX 200: 8,809.90, +14.67 points, +0.17%.
- AUD/USD: 0.7032, -0.06%.
- Best Sectors: Materials +1.71%, REITs +1.32%, Information Technology +1.03%.
- Worst Sectors: Consumer Staples -1.54%, Consumer Discretionary -0.96%, Utilities -0.63%.
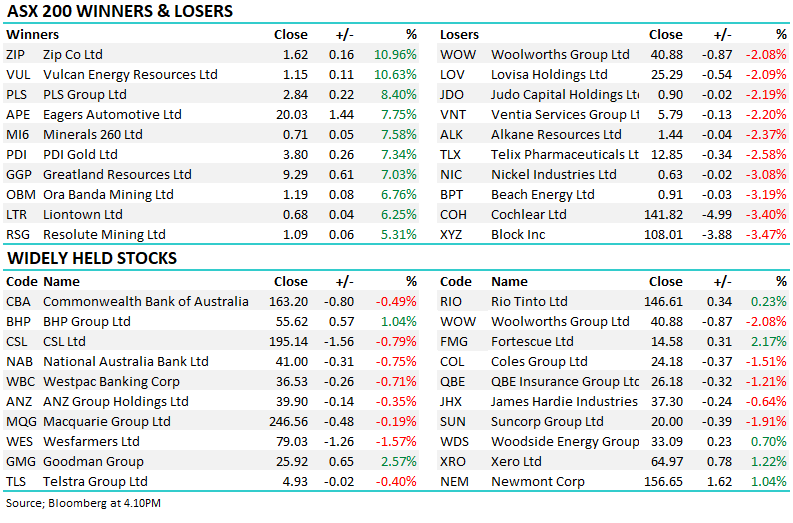
- Banks and rates: The major banks pared early losses but all closed lower. The outlooks for next week’s RBA decision remain split: NAB and CBA expect the cash rate to stay at 4.6%, while Westpac and ANZ forecast a fifth increase on 3 November – Wednesday’s inflation report is a key input. National Australia Bank (ASX: NAB) -0.75% to $41.00, Commonwealth Bank of Australia (ASX: CBA) -0.49% to $163.20, Westpac Banking Corporation (ASX: WBC) -0.71% to $36.53 and ANZ Group Holdings (ASX: ANZ) -0.35% to $39.90 all fell. ANZ & WBC held in the Active Growth & Income Portfolios.
- Tech recovered though concerns about AI infrastructure funding remained after SpaceX’s reported US$40 billion debt deal to finance chip purchases – Xero (ASX: XRO) +1.22% to $64.97, Wisetech Global (ASX: WTC) +1.45% to $40.70 and Megaport (ASX: MP1) +1.2% to $16.04.
- NEXTDC (ASX: NXT) -1.25% to $5.54 announced a board reset following last week’s Melbourne power delay and guidance downgrade: its chair will retire once a successor is appointed, two independent directors are expected in early 2027, proposed director fee increases were withdrawn, and CEO Craig Scroggie will forgo FY27 incentives.
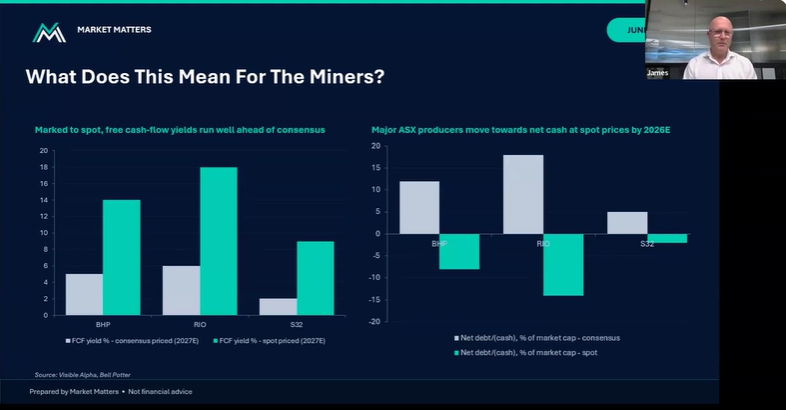
- Miners rebounded after a four-day slide, with iron ore, lithium, rare earths and uranium stocks among those recovering – BHP Group (ASX: BHP) +1.04% to $55.62, Rio Tinto (ASX: RIO) +0.23% to $146.61 and Fortescue (ASX: FMG) +2.17% to $14.58 finished higher. BHP held in Active Growth & Income Portfolio. RIO held in the Active Growth Portfolio. FMG held in the Active Income Portfolio.
- PLS Group (ASX: PLS) +8.40% to $2.84 and Liontown Resources (ASX: LTR) +6.25% to $0.68 led a lithium-sector rebound.
- BlueScope Steel (ASX: BSL) +2.94% to $33.31 lifted first-half FY27 underlying EBIT guidance to nearly $1.1 billion, about 15% above analyst estimates, citing stronger US steel spreads and resilient Australian demand.
- Company news: Challenger (ASX: CGF) -0.59% to $11.85 rejected TAL Dai-ichi Life’s proposal, saying it was not at a level the board could recommend to shareholders.
- Zip Co (ASX: ZIP) +10.96% to $1.62 rebounded after Friday’s sharp selloff; UBS and Macquarie viewed the US fraud impact as temporary and pointed to faster US transaction-volume growth in September. Held in the Emerging Companies Portfolio.
- Gold: Traded near US$4,010/oz / +0.4%.
- Iron Ore: US$90.30/mt / -0.2%
- Brent crude: US$114.50/mt / -1.8%
- Futures: S&P 500 E-mini futures +23.25pts / +0.30% | Dow Jones E-mini futures +186.00pts / +0.36% | FTSE futures +48.50pts / +0.45%.