- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify
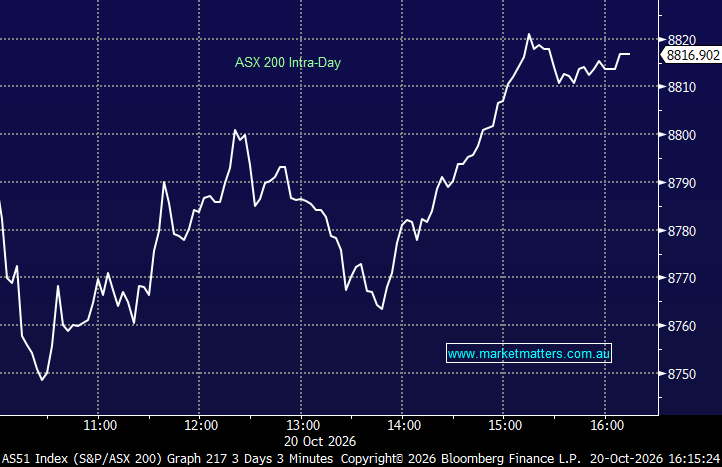
The ASX 200 finished mildly lower, recovering from a much weaker start that saw the main board off ~80pts at the lows. The market was again split beneath the surface: consumer-facing and healthcare names found support, while miners, energy stocks and the banks weighed on the index.
Resources were the main drag after BHP’s quarterly update showed a 19% fall in copper production, while elevated global bond yields continued to pressure sentiment. The US 10-year was back around 5.14% after rising overnight, while Brent crude remained close to US$110/bbl as geopolitical risk lingered. Encouragingly, there was still healthy stock-specific buying underneath the index, particularly in selected growth, property and consumer names.
- ASX 200: -28.83pts / -0.33% to 8,816.90
- AUD/USD: 0.6982 / +0.03%
- Best sectors: Consumer Staples +1.14%, Healthcare +0.87%, Consumer Discretionary +0.76%
- Worst sectors: Energy -1.31%, Materials -1.16%, Financials -0.48%
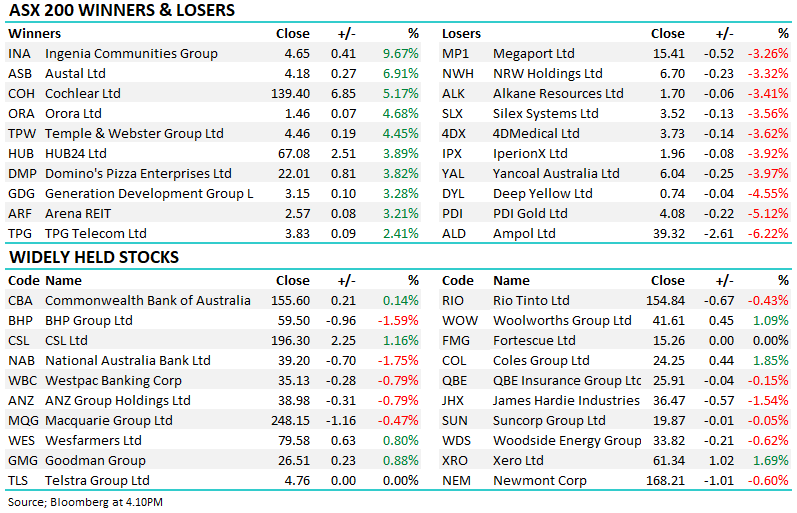
- Ingenia Communities (INA) +9.67% to $4.65 topped the ASX 200 after Warburg Pincus and Ingenia extended negotiations around the $5.25-a-share takeover proposal, with Warburg given additional time to complete due diligence.
- Austal (ASB) +6.91% to $4.18 was another standout, while Cochlear (COH) +5.17% to $139.40 helped healthcare outperform.
- Ora Banda Mining (OBM) +4.68% to $1.46, Temple & Webster (TPW) +4.45% to $4.46, Domino’s Pizza (DMP) +3.82% to $22.01 and Generation Development Group (GDG) +3.28% to $3.15 were among the stronger movers.
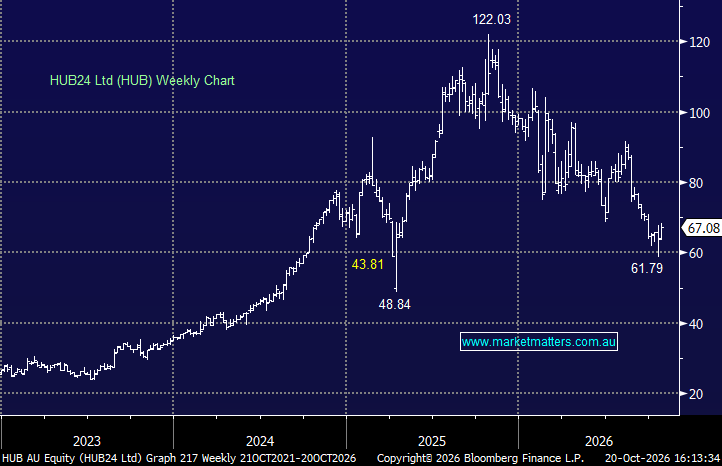
- HUB24 (HUB) +3.89% to $67.08 rallied after delivering $3.98bn of platform net inflows for the September quarter, ahead of expectations. Total FUA rose 15% YoY to $168.6bn and platform FUA increased 18% to $143.7bn, providing some reassurance after recent concerns about slowing industry flows. HUB held in Growth Portfolio
- Technology was mixed but generally firmer beneath the surface, with Xero (XRO) +1.69% to $61.34, while WiseTech Global (WTC) +1.36% and Life360 (360) +1.77% also gained. XRO & WTC held in Growth Portfolio, 360 held in Emerging Companies Portfolio.
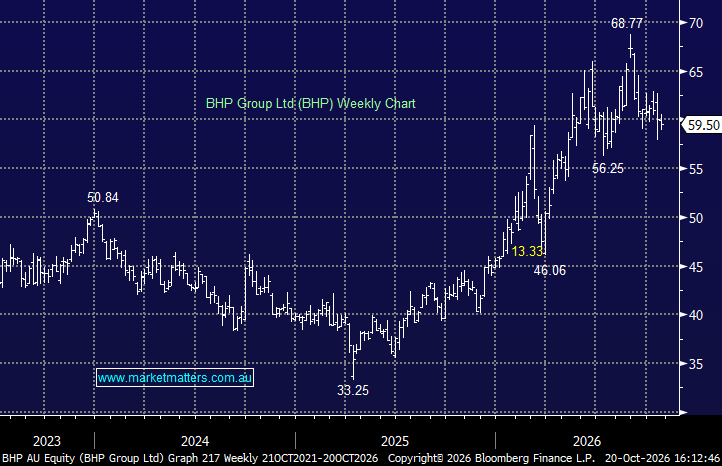
- BHP (BHP) -1.59% to $59.50 fell after reporting a 19% decline in quarterly copper production, although FY27 guidance was maintained. Rio Tinto (RIO) -0.43% to $154.84 also eased, while Fortescue (FMG) finished flat at $15.26. BHP held in Growth & Income Portfolios, FMG held in Income Portfolio.
- The banks were a drag, with NAB (NAB) -1.75% to $39.20, ANZ (ANZ) -0.79% to $38.98, Westpac (WBC) -0.79% to $35.13 and Macquarie Group (MQG) -0.47% to $248.15. Commonwealth Bank (CBA) +0.14% to $155.60 bucked the trend. ANZ & WBC held in Growth & Income Portfolios
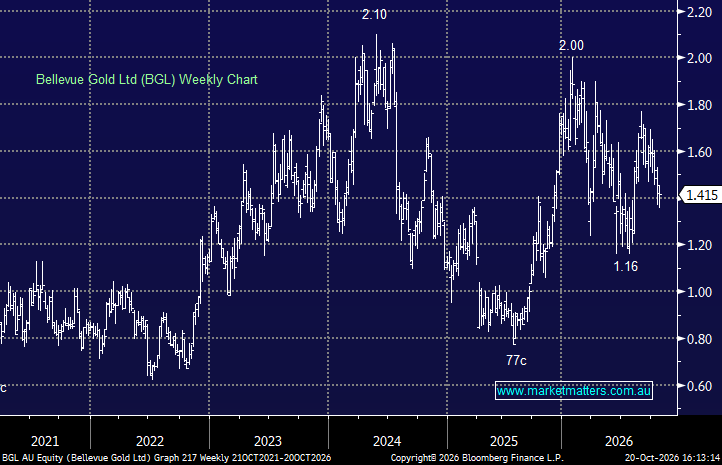
- Gold stocks were broadly weaker, with Bellevue Gold (BGL) -1.05% to around $1.42, Genesis Minerals (GMD) -1.39%, Northern Star (NST) -1.68%, Regis Resources (RRL) -1.86% and West African Resources (WAF) -1.96% lower. BGL held in Emerging Companies Portfolio
- Megaport (MP1) -3.26% to $15.41, NRW Holdings (NWH) -3.32% to $6.70, Alkane Resources (ALK) -3.41% to $1.70, Silex Systems (SLX) -3.56% to $3.52 and 4DMedical (4DX) -3.62% to $3.73 were among the larger losers. Silex held in Emerging Companies Portfolio
- Uranium remained under pressure, with Deep Yellow (DYL) -4.55% to $0.74 the weakest link there.
- Ampol (ALD) -6.22% to $39.32 was the weakest ASX 200 stock on the day.
- Brent crude remained close to US$109/bbl, with markets balancing recovering Persian Gulf export flows against ongoing risks around the Strait of Hormuz.
- FTSE futures: -54.5pts / -0.50%
- S&P 500 E-mini futures: +3pts / +0.04%
- Dow E-mini futures: +99pts / +0.19%