- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
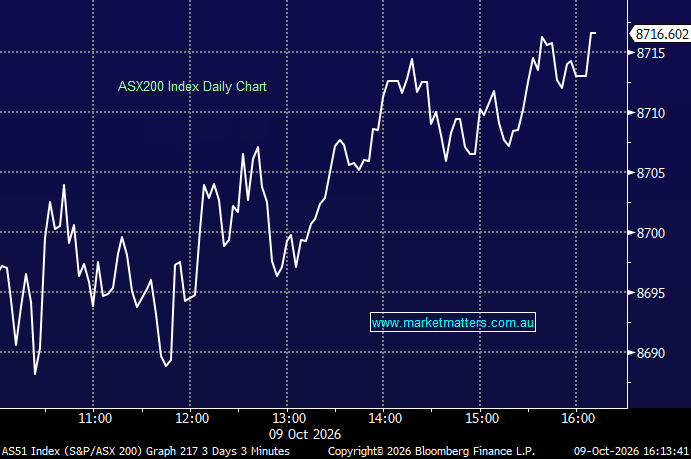
The ASX finished the week on a firmer note, extending its recovery after a volatile few sessions. Market breadth improved, with 9 of 11 sectors higher and ~70% of ASX200 stocks finishing in the green. Elevated bond yields and the fallout from the cancelled Firmus IPO remained in focus, though strong sessions from Technology, Consumer Discretionary and Real Estate more than offset weakness in Materials and Communication Services.
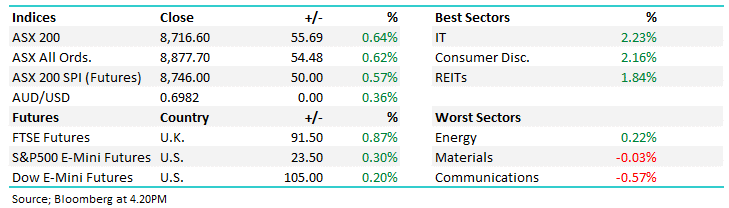
- ASX 200: +55.69pts / +0.64% to 8,716.60
- AUD/USD: 0.6982 / +0.36%
- Best Sectors: IT +2.23%, Consumer Disc. +2.16%, REITs +1.84%
- Worst Sectors: Energy +0.22%, Materials -0.03%, Communications -0.57%
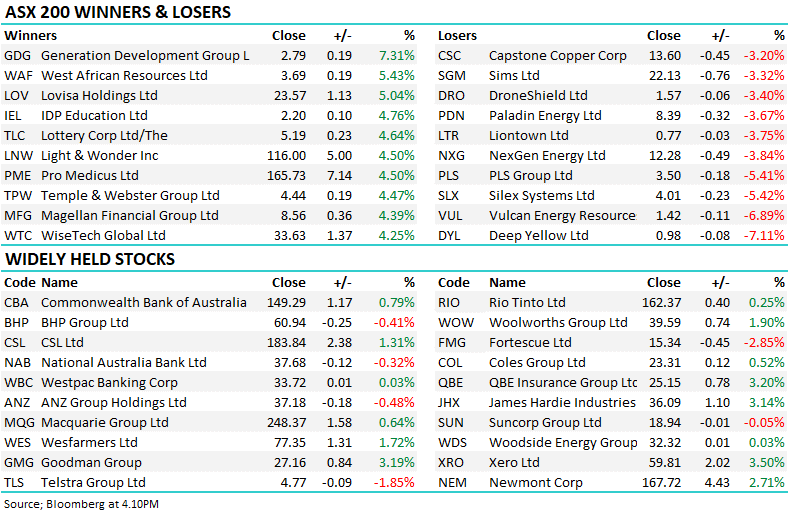
- Technology rebounded with Xero (ASX: XRO) +3.50% to $59.81 and WiseTech (ASX: WTC) +4.25% to $33.63 leading a recovery in beaten-down software names, despite overnight weakness in US tech stocks and renewed questions over whether AI revenues will justify infrastructure spending.
- Consumer Discretionary found support again, as the sector extended their recent bounce – Lovisa (ASX: LOV) +5.04% to $23.57, ARB Corp (ASX: ARB) +3.83% to $17.62 and Flight Centre (ASX: FLT) +0.98% to $10.26 gained despite consumer sentiment sitting at historically depressed levels.
- Materials edged higher, with BHP (ASX: BHP) -0.41% to $60.94 and Rio Tinto (ASX: RIO) +0.25% to $162.37 holding up better than smaller miners. Lithium, uranium and copper names remained under pressure, with Chinese lithium carbonate prices down around 44% from their May peak.
- Electro Optic Systems (ASX: EOS) -4.25% to $10.13 Won a record £370m (around A$700m) counter-drone contract for a Gulf state. More than 80% of revenue is expected within 12–24 months of the deal becoming unconditional, subject to approvals and guarantees.
- Maas Group (ASX: MGH) -6.65% to $4.63 Resumed trading after confirming it expects to complete its Firmus work orders by end-2027. Maas holds 3.2% of Firmus and has around $1.1bn in work orders, with $373m already paid. Firmus has shelved its proposed IPO and will pursue private funding.
- Telix Pharmaceuticals (ASX: TLX) closed flat at $15.85 UBS maintained Buy and raised its valuation to $26/share, citing the potential of its FDA fast-tracked prostate cancer imaging program.
- Boss Energy (ASX: BOE) -9.93% to $1.36 Fell after Goldman Sachs downgraded the stock to Sell with a $1.35 target, adding to volatility across uranium names. Paladin (ASX: PDN) -3.67% to $8.39 and Deep Yellow (ASX: DYL) -7.5% to 98c were also hit.
- Mastermyne Group (ASX: MYE) +6.21% to 77c Secured a Tahmoor mine services contract worth around $80m over two years, potentially rising to $240m if both extensions are exercised.
- Lifestyle Communities (ASX: LIC) -0.47% to $4.22 September-quarter new-home sales fell 22% year-on-year as Victorian downsizers delayed purchasing decisions.
- Gold: Rebounded to US$4,200/oz / +1.8%
- Iron Ore: Fell to US$90.70 / -0.6%
- Brent crude: Around US$102.90/bbl / -1.2%
- S&P 500 E-mini futures: +23.50pts / +0.30% | Dow Jones futures: +105.00pts / +0.20%