- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
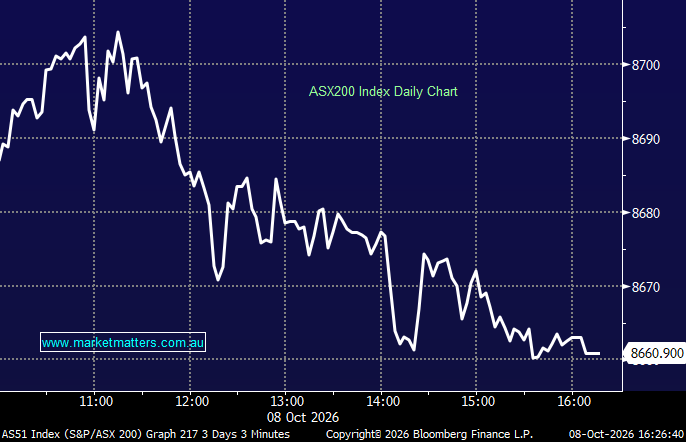
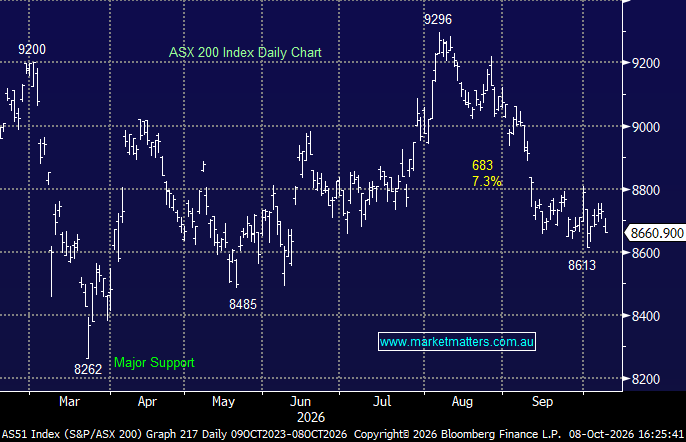
The ASX was hit by another bout of selling on Thursday as surging global bond yields and weakness across the resources sector weighed on the market. Today’s session was less about broad-based capitulation and more about defensive rotation. Energy was the standout, while Staples, Utilities and Telcos also attracted buying. The main driver was the continued rise in bond yields. Australia’s 30-year yield reached 5.88%, the highest since 2016, while the 10-year sat at 5.40%. With 10bp daily moves becoming increasingly common, the higher-rate environment remains a key drag on equity valuations locally and abroad.
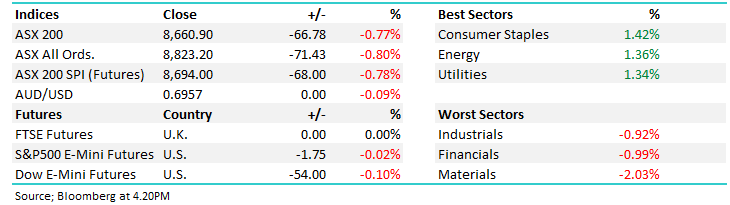
- ASX 200: -66.78pts / -0.77% to 8,660.90
- AUD/USD: 0.6957 / -0.09%
- Best sectors: Consumer Staples +1.42%, Energy +1.36%, Utilities +1.34%
- Worst sectors: Industrials -0.92%, Financials -0.99%, Materials -2.03%
- The uranium sector provided a good example of just how quickly sentiment can change — after surging yesterday following Google’s 3.6GW nuclear power agreement with Constellation Energy, the sector gave back most of those gains today.
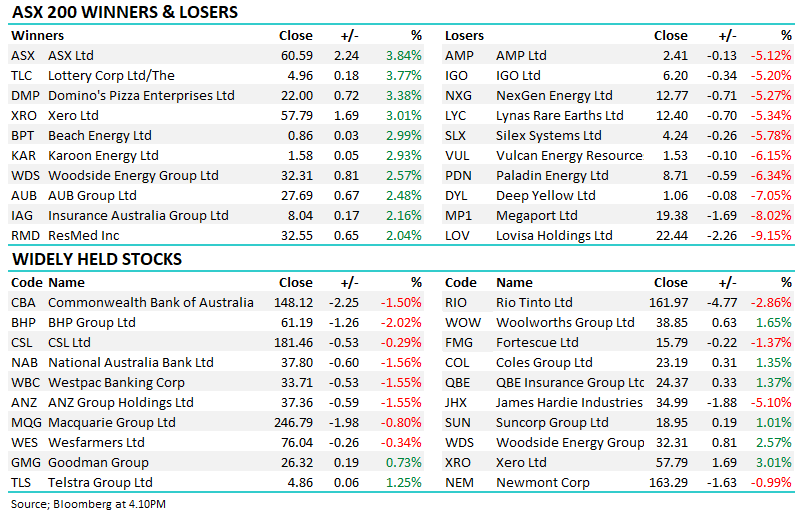
- Deep Yellow (ASX: DYL) -7.05% to $1.05 and Silex Systems (ASX: SLX) -5.78% to $4.24 both fell sharply, Paladin Energy (ASX: PDN) -6.34% to $8.71 (held in Active Growth Portfolio), Boss Energy (ASX: BOE) -4.43% to $1.51 and NexGen Energy (ASX: NXG) -5.27% to $12.77 (held in Emerging Companies Portfolio) lower as well.
- Maas Group (ASX: MGH) -22.38% to $4.96 fell by as much as 30% earlier in the session, following reports that the proposed Firmus IPO could be reworked after overseas investor demand fell short. Maas has a 3.2% stake in Firmus and also supplies the data-centre operator through its JLE subsidiary, meaning a weaker IPO could potentially affect both the value of its investment and the outlook for its associated contracts.
- ASX Ltd (ASX: ASX) +3.84% to $60.59 after UBS upgraded its outlook and lifted its target to $65.50, citing strong FY27 futures activity. Futures volumes rose 33% year-on-year in the September quarter.
- Xero (ASX: XRO) +3.01% to $57.79 (held in Active Growth Portfolio) after Citi placed the stock on a 90-day upside catalyst watch, expecting strong first-half revenue growth and potential margin upside from cost control.
- HUB24 (ASX: HUB) +1.50% to $64.36 (held in Active Growth Portfolio) and Netwealth (ASX: NWL) +0.71% to $17.06 both upgraded to Buy by UBS after their substantial post-Budget sell-offs, with HUB24 down around 34% and Netwealth 35% this year.
- Fortescue (ASX: FMG) -1.37% to $15.79 (held in Active Income Portfolio) reported September-quarter shipments of 46.8Mt, down 6%, while net debt surged to US$2.8bn following dividends, capex and a working-capital build. FY27 guidance was maintained.
- Elevra Lithium (ASX: ELV) -4.04% to $4.99 secured a three-year spodumene offtake agreement with LG Energy Solution covering 240,000dmt, with optional volumes of up to another 90,000dmt.
- Ramelius Resources (ASX: RMS) -0.80% to $3.71 Q1 gold production was 48.8koz, with wet weather delaying some Penny shipments, while cash and gold increased 18% to $768m.
- Brent crude: around US$102.60/bbl / +2.4%
- Gold: around US$4,130 / +0.5%
- Iron Ore: US$91.80 / +0.4%
- S&P 500 E-mini futures: +1.25 points / +0.02% | Dow E-mini futures: +30 points / +0.06%