- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
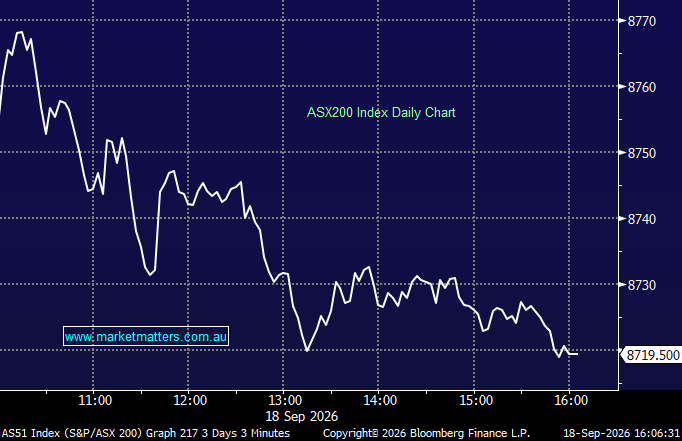
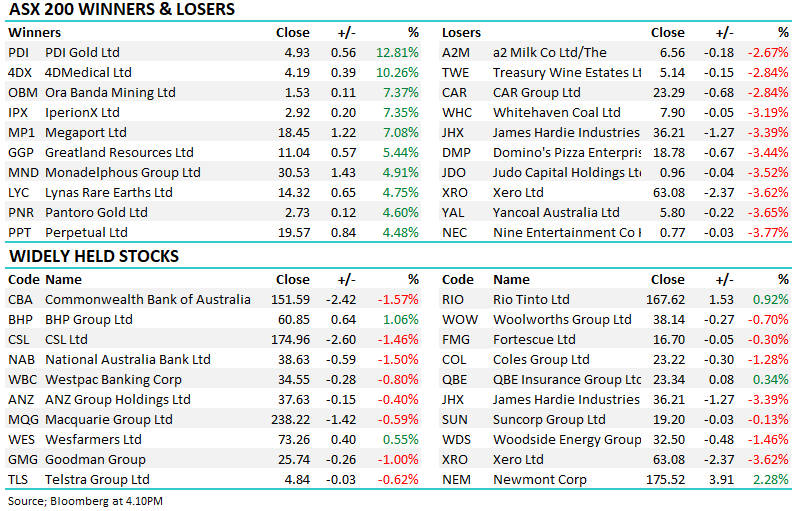
The ASX finished modestly lower, giving back a +40pt early gain as the market digested hawkish commentary from the RBA as Michele Bullock addressed parliament today. Governor Bullock indicated the Board will consider whether the three rate increases already delivered this year are sufficient to return inflation to target, pushing market pricing for a September hike to around 95%. Only four of 11 sectors finished higher, with a solid bounce in miners, and gold stocks particularly strong, though more than offset by weakness across Staples, Energy, Banks and Real Estate.
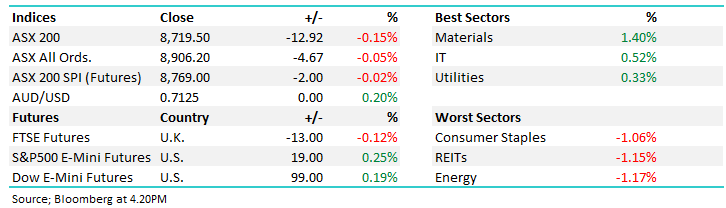
- ASX 200: -12.92pts (-0.15%) to 8,719.50
- AUD/USD: 0.7125, flat
- Best sectors: Materials +1.40%, IT +0.52%, Utilities +0.33%
- Worst sectors: Energy -1.17%, REITs -1.15%, Consumer Staples -1.06%
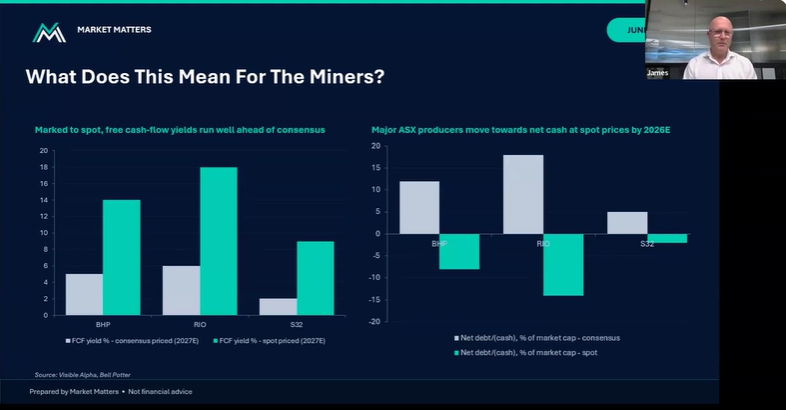
- Materials +1.40% was the standout sector as miners bounced following a sharp recent sell-off. Copper and gold rallied over the past 24 hours driving gains – BHP (ASX: BHP) +1.4% to $61.05, Rio Tinto (ASX: RIO) +0.84% to $167.49 and South32 (ASX: S32) +1.86% to $4.93 were among the stronger performers. BHP held in the Active Growth and Income Portfolios. S32 held in the Active Growth Portfolio.
- Technology +0.52% delivered a welcome bounce for beaten-up names – Megaport (ASX: MP1) +7.6% to $18.54 and NextDC (ASX: NXT) +2.71% to $11.36% led the way.
- Utilities was one of few areas to finish higher, with AGL Energy (ASX: AGL) +0.72% to $8.45 and APA Group (ASX: APA) +1.39 % to $10.93 firmed with the sector benefitting from its stable earnings profile in the face of a higher-for-longer rates environment.
- Financials remained a drag, with CBA (ASX: CBA) -1.03% to $152.43, NAB (ASX: NAB) -1.91% to $38.47, Westpac (ASX: WBC) -0.23% to $34.75 and ANZ (ASX: ANZ) -0.26% to $37.68 all weaker. ANZ held in the Active Growth and Income Portfolios. WBC held in the Active Income Portfolio.
- Maas Group (ASX: MGH) +12.72% to $6.38 received FIRB approval for the sale of its Construction Materials division to Heidelberg Materials for up to $1.703bn, clearing another key condition ahead of the deal. Shareholder approval is due at the 24 September AGM, with settlement expected in October.
- Arafura Rare Earths (ASX: ARU) +11.76% to 19c extended its binding offtake agreement with a global wind turbine manufacturer, covering 500tpa of NdPr oxide equivalent for five years, with potential to extend to eight years.
- Abacus Group (ASX: ABG) -1.18 % to 83.5c agreed to sell its entire 19.6% stake in Storage King Group (ASX: SKG) -1.86 % to $1.05 for $284.8m — the deal comprises a 10.37% stake sold to Ki Corporation at $1.20 per security, an 11.6% premium to the prior close, with the remaining 9.23% sold through an institutional block trade at $1.00.
- Macmahon (ASX: MAH) +6.07% to $1.05 rallied after agreeing to acquire Aspect Engineering Solutions for a headline enterprise value of $75m. Aspect generated $15.2m of FY26 EBIT, and the acquisition is expected to be around 6.2% EPS accretive before synergies.
- Insurance Australia Group (ASX: IAG) -1.11% to $8.01 will be shopping around for a new auditor, sacking KPMG after 25 years, launching a competitive tender process that excludes its KPMG as a candidate.
- Gold: $4,385.59 / +1.01%
- Brent crude: $102.61 / -2.1%
- Iron Ore: $97.15 / +0.83%
- S&P 500 E-mini futures: +19.00pts / +0.25%
- Dow E-mini futures: +99.00pts / +0.19%
- FTSE futures: -13.00pts / -0.12%