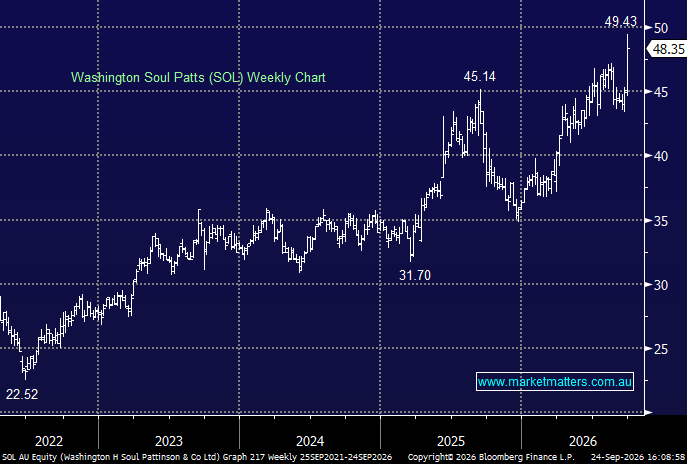
SOL +6.2% Produced a solid FY26 result as profits jumped, though headline A$2.19bn number tells only part of the story, with a large chunk coming from the Brickworks merger and other non-recurring items.
Key results:
- Revenue of A$1.49bn, more than double the prior year.
- Net profit (NPAT) of A$2.19bn, up from A$364m, with a significant contribution from the Brickworks merger-related tax benefit.
- Pre-tax NAV of A$13.7bn, up 10%.
- Net cash flow from investments of A$572m, up 12%.
- Final dividend of 63cps, up 6.8%, taking the full-year dividend to $1.11, up 7.8%.
The quality of the headline profit is less important than the underlying portfolio performance. Operating NPAT was A$319m, portfolio gains contributed A$343m, while non-recurring items added A$1.5bn, including a A$1.3bn day-one accounting gain and tax cost-base reset from the Brickworks merger. This was partly offset by A$221m of impairments, restructuring and other costs. Looking forward, management expects an uncertain environment around interest rates and bond yields, but has already approved another A$662m of offshore private market commitments, highlighting the firepower created by the post-merger balance sheet.
MM’s view: We own SOL in the Active Income portfolio, and the attraction here is not the A$2.19bn headline profit — much of that simply isn’t repeatable. It’s the combination of a stronger balance sheet, a growing and increasingly diversified investment portfolio, rising NAV and a steadily growing dividend. The Brickworks merger has delivered exactly what we wanted to see: a cleaner capital structure and more capital to put to work, without sacrificing Soul Patts’ disciplined approach to investing. With another A$662m of offshore private market commitments approved and the dividend growing at a healthy clip, we remain comfortable owning SOL as a long-term income holding, with some capital growth to boot.
MM remains long and bullish SOL
Add To Hit List