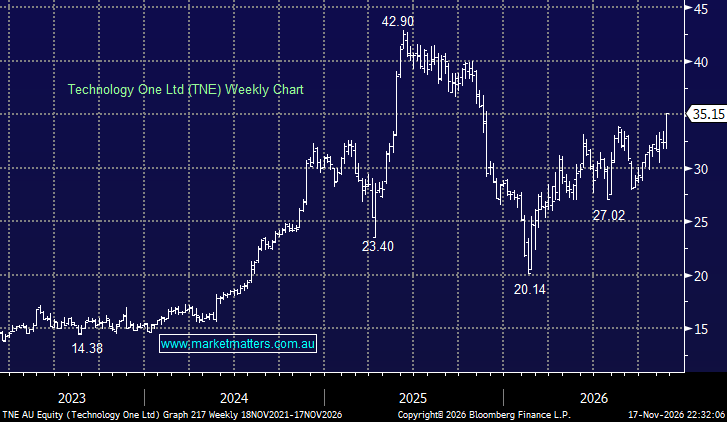
TNE was by far the best-performing stock on the ASX 200 on Tuesday, soaring almost 9% while the index suffered deep triple-digit losses. As we touched on earlier, the ASX software stocks have enjoyed a resurgence this month, and TNE was supported by Xero and Life360 on Tuesday, with only AI-correlated Megaport (-6.6%) noticeably dragging the chain. As we mentioned earlier, it will be another test today after US software names fell ~3% overnight, raising the question whether ASX names have been benefiting from tech flow out of the US or simply the recent global trend of money switching from semiconductors into software – a bit of both, we think.
TNE is a company that some people struggle to understand; it makes money by developing cloud-based enterprise resource planning (ERP) software that helps government departments, local councils, universities and businesses manage essential operations, including finance, payroll, human resources, procurement, student administration and asset management. It makes most of its money through recurring Software-as-a-Service (SaaS) subscriptions, charging customers an ongoing fee to access, host, maintain and upgrade its software, with implementation and support incorporated into its newer SaaS+ offering.
One of the standout facets of TNE’s business is the sticky nature of its largely govt. facing clients, with a churn rate of just 0.8% in FY26 while existing customers increased their spending by +16% on average after accounting for lost revenue from departing customers. Yesterday’s FY26 result was solid, with all major earnings measures broadly in line with consensus, and with positive growth as the catalyst for the gains:
- Net income increased 19% to $163.4m, pretax profit rose 20% to $217.6m, and total ARR grew 18% to $652.1m, while revenue increased 12% to $680.8m.
- Free cash flow rose 3% to $190.5m, and the company rewarded shareholders with a 62.5% increase in its final dividend to 32.5c per share – the company is in a reassuring net cash position.
Importantly, there were also encouraging signs in the growth outlook, particularly internationally and through its newer SaaS+ (Plus) offering. UK ARR increased 18% to $61m, while Plus generated 100 sales in FY26, reached $1m in ARR within four months of launch and secured more than $30m in additional product commitments from existing customers. Management reaffirmed its ambition to reach $1bn in ARR by FY30, without requiring geographic expansion, suggesting there remains considerable scope to deepen revenue from its existing customer base.
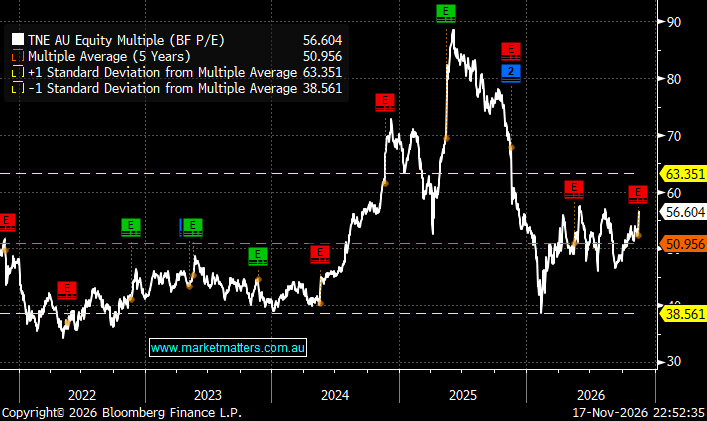
TNE is clearly a first-rate operation; the big question is whether the $11.5bn company can justify its 50x valuation, actually its average of the last 5 years, something other software companies have failed to maintain. Let’s assume the company can achieve, and it’s a strong possibility, $1bn in ARR in FY30; how will the numbers look then:
- All things being equal, the current NPAT of $163mn in FY26 should kick up to ~$250mn if margins remain constant, but the Saas leverage is likely to improve this materially.
On a simple back-of-the-envelope calculation, the average ASX 200-valued company that’s enjoying NPAT of, say, $400mn has a market cap of around $14bn, illustrating the potential upside in TNE, especially during periods of optimism towards growth and software stocks – lower bond yields would help this.
chart

Technology One (TNE) Historical PE Valuation- Source: Bloomberg
chart
Technology One (TNE) Historical PE Valuation- Source: Bloomberg
As we said before TNE is a world class company with the question being was yesterday’s result good enough to rerate the stock significantly above its current average valuation; probably is our answer, but the risk/reward of chasing the stock above $35 is hard to embrace.
- We can see TNE testing ~$40 into 2027 but are reticent to chase into strength above $35, although the statistics say we probably should!
MM is cautiously bullish towards TNE around $35
Add To Hit List