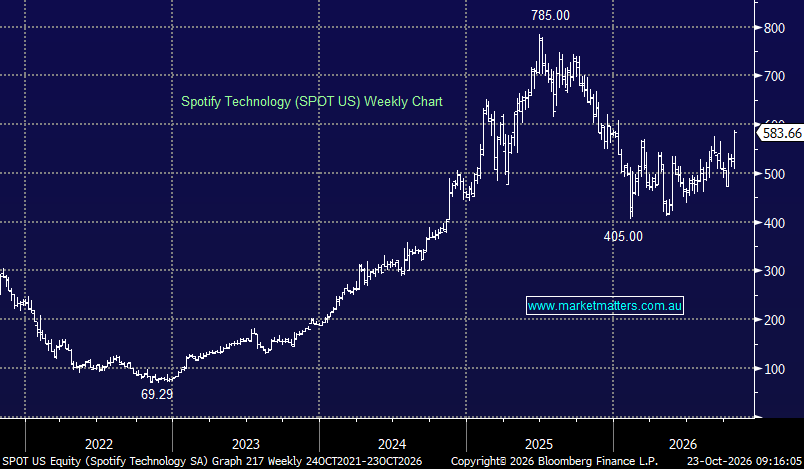
Spotify (SPOT) delivered a solid third-quarter result overnight, with user and subscriber growth holding up well and the margin outlook coming in better than feared. Revenue was broadly in line, but the market focused on improving profitability and healthy premium subscriber trends, sending the shares up over 11%.
Key Q3 highlights:
- Revenue: €4.97bn, up 16% YoY, broadly in line with expectations.
- Operating income: €672m, up 15% YoY.
- Gross margin: 33.0%, up from 31.6% and slightly ahead of expectations.
- Monthly active users: 788m, up 11% YoY.
- Premium subscribers: 306m, up 9% YoY and slightly ahead of consensus.
- EPS: €2.48 versus €3.28 a year ago.
The main concern going into the result was rising operating expenditure, particularly around marketing and cloud/AI investment. Costs did increase materially, but management characterised much of this spending as temporary, while 4Q guidance suggests margins remain on an improving trajectory. Spotify expects 316m premium subscribers, a 33.8% gross margin and €820m of operating income in Q4, with both subscriber and margin guidance slightly ahead of expectations.
The weak spot remains advertising, where growth continues to lag the premium business. However, that matters less while subscriber growth remains resilient and Spotify continues to demonstrate pricing power and improving unit economics.
MM’s view: We think this was a constructive result. The key debate around Spotify has shifted from whether it can grow, to whether it can convert that growth into sustained profitability. Q3 moved the story in the right direction, with strong subscriber growth, expanding gross margins and a better-than-feared Q4 outlook.