We think Praemium (PPS) is an interesting takeover candidate, with recent corporate activity adding weight to the argument. Bell Financial Group (BFG), the owner of Bell Potter, approached PPS in September with a non-binding, all-scrip merger proposal, which was subsequently rejected. While discussions have ceased, the approach highlights the strategic appeal of PPS, and we suspect Bell may not be the only interested party.
PPS is a wealth management platform and portfolio administration business, with particular strength in the high-net-worth (HNW) market, supporting complex portfolios including direct equities, international investments and alternative assets. It’s an attractive niche, and one that larger competitors HUB24 (HUB) and Netwealth (NWL) are increasingly targeting.
Similar to Market Partners, our wealth management partner operated by James and his team, Bell Potter already uses PPS’s Scope+ platform to administer more than 2,200 client portfolios, a relationship that added approximately $6bn in funds under administration (FUA). Bringing this technology in-house would make strategic sense for Bell, providing a broader wealth management offering and potential operating synergies.
The underlying business continues to grow, with FY26 FUA increasing 21% to $77.9bn, while underlying earnings (EBITDA) rose 14.5% to $32.1m. PPS has also undertaken a technology restructure targeting around $9m in annual cost savings, providing further scope for margin improvement.
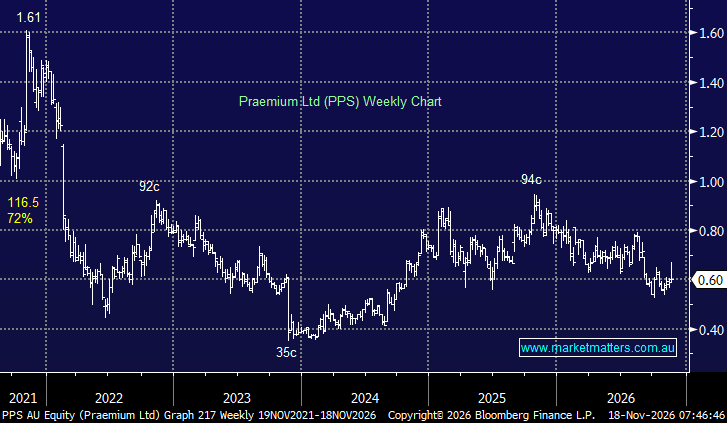
Could someone else come knocking? We think so. Both HUB and NWL offer compelling strategic combinations, with an acquisition delivering immediate scale in the attractive HNW segment, removing a competitor and creating opportunities to consolidate technology and administration costs. Netwealth has already tried, lobbing proposal in 2021 valuing PPS at ~$1.50 per share, which was rejected.
The timing is also interesting, with activist investor Viburnum emerging as a substantial shareholder, significant board changes, the appointment of Matthew Quinn as Chairman and the departure of long-serving CEO Anthony Wamsteker. Quinn previously chaired Class when it was acquired by HUB24, adding another interesting dimension to the story.
At around 60c, PPS has a market capitalisation of ~$300m, making it a relatively digestible acquisition for several potential suitors. If corporate interest does come to fruition, we think PPS could be worth $1.00–1.40 per share, factoring in the potential earnings benefits available to an acquirer.
Ultimately, we see a credible takeover argument for PPS, with Bell’s recent approach demonstrating genuine corporate interest. While the initial proposal was rejected, we wouldn’t rule out Bell returning with an improved offer, or HUB and NWL taking a closer look, particularly given the valuation gap between PPS and its larger peers. Netwealth (NWL) has a market cap of ~$4.5bn while HUB is bigger at $6.1bn.
As we often say at MM, takeovers aren’t a reason in themselves to own a stock, but they’re worth considering when the underlying investment thesis remains attractive. We believe PPS fits that description, with a growing HNW franchise, scope for margin improvement and several logical potential acquirers.
MM is bullish PPS ~60c
Add To Hit List