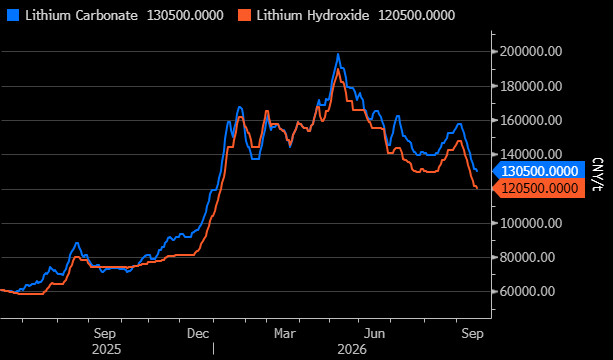
Lithium has endured a brutal September, with carbonate prices falling ~17%, driven initially by a shock revision to Chinese inventory data. SMM expanded its survey methodology, causing reported stockpiles to more than double from 78,800 tonnes to 175,000 tonnes; while much of the increase reflected the broader dataset rather than lithium suddenly appearing in warehouses, it challenged the improving supply-demand story and triggered a sharp repricing, with futures falling more than 14% over just three sessions.
The second leg lower came from the demand side after China reportedly temporarily suspended construction of new power and energy-storage battery projects pending a year-end review of industry capacity. This was arguably more concerning than the inventory revision because it raised questions over future battery demand at a time when excess manufacturing capacity is already an issue. Encouragingly, the sell-off lost momentum last week, while SMM expects Chinese battery production to rise 9% in September, helped by strong demand for batteries used in energy storage.
However, lithium carbonate remains around 120% above its June 2025 low despite falling more than 30% from May’s peak of close to 200,000 yuan/t. Putting the recent move into perspective, the market is undergoing a correction following a strong recovery rather than revisiting last year’s lows, with supply discipline, EV demand and rapidly growing energy-storage consumption still providing support—although the latest Chinese developments have clearly increased uncertainty around the near-term outlook. That said, related stocks are struggling with Albemarle (ALB US), one of the world’s largest lithium producers, falling another -3.6% on Friday night, taking the stock down to fresh 2026 lows with no obvious support in sight.
- We cannot see lithium prices improving until the uncertainty from China is removed.