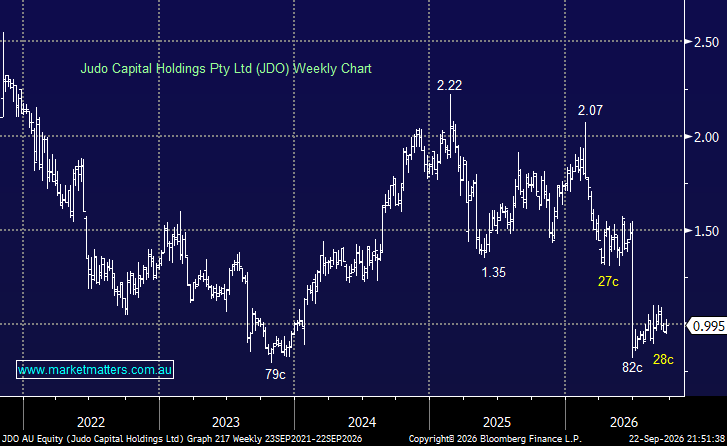
JDO was our “Chart of the Week” in Monday’s report, but a chart is nothing without some fundamental context behind it. Members may recall how JDO was hammered in June after downgrading FY26 earnings expectations and sharply lifting provisions for credit losses, more than offsetting an otherwise encouraging improvement in its net interest margin outlook here – it’s not often we see an ASX 200 stock almost halve in one day!
On Monday we touched on how JDO could bounce 40-50% if it makes new 2026 lows here, but some important nuances need to be understood before we consider this $1.1bn SME lender. Firstly, after June’s calamity, we must have a clear handle on the company’s lending book:
JDO has gross loans of approximately $14.7bn as of June 2026, up from $13.4bn six months earlier. Importantly, the loan book is relatively diversified across industries rather than being dominated by property: at December 2025, Real Estate represented 24%, followed by Accommodation & Food Services (12%), Residential Mortgages (9%), Agriculture (8%), Construction (7%), Health Care (6%), Retail (6%), Financial & Insurance Services (6%) and Manufacturing (5%), with the balance spread across several smaller sectors.
Hence, around three-quarters of Judo’s lending sits outside Real Estate, reducing its reliance on any single industry. The 7% exposure to Construction should also not be confused with property development, with JDO noting that it predominantly represents businesses servicing the construction industry. Encouragingly, as the loan book expanded to $14.7bn by June, Real Estate exposure actually declined from 24% to 23%, suggesting growth has continued without increasing concentration in the area currently attracting the most attention from investors.
JDO’s strategy is to broadly mirror the Australian economy in its sectoral mix, with deliberate underweights in agriculture and construction relative to their economic share. Elevated impairment levels have been concentrated in a small number of industries rather than being broad-based, and the bank applies targeted management overlays to more challenged sectors.
- From a sector perspective, we like JDO’s diversification as we enter a 5% bond yield world.
Importantly, JDO’s single-name concentration is low. The largest single exposure has rarely exceeded 1% of gross loans and advances, and is expected to remain stable or trend lower as the portfolio grows. Additionally, 98% of customers have facilities below A$20 million.
Judo’s FY26 presentation confirmed 19 customer groups above $50m, including six above $100m. Those 19 groups represented about 10% of the loan book, but they are heavily secured: the >$50m exposures were backed by 58 SME trading businesses and 131 freehold properties, with 97% having property security.
- From a key loan risk perspective, we think JDO is pretty well diversified.
However, everything clearly isn’t perfect, as we saw in June, and the market’s confidence in JDO hasn’t fully been restored, with the stock still trading down more than 40% YTD.
There are plenty of risks in this type of business; credit quality remains the main issue for Judo following the sharp increase in impairments during FY26. Importantly, the deterioration has been concentrated in a relatively small number of industries rather than spread broadly across the loan book. According to JDO, the average probability of default across Judo’s performing portfolio also remained stable through FY26, suggesting the higher impairments were driven more by specific pockets of stress than a widespread deterioration in SME credit quality.
That said, the market will want evidence that FY26 represented the high-water mark for bad debts. Consensus is currently forecasting a cost of risk at around 70bps in FY27, an improvement from 80bps in FY26 but still well above Judo’s 50bps through-the-cycle target. Following June’s credit-quality shock, the FY26 result, where profit still increased 29% to $111m, included greater disclosure around the composition and security of the loan book as management sought to reassure investors. The key issue from here is less about loan growth; the chart below shows they’ve got this covered- and more about whether impairments normalise as expected.
- Growing their loan book has been an impressive metric for JDO, with gross loans having grown from $6.1bn in FY22 to $14.7bn in FY26, a ~141% increase over 5 years— with consensus forecasting continued growth to $18.4bn by FY2028.
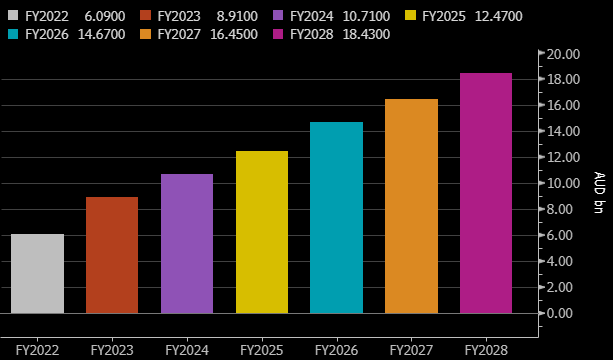
chart

Judo Bank (JDO) Loan Growth – Estimate: Source: Bloomberg
chart
Judo Bank (JDO) Loan Growth – Estimate: Source: Bloomberg
JDO is building a much larger buffer against potential bad debts as its SME loan book grows and matures. Loan-loss reserves have increased from just $22m in FY22 to $166.9m in FY26, with consensus expecting them to reach around $314m by FY28. As a proportion of gross loans, that represents an increase from roughly 0.36% to 1.14%, with the ratio forecast to reach around 1.7% by FY28.
Importantly, this does not mean JDO expects to lose $314m. Rather, the reserve represents money set aside to cover potential future loan losses, similar to an insurer and future claims. Annual impairment charges- the amount flowing through the P&L each year – have risen more gradually from $40.2m in FY22 to $96m in FY26, with consensus forecasting around $110m by FY28.
- The key takeaway is that Judo is carrying a progressively larger safety buffer as its relatively young loan book matures, reflecting a more conservative recognition of credit risk.
It’s going to take time for JDO to regain the market’s trust, especially with the RBA set to start hiking again next week, a huge headwind for many small businesses. However, we believe the market’s pricing in a worst-case scenario, leaving room for positive surprises, with the valuation particularly attractive back around 80c.
- We like the risk/reward towards JDO if we see another washout as the RBA hikes rates.
MM is bullish towards JDO in the 75-80c range
Add To Hit List