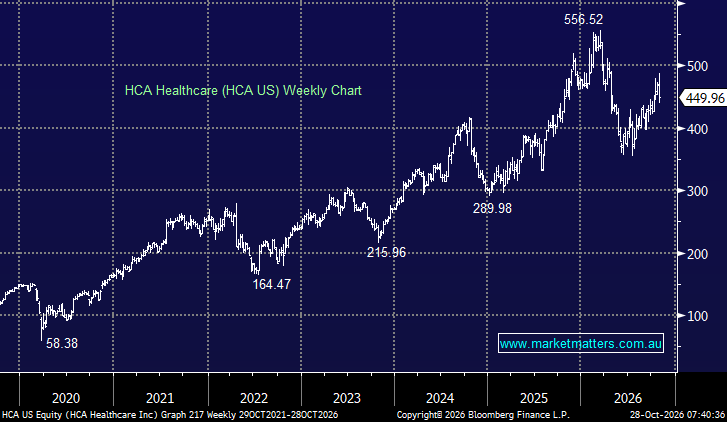
HCA Healthcare (HCA) initially traded higher overnight after delivering a better-than-expected third-quarter result, but the shares reversed through the session to finish 3.3% lower after management flagged that 2027 earnings are likely to be broadly consistent with 2026, relative to a +1.5% increase baked into consensus. That outlook mildly overshadowed an otherwise solid quarter.
Key 3Q highlights:
- Adjusted EPS: US$7.22 vs US$6.66 expected.
- Revenue: US$19.85bn, up 3.6% YoY vs US$19.31bn expected.
- Adjusted EBITDA: US$3.92bn, up 1.2% YoY.
- Net income: US$1.58bn, down 3.9% YoY.
- FY26 EPS guidance maintained at US$28.70–30.50.
- FY26 EBITDA guidance maintained at US$15.4–16.1bn, with management now expecting results toward the upper half of the range.
The quarter itself was solid. Volumes were good, cost execution held up and stronger supplemental payments helped absorb pressure from the individual health-insurance exchange market. Most brokers called the result a clear beat.
In terms of 2027 outlook, CEO Sam Hazen said earnings next year are expected to be generally consistent with 2026, with continued pressure on payer mix as some patients lose insurance coverage. That effectively removed the prospect any meaningful near-term earnings growth, though the market only positioned for a mild uplift, but it explains why the stock gave back its early gains.
- We own HCA and still view it as a high-quality operator. The core business is performing well; the issue is that policy changes and payer-mix pressure are limiting earnings growth.
MM remains long & bullish HCA ~$US450
Add To Hit List