A shorter report on the questions front this week as school holidays get underway. To those going away, have a fun and safe break with family and friends.
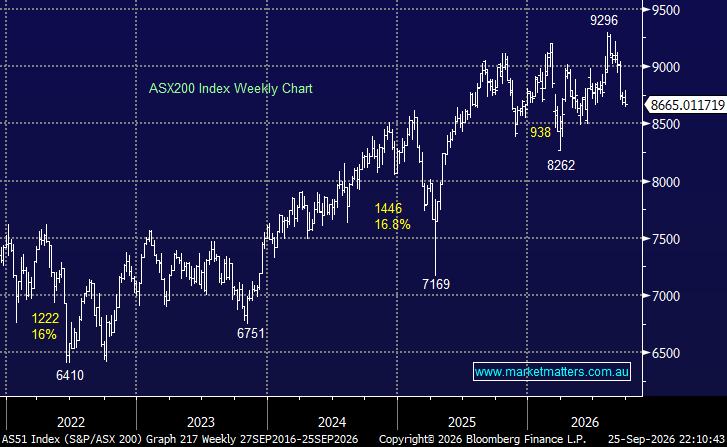
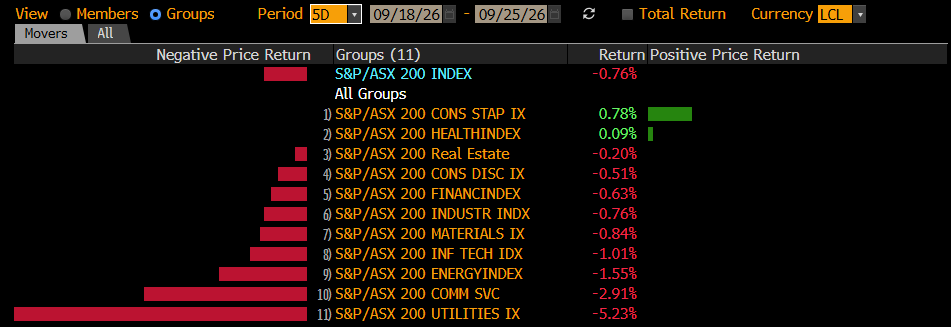
The ASX 200 retreated another 0.8% last week despite a softening oil price and gains on Wall Street. The local market has lost its “Mojo” at the moment, as is the way in the month of September, with investors adopting an if-in-doubt sell approach to news. With the RBA set to hike rates next week, the US-Iran war pushing up oil prices, bond yields soaring, and the local housing market falling, there are plenty of reasons to keep investors on the sidelines, but we believe it will deliver opportunity in the coming weeks.
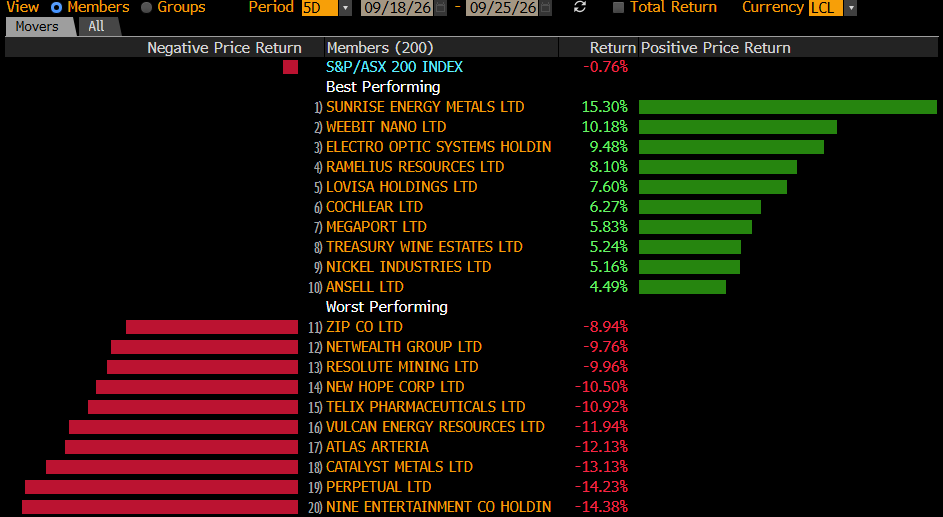
The best and worst-performing stocks last week were an mixed cohort, with no obvious trend:
Winners: Sunrise Energy (ASX: SRL) +15%, Weebit Nano (ASX: WBT) +10%, Electro Optic Systems (ASX: EOS) +9%, Ramelius Resources (ASX: RMS) +8%, Lovisa (ASX: LOV) +8%, Cochlear (ASX: COH) +6%, Megaport (ASX: MP1) +6%, and Treasury Wine (ASX: TWE) +5%.
Losers: Nine Entertainment (ASX: NEC) -14%, Perpetual (ASX: PPT) -14%, Catalyst Metals (ASX: CYL) -13%, Atlas Arteria (ASX: ALX) -12%, Vulcan Energy (ASX: VUL) -12%, Telix Pharma (ASX: TLX) -11%, New Hope (ASX: NHC) -11%, and Resolute Mining (ASX: RSG) -10%.
Weekly snapshot: Last week saw the ASX 200 consolidate recent losses as opposed to driving lower:
- We had to wait until Thursday to see the market move by more than 0.5%, falling 0.7%, despite softer employment data paring back rate hike bets – just.
- Credit markets are pricing in a 91% chance of an RBA 0.25% rate hike this week; it could prove to be the bad news we need to see before markets regain some optimism.
- The ASX 200 notched a fresh 4-month low on Friday as consumer discretionary and tech stocks weighed heavily on the market.
In the coming week, the RBA interest rate decision and Australian CPI are the pivotal local catalysts for the ASX 200, while US unemployment (NFP) and PCE data dominate the S&P 500, and both indices remain sensitive to oil price moves and any developments on the US-Iran diplomatic war.
Overseas markets rallied into the weekend in the absence of fresh negative news. In Europe, the German DAX (+0.6%) and UK FTSE (+0.1%) both finished on the correct side of the ledger. In the US, the S&P 500 (+0.5%) and NASDAQ (+0.4%) rallied back within striking distance of their all-time highs.
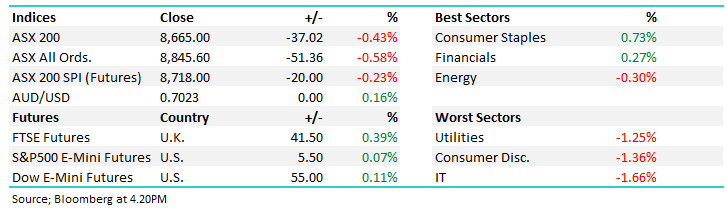
- The SPI Futures are calling the ASX 200 to open flat on Monday despite the strong session on Wall Street.