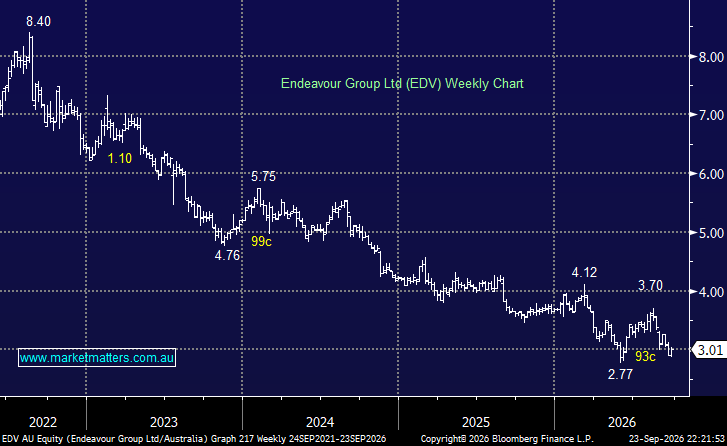
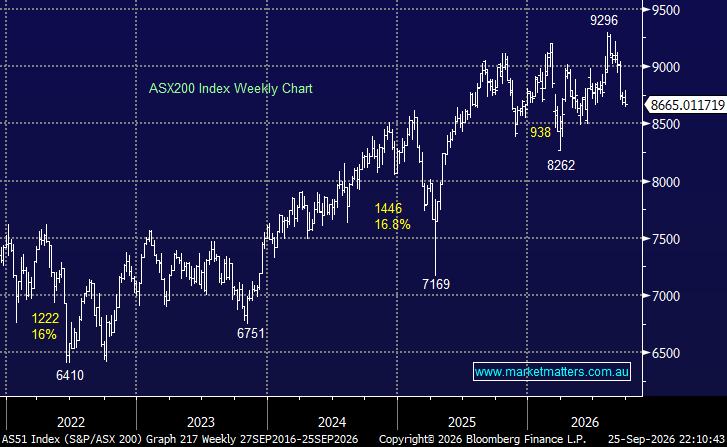
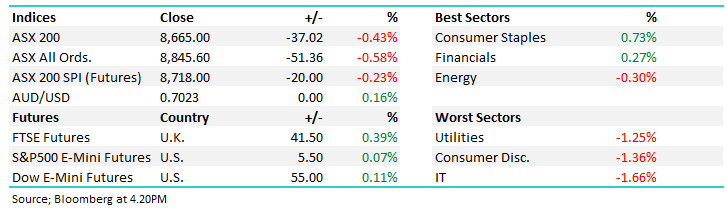
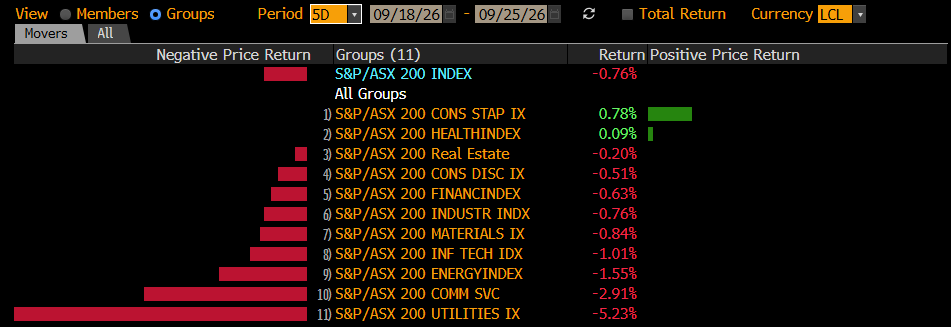
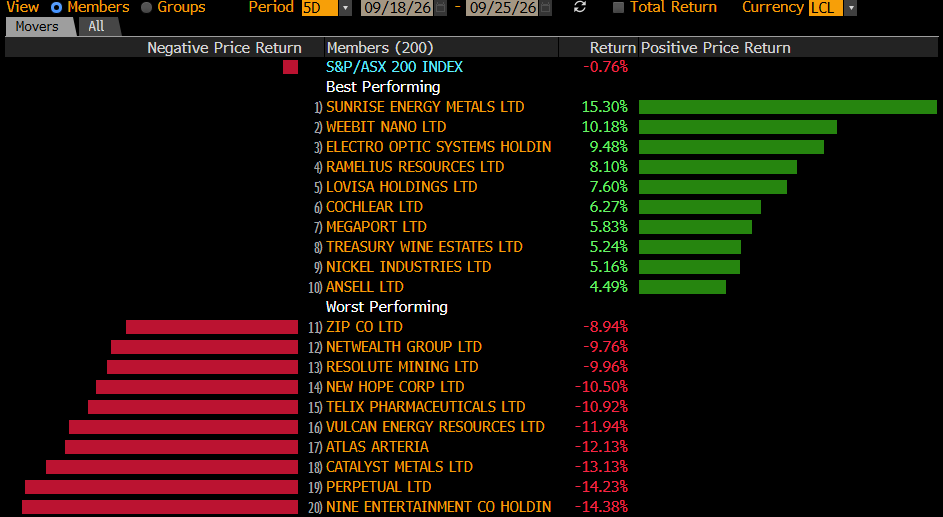
EDV has fallen around 12% over the past year, significantly underperforming both the ASX 200 and Consumer Staples (+12.5%). Unlike many of the market’s recent losers, EDV’s weakness has been driven almost entirely by falling earnings rather than multiple compression, with forward EPS cut by around 33% from $0.247 to $0.166 as aggressive pricing and promotional activity across Dan Murphy’s and BWS squeezed retail margins. Surprisingly, EDV’s forward P/E has expanded from 13.7x to 16.1x, suggesting investors are already looking beyond the current earnings decline towards a potential FY28–29 recovery.
FY26 reinforced the challenge, with underlying EPS falling to 20.2c from 23.7c and the final dividend slashed by ~80%, while elevated FY27 investment means a meaningful earnings recovery may still be some way off. The turnaround now rests on rebuilding profitable retail growth, extracting $300m of targeted cost savings by FY29 and improving returns from the Hotels division, where management plans to accelerate venue refurbishments. In short, EDV has avoided a major valuation de-rating, but earnings now need to catch up with the recovery already being priced into the multiple.
- We can see EDV finding support at new lows, but it still needs to deal with a structurally weak backdrop as people drink less – a more than 5% fully franked yield will provide support here.
MM is cautiously bullish towards EDV around $2.70
Add To Hit List