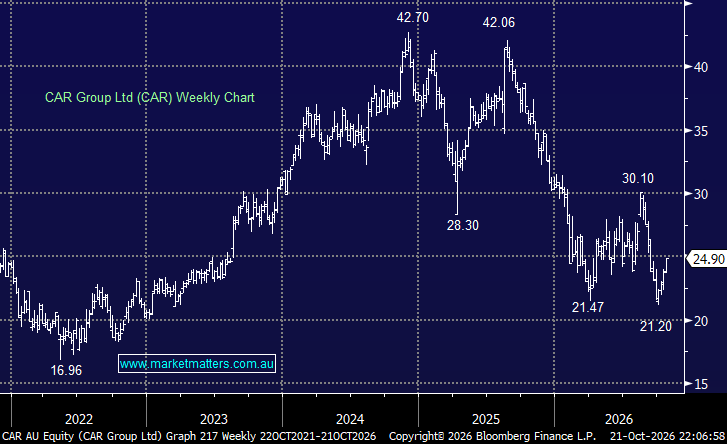
CAR Group (CAR) rose +3.5% on Wednesday having followed MM’s roadmap through most of 2026, covered here, along with its solid August result, with FY26 adjusted profit increasing 8% to $407m, while FY27 guidance is for 11–14% revenue growth. We see CAR Group’s earnings growth resting on three key drivers: AI monetisation, pricing power and international expansion. UBS forecasts margins to expand by an average of 80 basis points annually from FY27 over the following three years, supported by operating efficiencies and revenue growth. AI is already improving the customer experience, with conversational search lifting session-to-lead conversion by an impressive 26%, while new dealer-facing tools and lead-generation products are creating additional revenue opportunities.
- Ironically, the very reason CAR halved from its 2025 high is improving the business and user experience.
Internationally, North America, Latin America and Asia are important growth engines, with the US business expected to return to double-digit growth. CAR Group is also integrating its Americas operations to share technology and product innovations more efficiently across markets.
- In FY26, almost 60% of CAR’s revenue was from overseas, illustrating the extent of the company’s successful global expansion.
AI should lower software development and customer service costs, supporting margin expansion while freeing up resources for further innovation. The combination of pricing power, international growth and operating efficiencies provides a pathway to stronger earnings through to 2030.
The dominant risk to CAR is AI-driven pricing power erosion, a structural concern the market has already heavily priced in to the stock. In the short term, the main items that could weigh on the share price are macro-driven volume softness (particularly in private listings and the US RV market), margin contraction from international investment in marine and Korea, and currency headwinds that could undercut constant-currency guidance. Also, as we mentioned earlier, if bond yields take another leg higher, it will likely weigh on all growth stocks, such as CAR. However, overall we believe the stock already has got a lot of bad news baked into the cake with its EV/EBITDA multiple currently ~32% below its 5-year average.
- We can initially see CAR testing the $28-30 area, or 10-15% higher.
MM is bullish towards CAR below $25
Add To Hit List