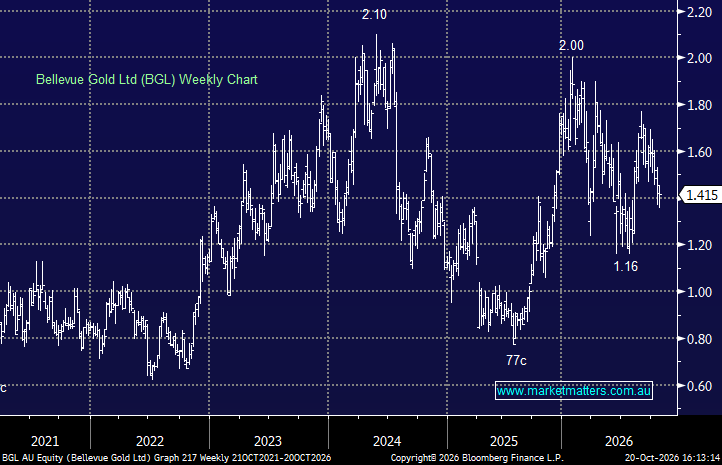
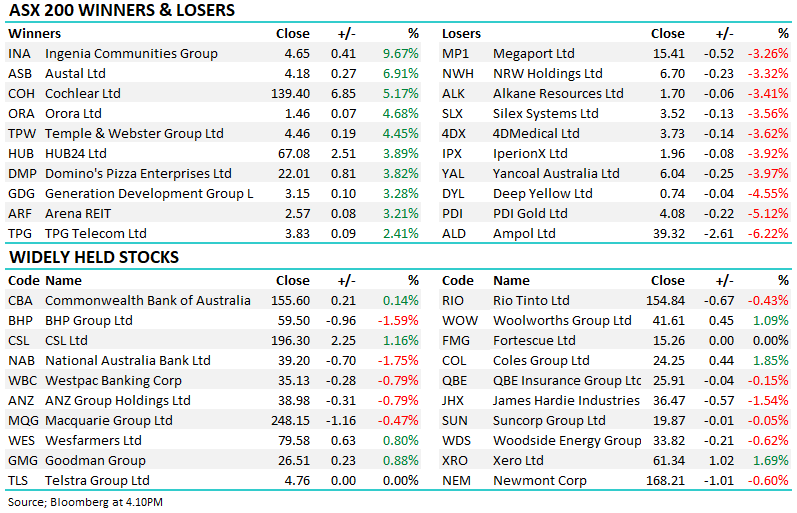
BGL -1.05% was mildly lower, though most gold stocks were, after a softer-than-expected September quarter, with production falling 15% QoQ to 35,585oz as the new mining contractor ramped up more slowly than planned.
Key 1Q27 numbers:
- Gold production: 35,585oz, down 15% QoQ but up 22% YoY.
- Gold sales: 35,979oz, down 12% QoQ.
- Realised gold price: A$4,980/oz, up 19% QoQ.
- Cash and gold on hand: A$213m, up from A$206m at June-end.
- FY27 production guidance maintained at 150,000–170,000oz.
- FY27 AISC guidance maintained at A$2,800–3,100/oz.
The key issue was the contractor transition in August, which disrupted mining rates and pushed some production into later quarters. Management expects the impact to be largely confined to 1Q, with deferred ounces recovered through the remainder of FY27 as the new contractor adds workers and productivity improves.
For us, this is a disappointing quarter rather than a thesis-changing one. Grades remain consistent with the mine plan, liquidity improved slightly, and full-year guidance has been maintained. However, BGL now needs to show a meaningful lift in production through the December quarter to rebuild confidence around execution.
We continue to own BGL with the attraction remaining the prospect of higher, more consistent production alongside progressively greater exposure to spot gold as the hedge book rolls off, but after another operational hiccup, execution remains the key swing factor.
MM remains long & bullish BGL ~$1.40
Add To Hit List