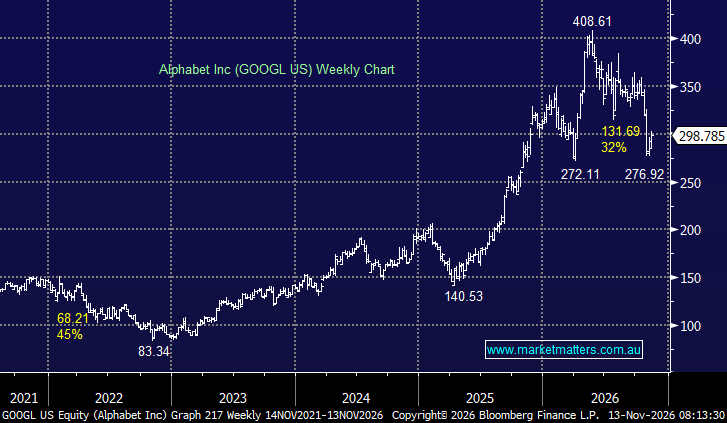
Alphabet Inc. is potentially one of the better-positioned beneficiaries to benefit if NVIDIA were to lose momentum, given Google’s investment in its own Tensor Processing Units (TPUs), custom-designed AI chips that provide an alternative to NVIDIA’s GPUs. Through Google Cloud, Alphabet can offer customers access to its own AI infrastructure, with a reported 44% total cost of ownership advantage and a $561bn cloud backlog providing substantial growth visibility. This creates an opportunity to win customers looking to reduce their dependence on NVIDIA, while improving the economics of its own Gemini AI models and broader services.
- GOOGL advanced ~2% overnight as events unfolded at NVIDIA.
However, the opportunity has limitations. NVIDIA’s software ecosystem is better and more, and Google Cloud still relies on NVIDIA GPUs for a meaningful share of workloads. More importantly, the greatest risk to Alphabet is not NVIDIA losing market share, but a broader slowdown in AI infrastructure investment. Alphabet is committing enormous amounts of capital to data centres, chips and computing capacity, and weaker demand could simultaneously slow Google Cloud growth, reduce returns on investment and leave the company carrying significant infrastructure costs.
A similar story to AVGO, a shift away from NVIDIA could benefit Alphabet, but a broader cooling of the AI investment cycle would be the more significant headwind. Also, we are conscious that Alphabet’s 3Q trading update was taken poorly by the market, covered here, with their traditional search business underwhelming.
- We can see GOOGL retesting the US$350 level if the AI Trade continues to regain its mojo.