- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
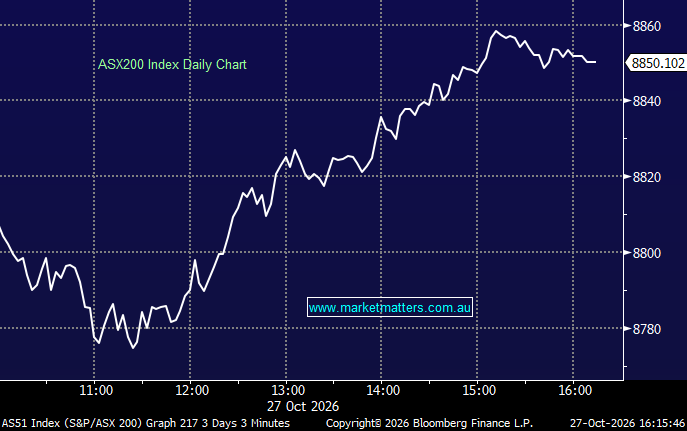
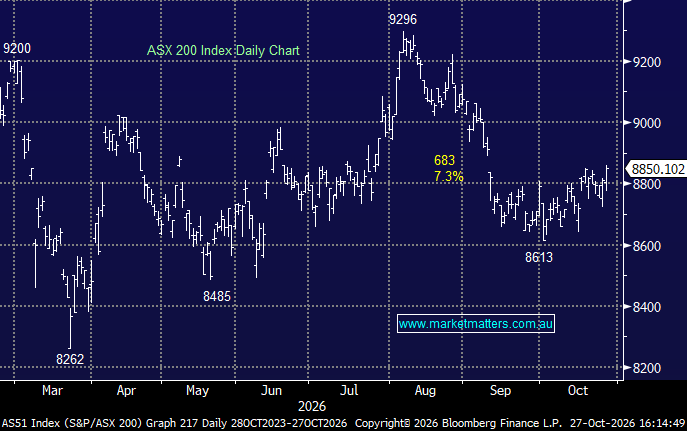
The ASX recovered from an early decline as Anthropic’s IPO filing revived global appetite for AI-related stocks just as stronger-than-expected Chinese economic data helped light a fuse under the Materials sector. The resources recovery was broad-based across gold, lithium, uranium and rare earths. However, it was strength in copper names that really gave the market a boost, with The Big Australian (BHP) adding +35pts to the index move by itself, helping to offset weakness in banks and defensive sectors.
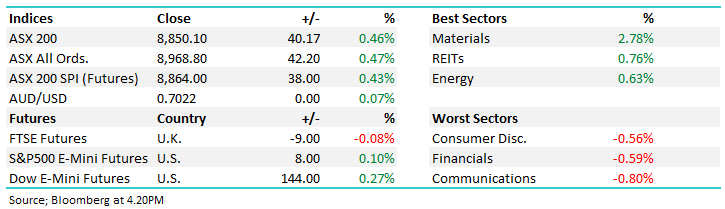
- ASX 200: 8,850.10, +40.20 points, +0.46%.
- AUD/USD: 0.7019, +0.01%.
- Best Sectors: Materials +2.78%, REITs +0.76%, Energy +0.63%.
- Worst Sectors: Communication Services -0.80%, Financials -0.59%, Consumer Discretionary -0.56%
- Westpac Consumer confidence remained weak at 67.9, while weekly inflation expectations rose to 6.3%, adding to the focus on Wednesday’s September-quarter CPI release.
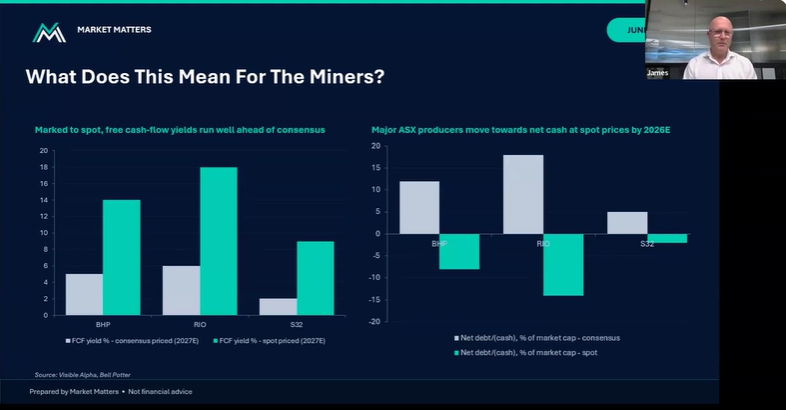
- Miners extended their rebound, with the Materials sector up almost 4% higher across two sessions. The bounce spanned copper, gold, lithium, uranium and rare earths, though iron ore remained under pressure amid weaker demand expectations and rising supply.
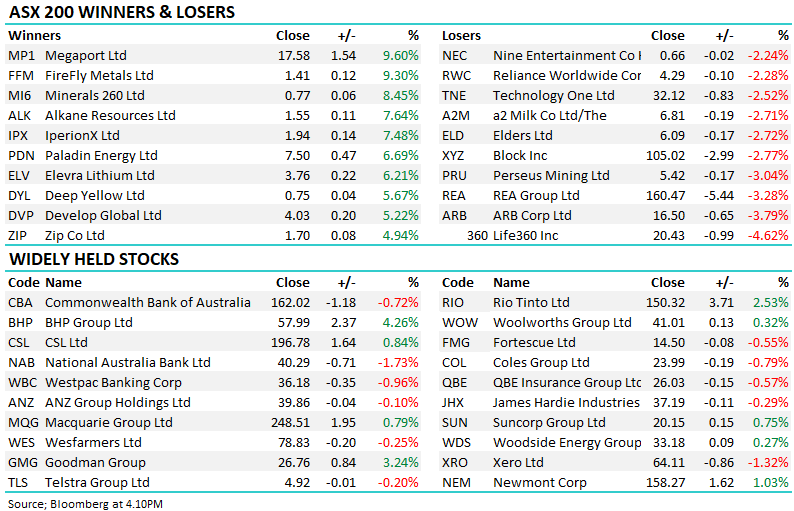
- BHP Group (ASX: BHP) +4.26% to $57.99 and Rio Tinto (ASX: RIO) +2.53% to $150.32 rose with the broader mining recovery. South32 (ASX: S32) +2.58% to $4.37 and Lynas Rare Earths (ASX: LYC) +3.46% to $11.66 also advanced. BHP held in Active Growth & Income Portfolios. RIO & S32 held in the Active Growth Portfolio.
- Anthropic’s public IPO filing helped revive risk appetite for Technology and Software stocks – Megaport (ASX: MP1) +9.60% to $17.58 and NEXTDC (ASX: NXT) +3.79% to $5.75 rallied with other AI and data-centre exposed shares. Zip Co (ASX: ZIP) +4.94% to $1.70 continued its recovery after last week’s selloff. ZIP held in the Emerging Companies Portfolio.
- The major banks weighed on the market, with all four closing lower ahead of this week’s inflation data and next week’s RBA decision. National Australia Bank (ASX: NAB) -1.73% to $40.29, Westpac (ASX: WBC) -0.96% to $36.18, Commonwealth Bank of Australia (ASX: CBA) -0.72% to $162.02 and ANZ Group Holdings (ASX: ANZ) -0.10% to $39.86 declined. ANZ & WBC held in Active Growth & Income Portfolios.
- Woodside Energy Group (ASX: WDS) +0.27% to $33.18 agreed to sell its 33.44% stake in the Greater Sunrise project to Timor GAP for up to $200 million. The sale, subject to approvals, is targeted for completion in the first half of 2027 and will allow Woodside to redirect capital and management attention to other opportunities.
- The Star Entertainment Group (ASX: SGR) +13.04% to 13c reported a return to positive quarterly EBITDA, at $12 million compared with a $13 million loss a year earlier, as Sydney and Gold Coast revenue improved and expenses declined. The company still faces going-concern uncertainty, including the suspended Star Sydney licence.
- CSL (ASX: CSL) +0.84% to $196.78 reaffirmed its FY27 outlook for underlying profit growth of about 5%; interim CEO Gordon Naylor is set to replace Brian McNamee as chairman in March.
- Perseus Mining (ASX: PRU) -3.04% to $5.42 fell after its September-quarter production and costs missed estimates, although the company maintained full-year guidance.
- Gold: Traded down -0.2% to $US4,009/oz
- Iron Ore: US$89.40/mt / -1.2%
- Brent crude: Traded near US$114.80/bbl / -0.8%
- Futures: S&P 500 E-mini futures +8.00pts / +0.10% | Dow Jones E-mini futures +144.00pts / +0.27% | FTSE futures -9.00pts / -0.08%.
- US Earnings Tonight: Visa (NYSE: V), Coca-Cola Company (NYSE: KO), Freeport McMoRan (NYSE: FCX) & HCA Healthcare (NYSE: HCA).