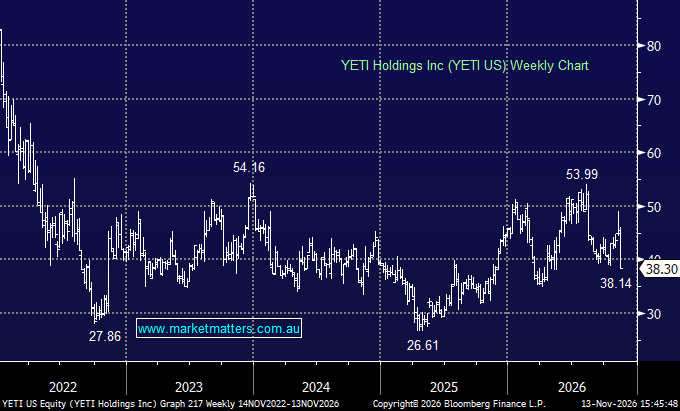
YETI delivered a mixed third-quarter result, with earnings comfortably ahead of expectations, although revenue missed consensus and management lowered the full-year outlook. As we’ve seen time and time again, the market has no hesitation in punishing any downward revisions to earnings outlooks, and we saw this with YETI overnight.
Key details:
- Q3 reported sales increased 4% to US$509.4m, missing the US$523.6m consensus estimate.
- Adjusted EPS rose 49% to US$0.91, ahead of the US$0.85 market estimate.
- Adjusted gross margin expanded 310 basis points to 59%
- Drinkware sales grew 8%, while international sales increased 19%.
- FY26 adjusted sales growth guidance was reduced to approximately 6%, from 7–8% previously, below market expectations.
- Adjusted EPS guidance was trimmed to US$2.90–US$2.95, from US$2.94–US$3.00, the midpoint below consensus of ~US$2.97.
MM’s view: YETI’s brand strength and operating discipline position it well to navigate a softer consumer environment. However, near-term demand remains a risk, particularly in North America. Its position as a premium brand, at the upper end of discretionary spending, makes it particularly sensitive to changes in consumer confidence and interest rates. With US rates now expected to remain higher for longer, we see the consumer environment staying challenging, with discretionary stocks likely to remain under pressure. Against this backdrop, we are growing more cautious towards YETI.
MM is neutral towards YETI
Add To Hit List