Hi Peter,
Champion Iron (ASX: CIA) posted a weak 2Q result this week covered by MM here, the company is suffering from the painful 1-2 combination of pressure on margins courtesy of weaker pricing and higher costs.
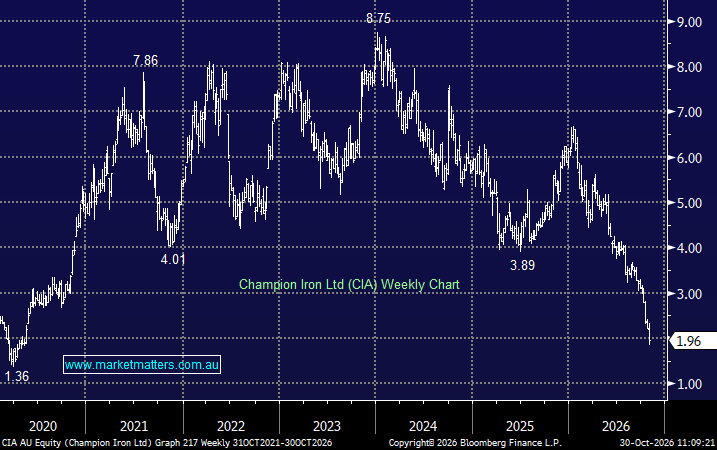
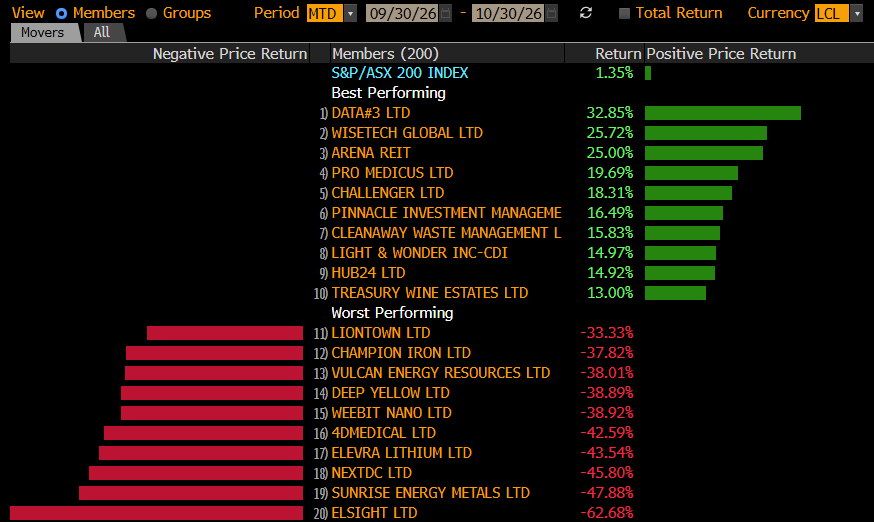
CIA has been one of the ASX’s worst-performing miners in 2026, with shares falling ~70% from their January peak as collapsing margins and mounting balance sheet concerns weigh on sentiment. Weaker iron ore prices, elevated freight and fuel costs, and expenses associated with commissioning its new direct reduction pellet feed (DRPF) project have combined to squeeze profitability.
- Importantly, the company has now reported consecutive quarterly losses despite record September-quarter iron ore sales volumes, highlighting the severity of the margin pressure.
The bigger concern for us is CIA’s financial position, with net debt of C$913m. They do have another C$618m in available liquidity, but they’ve had to renegotiate temporary relief from certain lending covenants through mid-2027.
On a more positive note, Champion has completed its first commercial shipment of higher-value DRPF iron ore, with further shipments planned, potentially supporting margins as production ramps up.
While Champion retains valuable iron ore assets and sufficient liquidity to navigate the immediate challenges, the combination of weak profitability, elevated debt and uncertain commodity prices makes the stock uninvestable to us.
We are neutral towards CIA below $2.