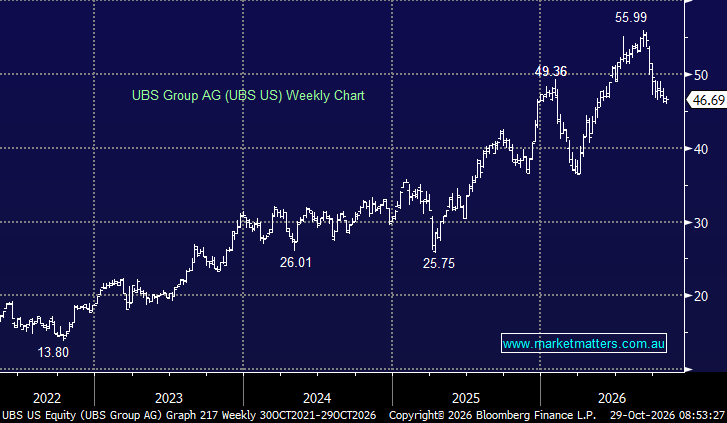
UBS Group (UBS) delivered a broadly solid third-quarter result, with strong wealth-management inflows the standout. The stock was essentially flat in US trading post-result, reflecting a decent print but little in the way of a fresh catalyst.
Key Q3 highlights:
- Net income: US$2.69bn, up 8.4% YoY vs US$2.74bn expected.
- Revenue: US$13.35bn, up 4.6% YoY vs US$13.06bn expected.
- Wealth Management pretax profit: US$1.92bn, up 42% YoY.
- Global Wealth net new assets: US$55.1bn vs US$34.9bn expected.
- CET1: 14.7%.
- UBS repurchased US$1.8bn of shares during the quarter.
The key positive was wealth, particularly strong net new money across Asia Pacific and the Americas. The Credit Suisse integration also remains on track to be completed by year-end, while the balance sheet remains healthy. The lingering issue is capital returns. Management flagged seasonal moderation into Q4 and declined to provide further detail on the scale of its next buyback program.
MM’s view: We own UBS and remain positive. The core wealth-management franchise continues to perform well, and the Credit Suisse integration is nearing completion. The next major catalyst is likely to come from greater clarity on capital requirements for the now merged group, which will have implications for balance sheet flexibility moving forward. The first cut of this from the Swiss Regulator was sub-optimal.