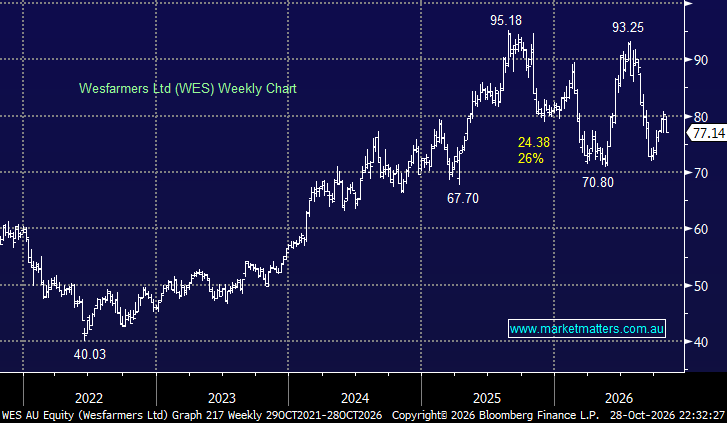
After mentioning Woollies and mince this morning we’ve revisited WES, far from a direct rival but still a discretionary retailer with brands such as Bunnings, Kmart and Officeworks. We last looked at WES following its solid FY26 result here, in August, when the stock was ~$80. After dropping $3, it’s on our radar in line with our comments back then: “The dividend increase is welcome, and the core franchises remain first class, but we’d want either a better entry point or a stronger earnings acceleration before becoming more enthusiastic.”
WES has risen almost 2% in October, although the modest gain masks a choppy month, supported by an upgrade from Barrenjoey to Overweight with an $89 price target and a general defensive bid. Wesfarmers Health also attracted attention, with demand for weight-loss treatments and beauty services supporting growth across Priceline and its laser-clinic businesses. However, not surprisingly, concerns about pressure on consumer spending have been a headwind, with investors watching for further guidance at today’s AGM – 4pm AEST.
- We can still see WES testing the $70 area, but it is slowly becoming more attractive – we will reassess after the AGM.
MM is neutral towards WES around $77
Add To Hit List