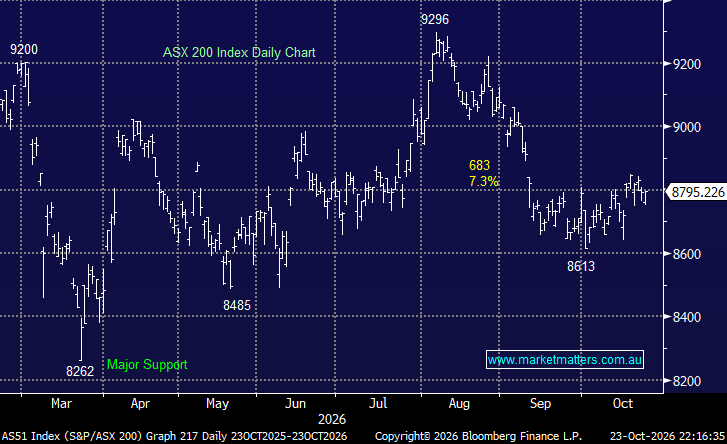
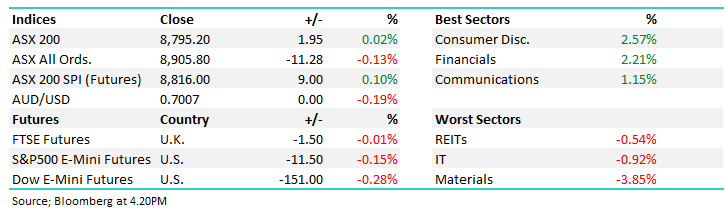
The ASX 200 finished a volatile week, especially at the stock and sector level, with an 8% drop in the materials sector dragging down the broader market by just 0.1% despite almost 60% of the main boards closing higher. However, when we see heavyweight miners South32 (-11%), Sandfire (-10%), BHP Group (-8%), and RIO Tinto (-6%), it was always going to be tough for the index to advance.
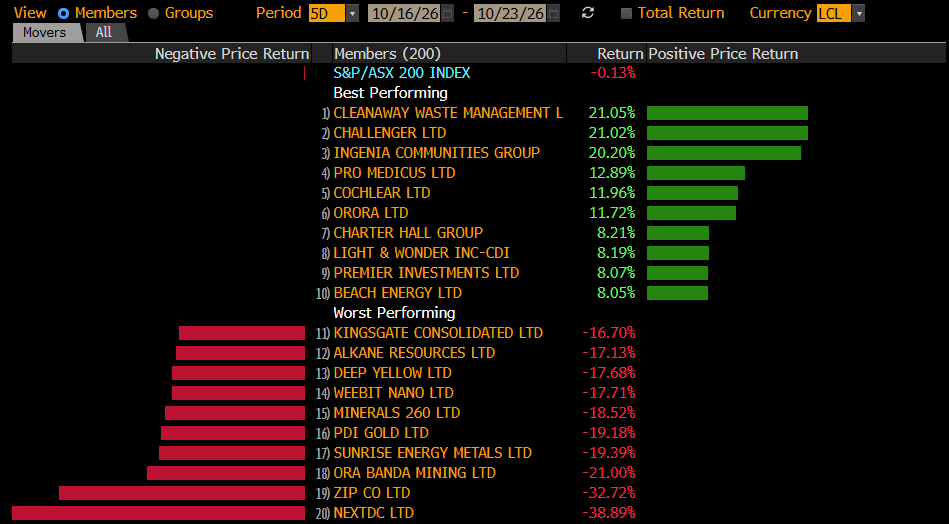
The best and worst-performing stocks last week showcased dramatic moves driven by M&A and disappointing trading updates, plus a sprinkling of gold stocks on the wrong side of the ledger – it’s not often that stocks which fall 10% don’t get close to figuring in the losers enclosure.
Winners: Cleanaway Waste (ASX: CWY) +21.1%, Challenger (ASX: CGF) +21%, Ingenia Communities (ASX: INA) +20.2%, Pro Medicus (ASX: PME) +12.9%, Cochlear (ASX: COH) +12%, Orora (ASX: ORA) +11.7%, Charter Hall (ASX: CHC) +8.2%, and Light & Wonder (ASX: LNW) +8.2%.
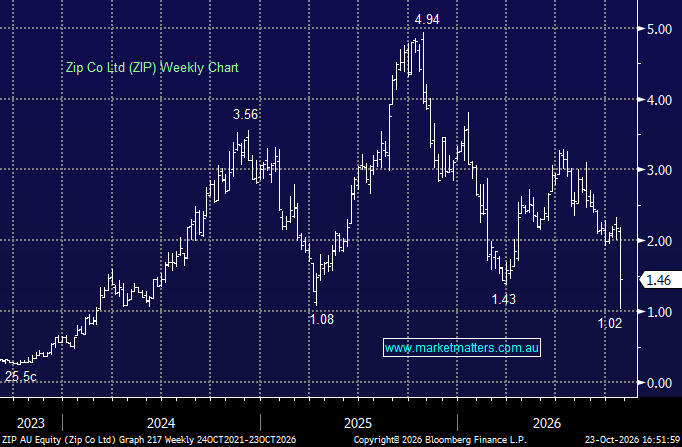
Losers: NEXTDC (ASX: NXT) -38.9%, ZIP Co Ltd (ASX: ZIP) -32,7%, Ora Band Mining (ASX: OBM) -21%, Sunrise Energy (ASX: SRL) -19.4%, PDI Gold Ltd (ASX: PDI) -19.2%, Minerals 260 Ltd (ASX: MI6) -18.5%, Weebit Nano (ASX: WBT) – 17.7%, and Deep Yellow (ASX: DYL) -17.7%.
Weekly snapshot: Major news during the week was largely stock and sector specific.
- The ASX 200 commenced the week with bullish M&A news for Cleanaway (CWY) and Challenger (CGF) helping lift the index +0.45%.
- BHP set the tone on Tuesday, delivering a soft quarter for copper, with production down~19%, pushing the stock down 1.6%, the calm before the storm!
- NEXTDC dominated the news on Wednesday, crashing ~40% after succumbing to resident pressure at its M3 Melbourne data centre.
- Sentiment was dented further by RBA deputy governor Andrew Hauser, who warned inflation was materially worse than forecast in August.
- Thursday saw Nick Scali (-15%) close down after a weaker 1H26 result demonstrating how tough it is in retail, particularly those influenced by weakness in property markets.
- The week ended with aggressive rotation into the Big Four banks at the expense of the major miners, e.g. CBA (+4%) and BHP Group (-4%), and a ~50% plunge by ZIP on the open after a fraud incident contributed to a September-quarter earnings miss.
Next week, mega-cap technology companies will step up to the plate, with Amazon, Alphabet and Microsoft reporting amid heightened scrutiny of AI capacity constraints, data-centre demand and returns on heavy capital spending. On the macroeconomic front, US GDP and PCE inflation data will be key releases, while oil prices will continue to exert a major influence on stocks.
Overseas markets struggled overnight as oil punched higher as a further flare-up in the Middle East threatened global oil supplies. In Europe, the UK FTSE and EURO STOXX 50 both retreated by 0.3%. In the US, the Dow fell 1.2% as selling spread from the semiconductors, with the S&P 500 closing down 0.5%.
- The SPI Futures are calling the ASX 200 to open down 0.5% on Monday following a tough session on global bourses as the oil price surged more than 3%.