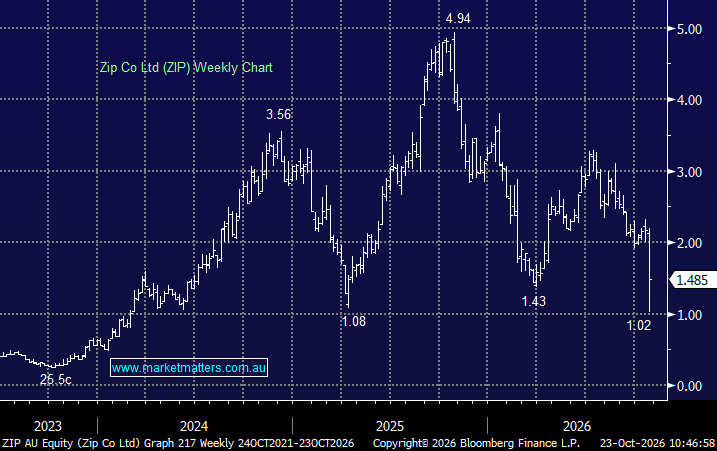
Why did ZIP Co Ltd (ASX: ZIP) crash 50% on the open?
Zip Co (ASX: ZIP) has been smashed today, plunging as much as 50% after revealing a US fraud incident that cost the buy-now-pay-later provider $7.2m and disrupted customer growth and transaction volumes during July and August. The company has notified authorities and lodged an insurance claim, but the bigger concern for investors is the deterioration in credit quality.
- Group net bad debts rose to 1.97% of transaction volumes, compared with 1.65% a year earlier. The combination of unexpected fraud costs, higher credit losses and weaker US momentum has clearly rattled investors, triggering the stock’s largest-ever one-day decline.
Importantly, the underlying quarterly numbers weren’t all bad. Revenue rose 17% to $373.4m, total transaction volumes increased 18% to $4.6bn, and merchant numbers climbed 10% to 96,600. However, cash earnings (EBTA) grew just 3.5% to $65m, well below revenue growth, while active customers remained flat at 6.4 million.
Management has maintained FY27 cash EBTA guidance of $340m, comfortably ahead of consensus expectations of ~$300m, and expects US credit losses to improve in the December quarter, reiterating its FY27 target range of 1.5–2.0% of transaction volumes.
We believe the scale of today’s selloff looks extreme given Zip has maintained full-year earnings guidance, but questions are arising around the quality and sustainability of its growth. The fraud incident may prove temporary, but rising bad debts and relatively modest earnings growth suggest the business has less room for error than investors previously assumed.
- We like ZIP into the panic selling below $1.50 but it’s not for the faint hearted.