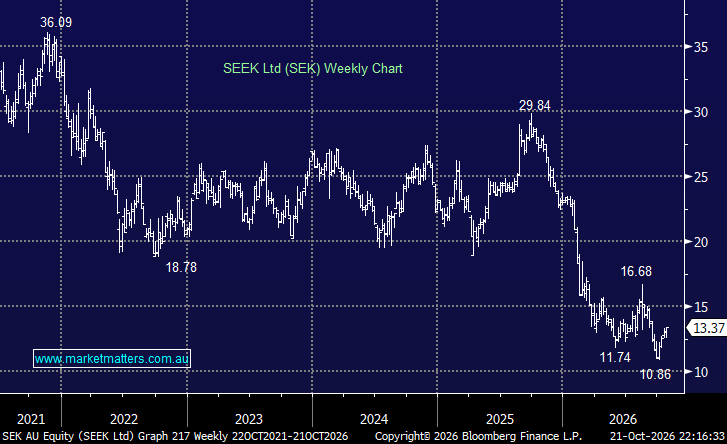
SEEK Ltd (SEK) rose +4.4% on Wednesday but its been on a downward spiral since 2021, not just over the last 12-months like CAR and REA. Again, the weakness reflects the confluence of three compounding headwinds: AI disruption fears that de-rated the stock more severely than its ASX peers, a multi-year structural decline in Australian job ad volumes that raised questions about the durability of the business model, and Asia volume deceleration which removed a key growth driver.
- These major structural headwinds led to SEK trading more than 40% below its medium-term EV/EBITDA multiple.
The partial stabilisation from August 2026 has been driven by a yield growth upgrade to a minimum of 10% and early evidence that AI-powered products like Advanced Ads are accelerating monetisation even as volumes remain weak. Looking to 2030, the growth case rests on yield compounding at double-digit rates, EBITDA margin expansion of ~1.3pp per annum, Growth Fund asset monetisation, and a gradual Asia volume recovery, with international revenue holding steady at ~20%.
NB “Yield growth” means earning more revenue from each customer, listing or transaction, rather than relying on an increase in the number of customers or listings.
SEEK’s Growth Fund holds minority stakes in online employment marketplaces across emerging markets, including Latin America, Asia and Africa. These investments sit outside SEEK’s core operating businesses and provide exposure to faster-growing job markets, where SEK has invested in businesses without owning or managing them outright. They are reportedly exploring the sale of around $1 billion of Growth Fund assets, potentially unlocking capital that could be returned to shareholders or reinvested in the business. The question is how much cash SEEK can ultimately realise from the sale and how it chooses to use the proceeds, e.g. buybacks, dividends, expansion, etc.
- We like the risk/reward towards SEK at current levels, targeting the $16 area, or 15-20% higher.
MM is cautiously bullish towards SEK
Add To Hit List