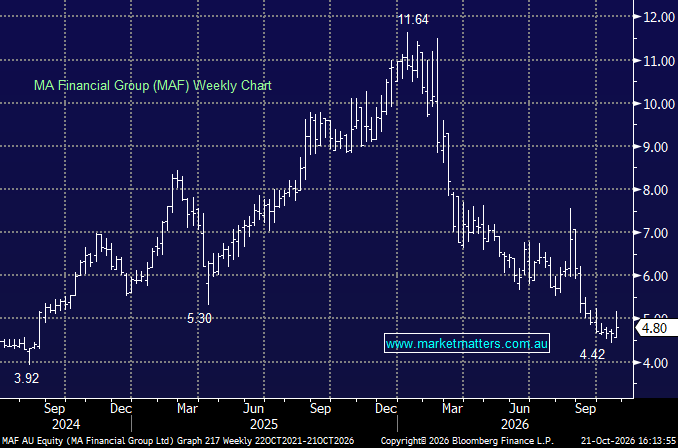
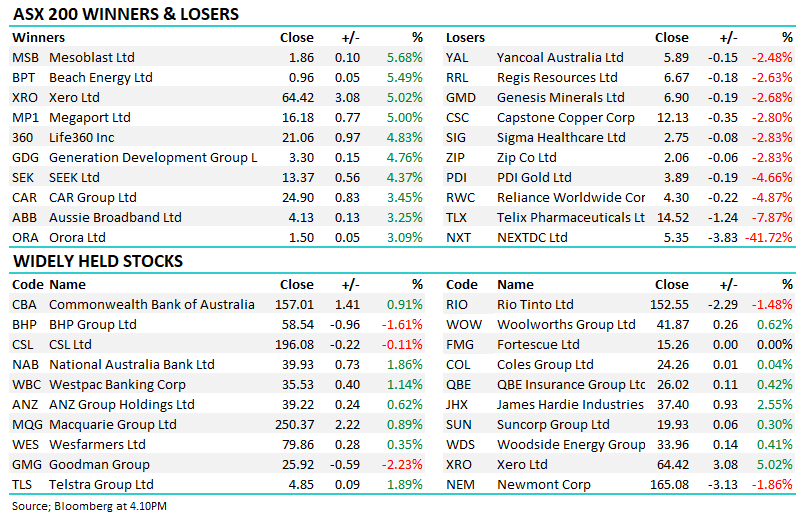
MAF +3%: Rallied around 9% early, with the market initially responding positively to a broader trading update showing continued growth in the business. That said, the update also reinforced why the stock has been under so much pressure, with MA suspending redemptions across its property-related lending funds and winding up its MA Secured Real Estate Income Fund as conditions in property and private credit remain difficult.
Key points:
- AUM: A$15.7bn, up 18% YoY.
- Gross inflows: A$710m, up 11%
- MA has suspended redemptions across its A$2.3bn property lending strategy.
- The MA Secured Real Estate Income Fund will be wound up, with capital expected to be returned over around 12 months.
- Private credit AUM is around A$7.5bn, with property still a significant part of the book.
Redemption restrictions across private credit are never a good look, particularly when they coincide with weaker property conditions, slower asset sales and longer refinancing timeframes. It raises questions around liquidity, valuation and the broader mismatch between relatively illiquid loans and investor redemption expectations.
However, we do think MA is a better operator than the share price currently implies. The business is diversified across asset management, lending and corporate advisory, and while property is still dominant within private credit, this is not a one-dimensional residential development lender. The 18% growth in AUM and resilient gross inflows also suggest the broader franchise is holding up well despite the difficult backdrop.
We own MAF and think the selloff has gone too far. MA is a diversified and capable operator coming off a very low base.
MM remains positive on MAF
Add To Hit List