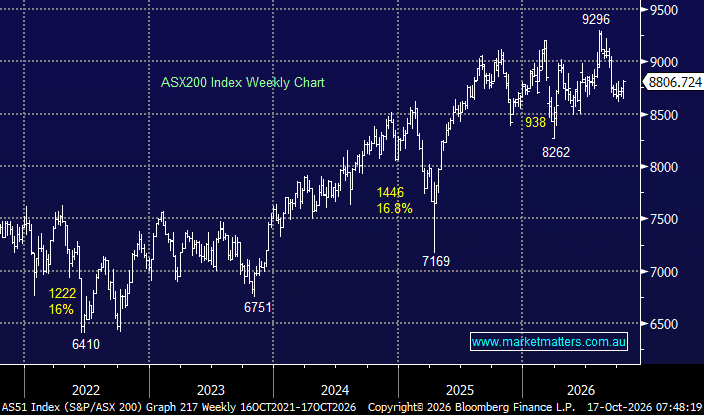
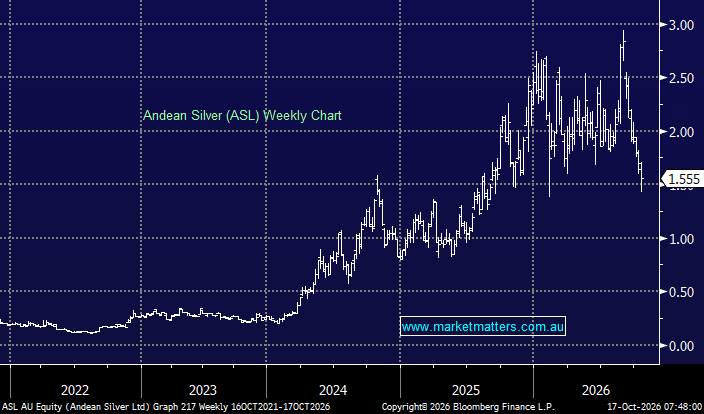
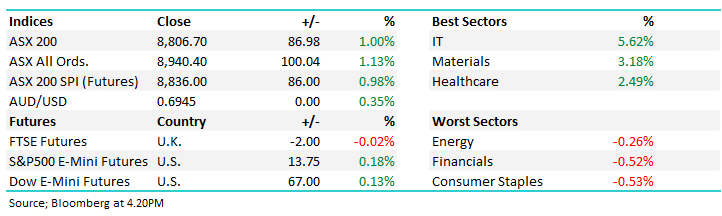
The ASX 200 finished a volatile week up +1.0%, although the headline gain masked some fairly aggressive rotation beneath the surface. Utilities (+4.5%), Healthcare (+3.9%), Consumer Staples (+3.4%) and Financials (+3.2%) led the market higher, while Materials (-2.3%), Real Estate (-1.7%) and Information Technology (-1.3%) lagged. Investors continued to rotate into some of the more beaten-up and defensive areas of the market, while resources came under pressure.
The stock moves were equally stark, with some sharp rebounds in names that had been heavily sold in recent weeks, while lithium, uranium and AI linked tech featured prominently on the losers’ side.
Winners: WiseTech Global (ASX: WTC) +11.8%, Bank of Queensland (ASX: BOQ) +7.9%, Treasury Wine Estates (ASX: TWE) +7.7%, BlueScope Steel (ASX: BSL) +7.5%, Generation Development Group (ASX: GDG) +7.2%, Lovisa (ASX: LOV) +7.1%, Block (ASX: XYZ) +6.9%, Origin Energy (ASX: ORG) +6.1%, Pro Medicus (ASX: PME) +6.0%, & Sigma Healthcare (ASX: SIG) +6.0%.
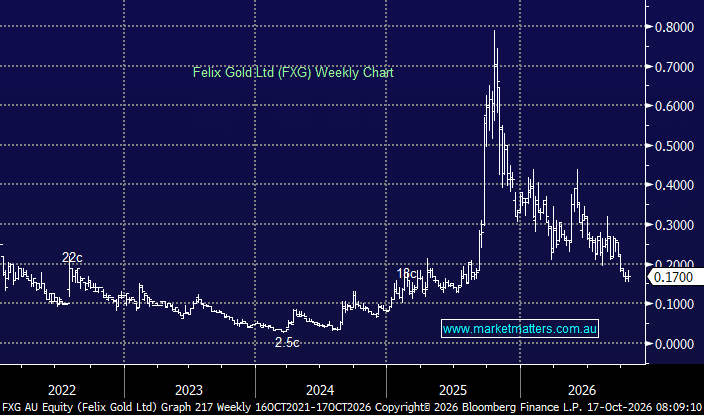
Losers: Elsight (ASX: ELS) -18.4%, Vulcan Energy (ASX: VUL) -17.3%, Ingenia Communities (ASX: INA) -16.8%, Deep Yellow (ASX: DYL) -16.3%, Elevra Lithium (ASX: ELV) -16.3%, Champion Iron (ASX: CIA) -15.0%, PLS Group (ASX: PLS) -14.9%, Paladin Energy (ASX: PDN) -12.8%, Megaport (ASX: MP1) -12.1%, & NEXTDC (ASX: NXT) -11.5%.
Weekly snapshot: The ASX finished higher, but it was a week of major macro cross-currents and aggressive sector rotation:
- The week started positively, with banks and miners leading a rebound as Australian bond yields eased and commodity prices firmed. Technology also recovered, although the broader market remained selective rather than universally strong.
- Midweek, hotter-than-expected US CPI rattled global markets. September headline inflation rose 0.6% for the month and 3.7% year-on-year, up from 3.4% in August, while core CPI rose 0.3% and 2.6% annually. The result revived expectations of another Fed hike and briefly pushed the US 10-year yield above 5.3%, placing renewed pressure on expensive growth and AI-linked equities.
- The pressure was most obvious in semiconductors. The Philadelphia Semiconductor Index was down on every session as the market questioned the sustainability of AI capital spending and, importantly, the debt being used to fund parts of the data-centre buildout. CoreWeave’s bonds were a focal point, with yields pushing above 15%.
- Thursday was the weakest local session, with resources under pressure. Iron ore, lithium and uranium names were sold heavily, while the banks also fell.
- Australian employment data provided some relief on Thursday. September employment fell by 39,300, while the unemployment rate printed at 4.7% and participation eased to 66.8%. The softer labour market helped bring down expectations for aggressive RBA tightening and gave rate-sensitive sectors some support.
- Friday saw the local market bounce strongly as the rally broadened into areas that had been heavily sold. Technology and Materials led the recovery, with investors stepping back into oversold names. That broadening is constructive in our view — a healthier market is one where leadership extends beyond a narrow handful of winners.
The key battle remains earnings growth versus higher bond yields. US 10-year yields finished the week around 5.1%, having traded above 5.3% after the CPI print. Encouragingly, bond markets began to behave more like a traditional safe haven later in the week, with yields easing as AI-related equities came under pressure. That is a subtle but important shift after a period where both stocks and bonds had been falling together.
In the coming week, the focus moves firmly back to US earnings, particularly the AI complex. Meta, Tesla, Lam Research and Texas Instruments are all due to report. Consensus still expects S&P 500 earnings growth of ~30% for the September quarter, which remains the key fundamental support for the market.
Overseas markets finished the week on a softer note as technology selling intensified on Friday. The S&P 500 fell 1.1%, the NASDAQ dropped 2.2%, while the Dow was comparatively resilient, falling just 0.4% as money continued to rotate away from AI and into more traditional sectors. Brent crude also surged toward US$110/bbl amid renewed Middle East supply concerns, keeping inflation and interest rates front and centre heading into next week.
- SPI Futures are pricing a slight dip on Monday, down -11pts/0.12%, comparatively better than Wall Street – early signs of looming ASX outperformance perhaps.