- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
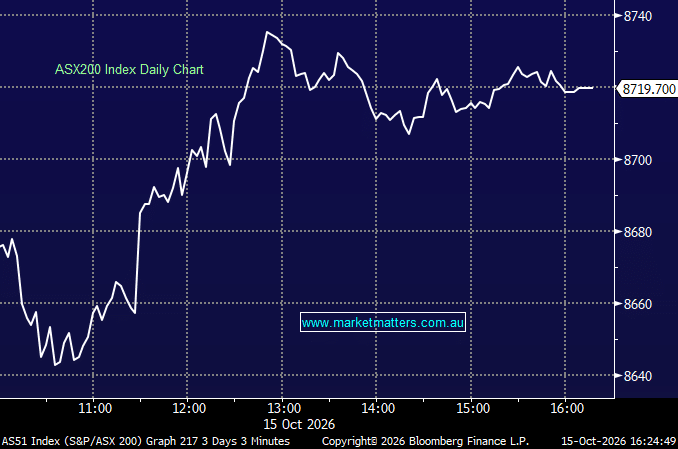
Local shares finished marginally lower as a defensive rotation into consumer staples and financials offset a sharp sell-off in miners, technology and data centre stocks, with softer domestic employment data providing some relief on interest rate expectations after hotter-than-expected US inflation reignited rate concerns overnight.
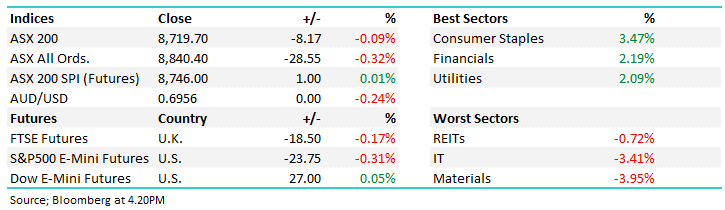
- ASX 200: 8,719.69, -8.16pts, -0.09%.
- AUD/USD: 0.6956, -0.24%.
- Best Sectors: Consumer Staples +3.47%, Financials +2.19%, Utilities +2.09%.
- Worst Sectors: Materials -3.95%, Information Technology -3.41%, REITs -0.72%.
- Australian employment data at 11:30am for September showed employment fell by 39,300, against expectations for a 20,000 increase, and unemployment rose to 4.7% vs 4.6% expected. The data eased immediate rate hike concerns, although elevated inflation leaves the RBA’s November decision uncertain with markets pricing in a ~0.2% chance of a hike vs ~0.3% prior to the data.
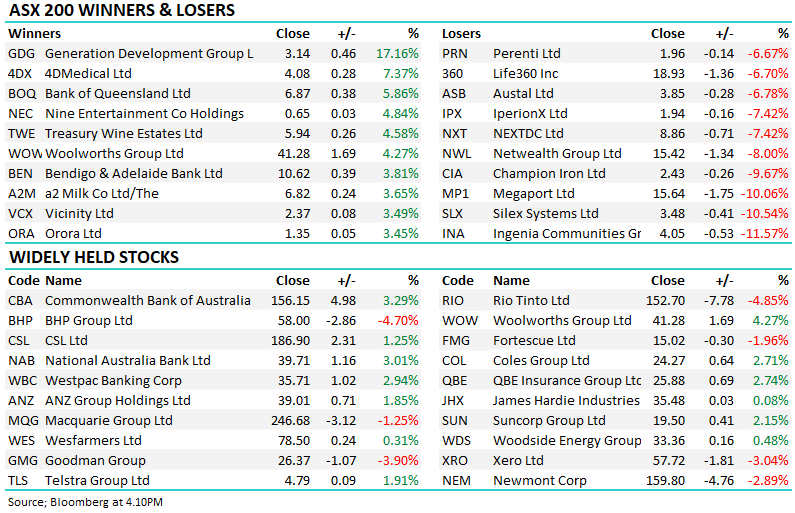
- Financials rallied on the back of the employment data with Commonwealth Bank of Australia (ASX: CBA) +3.29% to $156.15, National Australia Bank (ASX: NAB) +3.01% to $39.71, Westpac Banking Corporation (ASX: WBC) +2.94% to $35.71 and ANZ Group Holdings (ASX: ANZ) +1.85% to $39.01 all advancing. ANZ & WBC held in the Active Growth and Income Portfolios.
- Bank of Queensland (ASX: BOQ) +5.86% to $6.87 rallied despite FY26 cash profit falling 7% to $358 million, with the market zeroing in on net interest margin improving to 1.70%, above consensus of 1.69%.
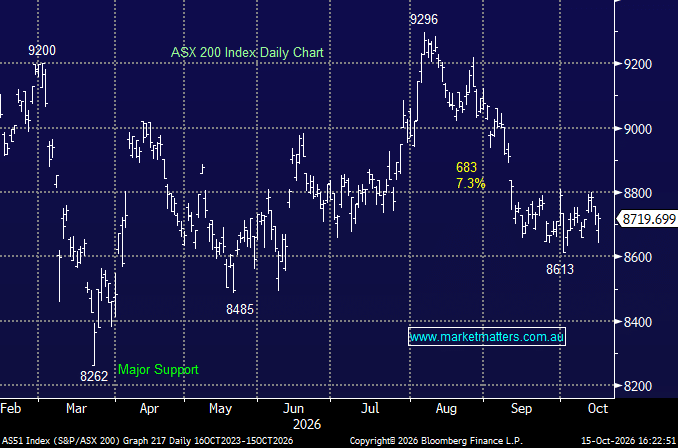
- Materials slumped to a three-month low as global risk aversion, weaker commodity prices and concerns about AI infrastructure spending weighed on miners. BHP Group (ASX: BHP) -4.70% to $58.00 and Rio Tinto (ASX: RIO) -4.85% to $152.70 led the major miners lower, while Fortescue (ASX: FMG) -1.96% to $15.48 also declined. BHP held in the Active Growth and Income Portfolios. FMG held in the Active Income portfolio.
- Chinese lithium futures extended weakness amid concerns about electric vehicle and energy-storage demand, now down 14% over the week. Goldman Sachs expects the market to move towards balance in the fourth quarter, followed by surpluses over the next two years.
- Off the back of the weakness, Morgans upgraded Mineral Resources (ASX: MIN) -4.85% to $44.38 to Buy from Accumulate but cut its target to $65 from $71, while upgrading PLS Group (ASX: PLS) -6.31% to $2.97 to Accumulate from Trim and reducing its target to $4 from $4.60. Liontown Resources (ASX: LTR) -5.56% to 68c remained under pressure, with Morgans retaining its Accumulate rating but cutting its target to 85 cents from $1.10.
- Tech fell as hotter US inflation, rising rate expectations and concerns over AI valuations and infrastructure funding triggered a global technology sell-off. Megaport (ASX: MP1) -10.06% to $15.64, NextDC (ASX: NXT) -7.42% to $8.86, Life360 (ASX: 360) -6.70% to $18.93 and Xero (ASX: XRO) -3.04% to $57.72 declined sharply. XRO held in the Active Growth Portfolio. 360 held in the Emerging Companies Portfolio.
- Consumer Staples led the market as investors rotated towards defensive earnings. Woolworths Group (ASX: WOW) +4.27% to $41.28 and Treasury Wine Estates (ASX: TWE) +4.58% to $5.94 advanced strongly, while Wesfarmers (ASX: WES) +0.31% to $78.50 edged higher.
- WiseTech Global (ASX: WTC) +2.83% to $34.50 benefited from ASIC closing investigations into the company, founder Richard White and two other employees, issuing no-action letters which removes a significant regulatory overhang. WTC held in the Active Growth Portfolio.
- ARB Corporation (ASX: ARB) -3.27% to $16.56 held their AGM announcing a 6.1% decline in first-quarter sales as vehicle recalls, a HiLux stop-sale, UK supply issues and softer New Zealand demand weighed on aftermarket and export sales. OEM sales grew strongly, and unaudited profit before tax increased despite lower sales. ARB held in the Emerging Companies Portfolio.
- Netwealth Group (ASX: NWL) -8.00% to $14.42 fell after cutting FY27 funds-under-advice net flow guidance by approximately 5.2% to $17–19 billion from $18–20 billion, despite record funds under administration of $139.2 billion.
- SHAPE Australia (ASX: SHA) -6.26% to $6.89 fell in line with the AI-related selloff, despite securing an ~$800 million contract to expand DigiCo’s Sydney data centre campus by 52MW, lifting work in hand above $1.4 billion.
- Gold: Traded near US$4,151/oz / +1.1%.
- Iron Ore: US$90.50/mt / +0.1%.
- Brent crude: Traded near US$104.60/bbl / -0.3%.
- Futures: S&P 500 E-mini futures -23.75pts / -0.31% | Dow Jones futures +27.00pts / +0.05% | FTSE futures -18.50pts / -0.17%.
- US Reporting Tonight: Taiwan Semiconductor (NYSE: TSM) the main one to watch.