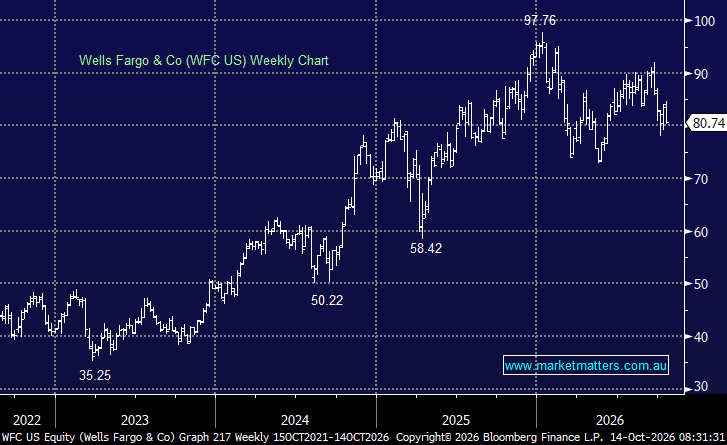
Wells Fargo’s quarter was pretty steady. Revenue and NII were slightly soft, but credit quality came in better than expected and profitability continued to improve following removal of the Fed’s long-standing asset cap.
3Q highlights;
- Revenue: US$21.87bn, up 2% YoY, missing consensus of US$22.31bn by 2%.
- EPS: US$1.87, up 13% YoY, beating consensus of US$1.85 by 1%.
- Net profit: US$5.95bn, beating consensus of US$5.87 bn by 1.4%.
- Equities trading revenue: US$543m, flat YoY.
- FICC trading: US$1.26bn, down 7% YoY.
- Investment banking fees: US$908m, up 10% YoY.
The most encouraging aspect was credit. Management said consumers and businesses remain in good shape, with low delinquencies and limited signs of broader stress. Cost control was also solid, helped by an 8% reduction in headcount, while the bank reaffirmed its FY26 NII guidance of around US$50bn.
Wells Fargo is now operating without the balance-sheet restrictions that constrained growth for years, which should provide a longer-term tailwind. The quarter itself was fairly benign, but improving returns, resilient credit and scope to grow the balance sheet make the medium-term setup increasingly interesting. JPM is trading on 10.2x vs historical average of 10.9x. The stock ended lower overnight.
MM is neutral WFC ~$US80
Add To Hit List