- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
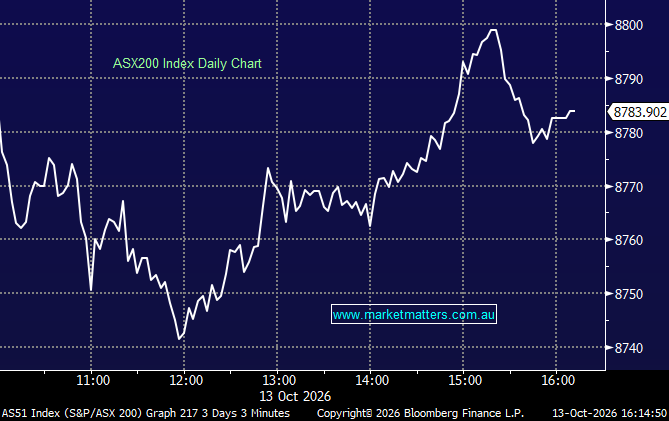
A mixed session on the ASX today, with the index recovering from intraday losses to finish almost unchanged. Defensive sectors, energy and banks provided some support, but a sharp global semiconductor sell-off weighed heavily on Technology, while Materials and lithium stocks also came under pressure. Concerns around Chinese competition in memory chips and the sustainability of AI infrastructure spending drove a broader pullback in growth stocks though rising oil prices added to the inflation outlook, with the latest RBA minutes reinforcing concerns about domestic capacity pressures and the possibility of further rate hikes.
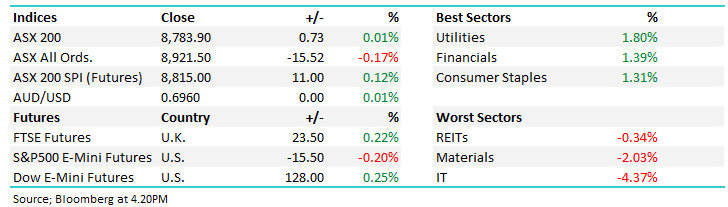
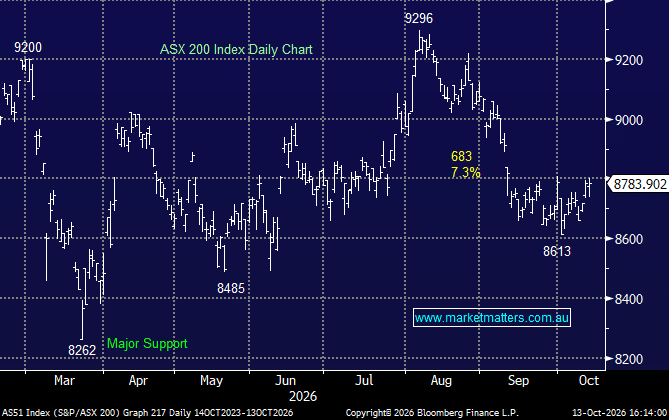
- ASX 200: +0.73pts / +0.01% to 8,783.90
- AUD/USD: 0.6960 / +0.01%
- Best Sectors: Utilities +1.80%, Financials +1.39%, Consumer Staples +1.31%
- Worst Sectors: REITs -0.34%, Materials -2.02% , IT -4.37%
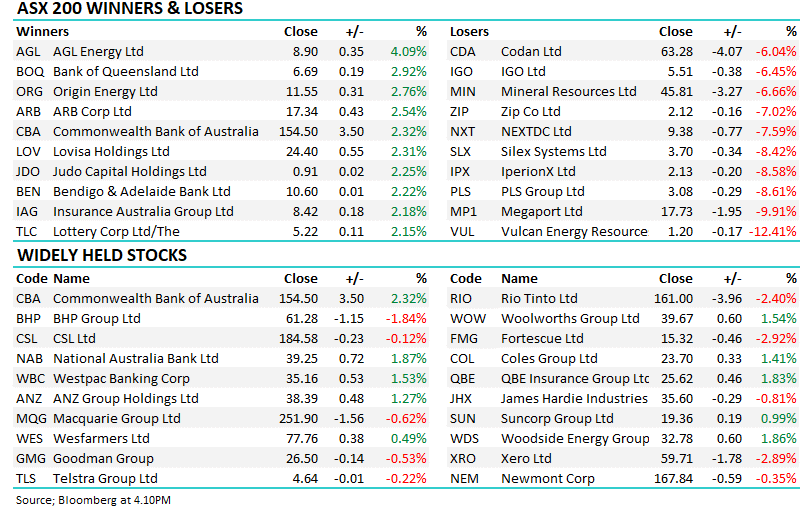
- Utilities and Energy stocks were supported by firmer oil prices, with Brent crude approaching US$107/bbl amid renewed supply concerns. AGL Energy (ASX: AGL) +4.09% to $8.90, Origin Energy (ASX: ORG) +2.76% to $11.55, Santos (ASX: STO) +1.57% to $8.91 and Woodside Energy (ASX: WDS) +1.86% to $32.78 were among the stronger performers. AGL held in the Active Income Portfolio.
- Financials was the bedrock for the index today with Commonwealth Bank (ASX: CBA) +2.32% to $154.50, NAB (ASX: NAB) +1.87% to $39.25, Westpac (ASX: WBC) +1.53% to $35.16 and ANZ (ASX: ANZ) +1.27% to $38.39 higher. Macquarie Group (ASX: MQG) -0.62% to $251.90 bucked the trend. ANZ & WBC held in the Active Growth and Income Portfolios.
- The global chip sell-off intensified on concerns around Chinese memory-chip competition and the cost of financing AI infrastructure hitting the local Tech sector – Megaport (ASX: MP1) -9.91% to $17.73, IperionX (ASX: IPX) -8.58% to $2.13, Zip Co (ASX: ZIP) -7.02% to $2.12, NextDC (ASX: NXT) -7.59% to $9.38 and Xero (ASX: XRO) -2.89% to $59.71 were among the stocks under pressure. XRO held in the Active Growth Portfolio. ZIP held in the Emerging Companies Portfolio.
- Investors took profits as concerns about the global growth outlook weighed on miners – BHP (ASX: BHP) -1.84% to $61.28, Rio Tinto (ASX: RIO) -2.40% to $161.00 and Fortescue (ASX: FMG) -2.92% to $15.32 declined. BHP held in the Active Growth and Income Portfolios.
- Lithium stocks were hit particularly hard after spodumene prices fell, with PLS Group (ASX: PLS) -8.61% to $3.08, Mineral Resources (ASX: MIN) -6.66% to $45.81, IGO (ASX: IGO) -6.45% to $5.51 and Vulcan Energy Resources (ASX: VUL) -12.41% to $1.20 among the major losers.
- Raiz Invest (ASX: RZI) -32% to 34c flagged potentially material tax liabilities relating to historical compliance failures dating back to 2015 as tax withholding and reporting requirements were not met for certain funds, with potential penalties, interest and remediation costs still being assessed. An independent review is continuing, and the company has notified ASIC and the ATO.
- XRF Scientific (ASX: XRF) +12.39% to $1.86 reported a strong September quarter. Revenue increased 38% to $21.1m, while profit before tax rose 30% to $4.4m. Consumables revenue increased 27%, and management expects another strong December quarter.
- Arena REIT (ASX: ARF) +1.69% to $2.0 rose for a fifth time in six sessions as all 27 Arena-owned childcare centres previously operated by collapsed provider Edge Early Learning now have proposed replacement operators.
- Southern Cross Electrical Engineering (ASX: SXE) -8.82% to $4.55 caught up in the Tech selloff given exposure to the data center buildout, though Macquarie raised its price target to $6.00 from $5.60, retaining an Outperform rating. The broker views the acquisition of Entire Operations for up to $112.1m as strategically attractive, with earnings forecasts lifted following the deal announced yesterday.
- Baby Bunting (ASX: BBN) +11.27% to $1.135 reaffirmed FY27 pro forma NPAT guidance of $19m–$21m, although comparable store sales growth slowed to 2.2% over the first 14 weeks, below its full-year target of 3%–5%. Store refurbishments are delivering an average sales uplift of around 20%.
- Gold: Rose ~$US22 to around $US4194 / +0.5%
- Iron ore: $US90.75/mt / -0.2%
- Brent crude: Traded around US$105.30/bbl / -1.2%
- Futures: S&P 500 E-mini futures -15.50pts / -0.20% | Dow Jones futures +128.00pts / +0.25% | FTSE futures +23.50pts / +0.22%.
- US Reporting Tonight: J P Morgan Chase & Co (NYSE: JPM), Wells Fargo (NYSE: WFC), Goldman Sachs (NYSE: GS), Citigroup (NYSE: C), Johnson & Johnson (NYSE: JNJ) and UnitedHealth (NYSE: UNH) the ones to watch.