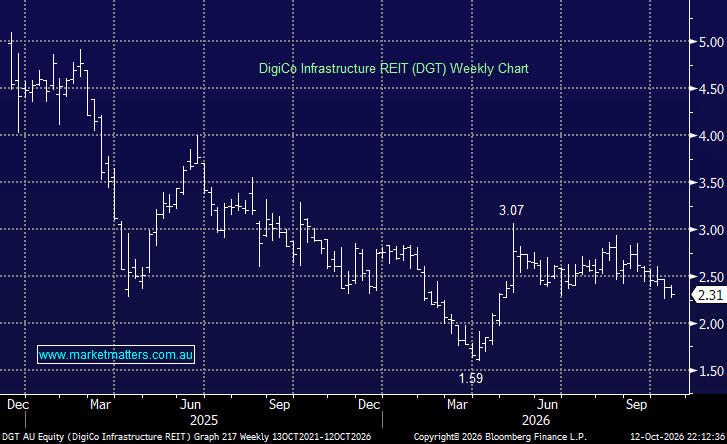
DigiCo listed on the ASX in December 2024 and has essentially halved since then. A few issues at play, summarised as an expensive IPO, disappointing earnings, concerns over capital intensity and leverage. That said, these pain points are on the improve, and DGT could be a different way to play the sector.
DGT is Australia’s only listed pure-play data centre REIT, owning and operating carrier-neutral colocation facilities, anchored by its SYD1 campus in Sydney. Unlike NEXTDC, which is still investing heavily in new capacity, Goodman Group, which combines data centre development with a much larger industrial property portfolio, or Macquarie Technology Group, which also provides cloud and managed services, DigiCo offers direct exposure to data centre infrastructure and recurring colocation income. Its REIT structure makes it more comparable to US operator Equinix, although DigiCo is much smaller, with LTM revenue of approximately US$140 million versus Equinix’s US$9.8 billion.
- One of the main issues for DGT through the second half of 2025 and into early 2026 was investors questioning the scale of capital expenditure, existing leverage and their ability to fund the development pipeline – i.e. a legit concern.
Their 1H26 result showed an improving performance, with underlying EBITDA rising 15% HoH, but more importantly, they sold their Chicago data centre, CHI1, for US$750 million, alongside the sale of its LAX1 and LAX2 sites for approximately US$70 million. The transactions materially strengthened the balance sheet, with gearing expected to fall from 36% to 17%, while allowing management to refocus capital on Australian growth opportunities.
- The ~25% drive higher in May illustrates how funding concerns are weighing on the sector, lessen these worries and the stocks can advance.
DigiCo has since given back some of those gains, but we think the worm could finally be turning here. A better 1H result while they have also secured letters of intent for the remaining 52MW of capacity at its SYD1 facility, supporting planned expansion and targeted delivery over FY27–FY28.
- We like DGT, supported by an estimated 5.2% unfranked yield.
MM is cautiously bullish towards DGT around $2.30
Add To Hit List