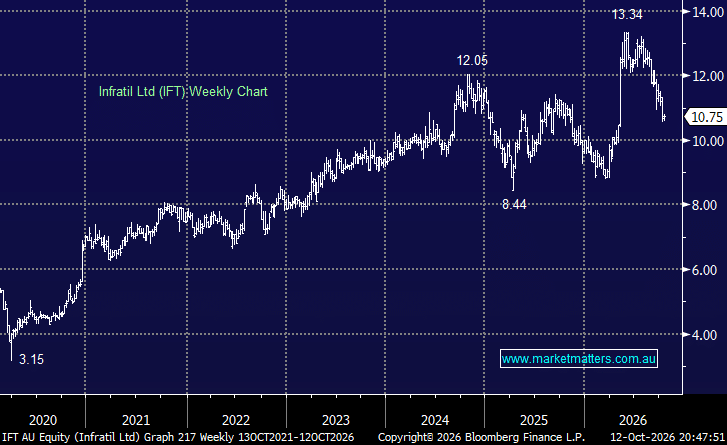
Dual-listed Infratil provides an alternative to direct investment in listed data centre operators, combining AI infrastructure growth with established infrastructure assets. The opportunity hinges on CDC converting its development pipeline into contracted earnings while managing substantial funding requirements and delivering attractive returns on new investment. The stock surged in early May after CDC secured a landmark 555MW, 30-year agreement with a US investment-grade customer, taking total contracted capacity above 1GW. The new contract strengthened earnings visibility, with CDC expecting EBITDA to exceed $1 billion in FY28 and reach ~$2 billion on an annualised basis once the capacity is fully deployed.
- IFT faded after its FY26 result in late May, amid concerns around FY27 earnings expectations, including softer guidance for telecommunications business One NZ.
Infratil, like its peers, has since faced pressure from higher interest rates and renewed scrutiny of AI infrastructure valuations, although CDC’s underlying growth outlook remains strong. The issue is around progress in customer contracting and pipeline development being offset by higher assumed financing costs – a typical theme across the space at the moment.
Technically IFT looks poor after its failed foray above $12 and we wouldn’t be surprised to see the stock test under $10 over the coming months.
- We see no reason to buy IFT at the moment, with other players looking more interesting at current levels.
MM is neutral towards IFT around $11
Add To Hit List