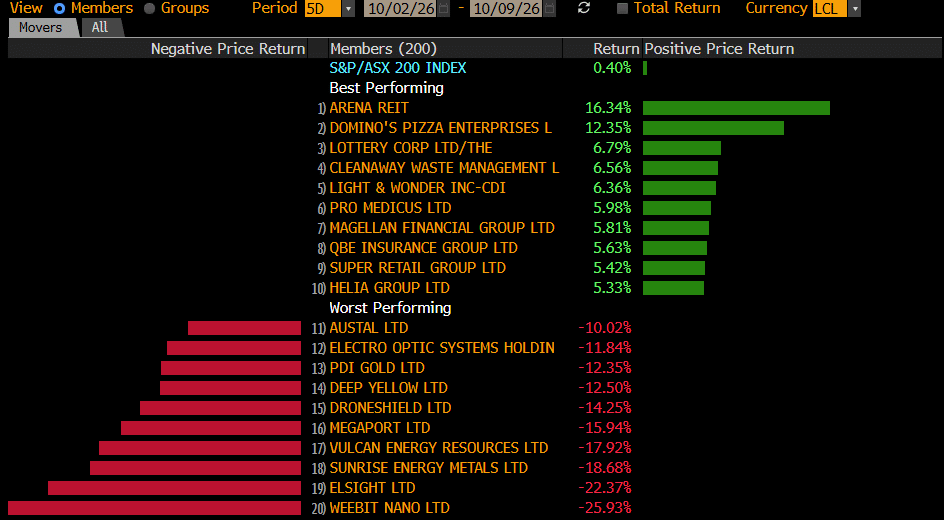
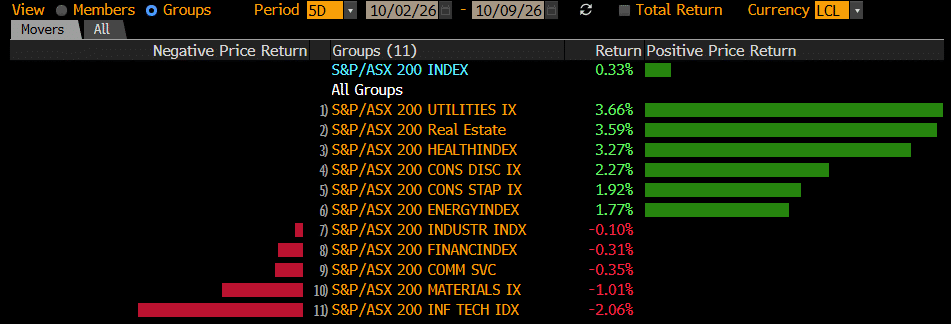
The ASX 200 finished a choppy week up +0.4% with the rate sensitive utilities (+3.6%), real estate (3.6%), healthcare (+3.5%) and consumer discretionary (2.4%) sectors leading the markets gains. Action on the index level was relatively quiet, however, it was anything but on the stock front with 10 stocks falling by more than 10%, for an average decline of more than 16% while only two stocks rewarded investors with double digit gains – it felt like fund managers were actively tweaking their portfolios as we enter the December quarter.
Recovery stocks caught our eye in the winner’s enclosure last week while the energy and defence names figured prominently on the losers side.
Winners: Arena REIT (ASX: ARF) +16%, Domino’s Pizza (ASX: DMP) +12.4%, Lottery Corp (ASX: TLC) +6.8%, Cleanaway Waste (ASX: CWY) +6.6%, Light & Wonder (ASX: LNW) +6.4%, Pro Medicus (ASX: PME) +6%, Magellan (ASX: MFG) +5.8%, & Super Retail (ASX: SUL) +5.4%.
Losers: Weebit (ASX: WBT) -25.9%, Elsight (ASX: ELS) -22.4%, Sunrise Energy (ASX: SRL) -18.7%, Vulcan Energy (ASX: VUL) -17.9%, Megaport (ASX: MP1) -15.9%, DroneShield (ASX: DRO) -14.3%, Deep Yellow (ASX: DYL -12.5%, Electro Optic (ASX: EOS) -11.8%, & Austal (ASX: ASB) -10%.
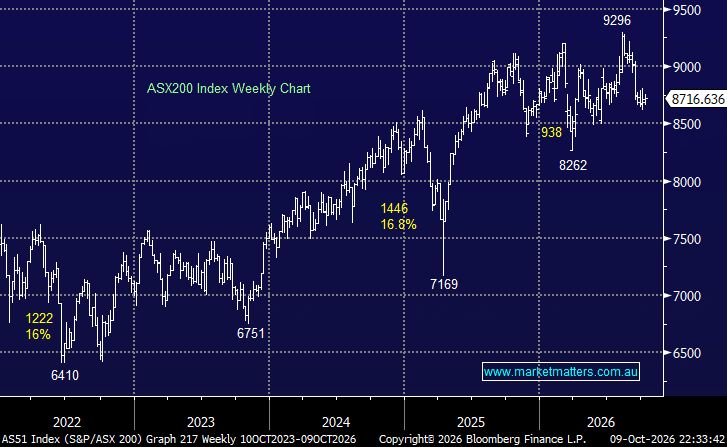
Weekly snapshot: The local market edged higher last week but there’s no formation yet that MMs targeted low is in place:
- The ASX 200 commenced the week on the front foot, shrugging off deteriorating consumer sentiment testing levels not seen since the early 1990’s recession.
- The local market saw further sector rotation into the rate-sensitive names, at the expense of miners & banks, despite no positive lead from bond yields.
- Thursday saw broad-based selling as rising bond yields saw defensive rotation away from the resources sector, plus Maas Group (MGH) fell on concerns the Firmus IPO wouldn’t go ahead.
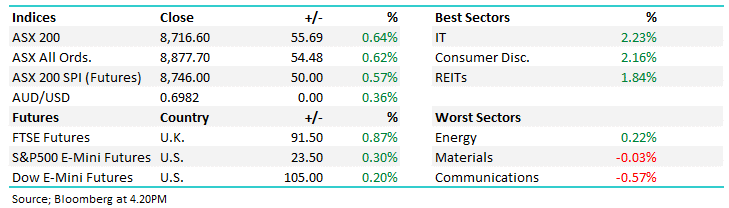
- The ASX 200 exited the first full week of October strongly gaining +0.6% despite the failed Firmus IPO and mixed performances from the heavyweight miners.
In the coming week the markets focus will be on two pivotal economic releases, plus the start of US earnings season: US CPI on Wednesday, a key factor determining the Fed’s rate outlook, and Australian employment on Thursday, which will help influence expectations for the RBA. For the S&P 500, hotter-than-expected inflation could weigh on sentiment, while bank earnings will be watched closely for what comes next. The ASX 200 faces a double test of its own, with domestic labour market data influencing the RBA outlook and Wall Street’s ability to punch to new highs will be monitored closely.
Overseas markets were firm into the weekend ahead of US earnings season despite firm oil prices, and soft chipmakers. In Europe, the German DAX (+1.1%) and UK FTSE (+1.1%) both enjoyed strong gains. In the US, the S&P 500 (0.6%) and tech-based NASDAQ (+0.5%) both ended the session near their intra-day high, knocking on the doors of all-time highs.
- The SPI Futures are calling the ASX 200 to open up +0.4% on Monday following strong performances on overseas bourses and a more than $1 gain by BHP in US trade.