- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
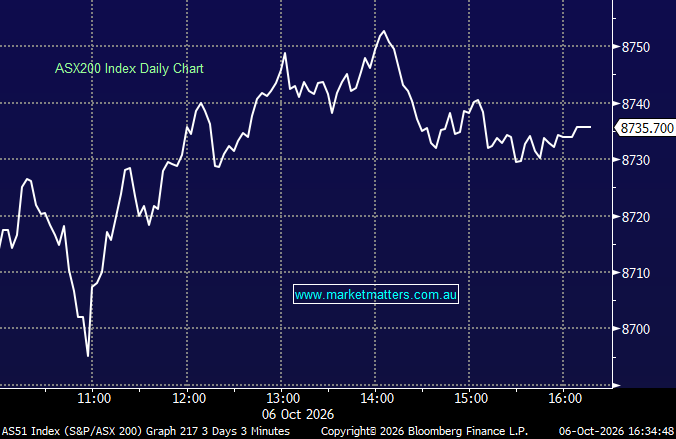
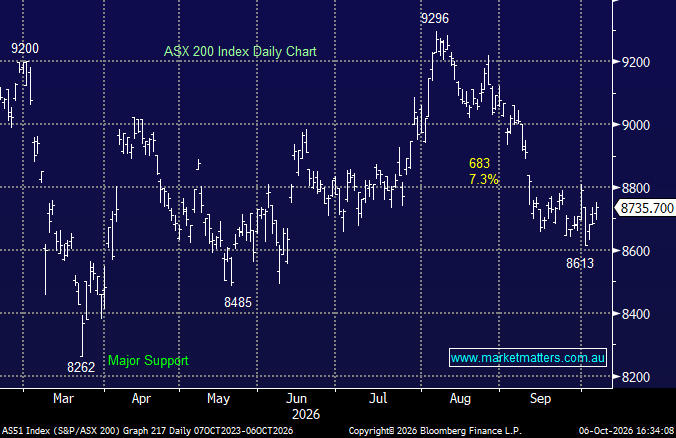
The ASX moved higher for a third straight session with some confidence returning to the market. The rally was driven by a very different mix of stocks to what we saw on Wall Street overnight, with Real Estate leading despite bond-yields remaining elevated, and Materials also looking strong. Technology was the only significant detractor, failing to mirror the move seen overnight in the US as the tech-focused Nasdaq surged to new all-time highs.
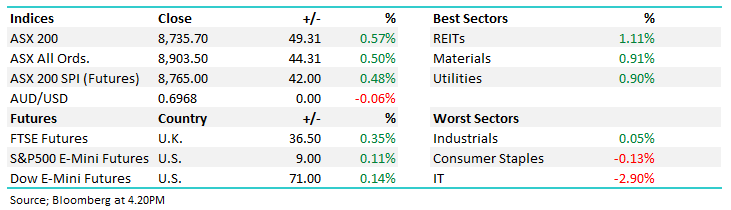
- ASX 200: +49.31pts / +0.57% to 8,735.70
- AUD/USD: 0.6968 / -0.06%
- Best sectors: REITs +1.11%, Materials +0.91%, Utilities +0.90%
- Worst sectors: Industrials +0.05%, Consumer Staples -0.13%, IT -2.90%
- The domestic economic backdrop took a hit, with the Westpac-Melbourne Institute Consumer Sentiment Index falling 4.7% to 80.4 in October – though the market took it in its stride.
- The post-RBA reading fell to just 67.2, from 86.9 before the rate decision — a level only seen in complete surveys during the early-1990s recession. More than 80% of respondents now expect mortgage rates to rise over the next year, while the willingness to buy major household items fell 7.1%
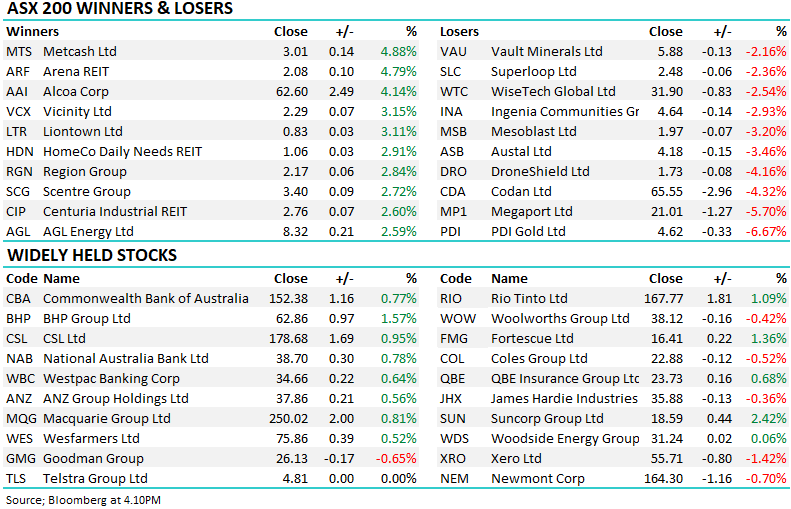
- Materials performed well – BHP Group (ASX: BHP) +1.57% to $62.86 (held in Active Growth & Active Income Portfolios), South32 (ASX: S32) +1.21% to $5.03 (held in Active Growth Portfolio) and Sandfire Resources (ASX: SFR) +0.58% to $22.38 (held in Active Growth Portfolio) were all higher on stronger copper prices.
- Lithium bounced also bounced with Liontown Resources (ASX: LTR) +3.11% to $0.83 and Pilbara Minerals (ASX: PLS) +2.42% to $3.81 while Alcoa Corp (ASX: AAI) +4.14% to $62.60 jumped as aluminium prices finally snapped a five-day losing streak.
- The big negative was Technology, which failed to participate in the Nasdaq-led global rally. Xero (ASX: XRO) -1.42% to $55.71 (held in Active Growth Portfolio), WiseTech Global (ASX: WTC) -2.54% to $31.90 (held in Active Growth Portfolio) and Megaport (ASX: MP1) -5.70% to $21.01 were among the day’s notable decliners.
- Dicker Data (ASX: DDR) entered a trading halt ahead of a proposed material acquisition. The company was up 56.5% YTD and had closed at record highs on Monday, with $57.2m of cash at June 30 to fund the acquisition, though a raise could be on the cards.
- EQ Resources (ASX: EQR) -11.39% to 35c as revenue more than doubled to a record $158.8m in the September quarter, production rose 81% and cash jumped 192% to $82.3m, although the stock subsequently gave back its early gains.
- SKS Technologies (ASX: SKS) +2.01% to $11.17 moved higher on another $38m of electrical works on the MEL2 data centre, taking the project’s total value to $66m and work on hand to $270m.
- LGI Ltd (ASX: LGI) +13.11% to $2.20 agreed to acquire two operating Queensland solar farms for $22m, lifting its medium-term capacity target by 50% to more than 120MW.
- Rio Tinto (ASX: RIO) +1.09% to $167.77 rose as Morgan Stanley remains Underweight despite seeing potential value from Rio’s infrastructure asset sales, citing stretched valuation, iron ore fundamentals and limited copper growth.
- Brent crude: Rose to US$101/bbl / +0.4%
- Gold: Down US$20 to around US$4,11/oz / -0.5%
- S&P 500 E-mini futures: +9.00pts / +0.11% | Dow E-mini futures: +71.00pts / +0.14%