- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
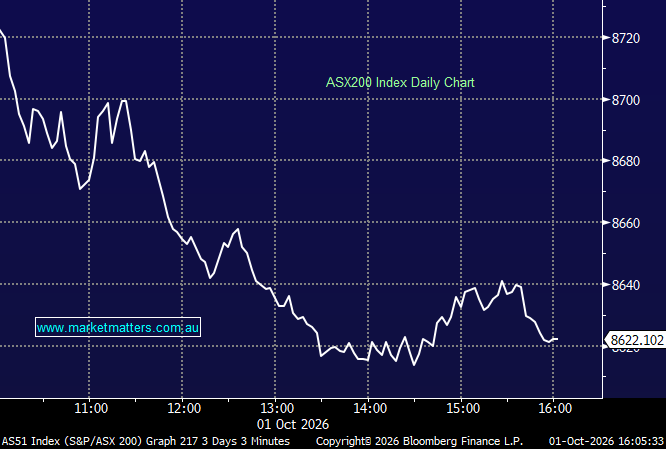
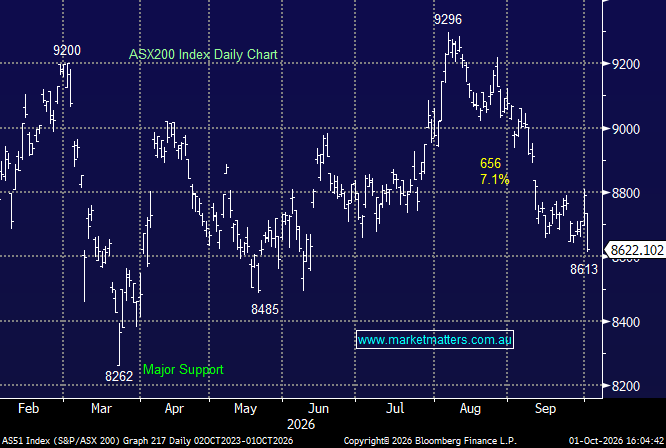
Today’s move was effectively the mirror image of yesterday with the ASX back to its lowest level since June. The market rallied almost 1% yesterday on softer CPI and hopes that the RBA may be close to the end of its tightening cycle, but bond yields reversed higher overnight and quickly put that trade under pressure. Nothing fundamental really changed from yesterday here locally, in fact, credit market pricing of another hike this year has fallen from ~60% on Monday to 30% today. On the sector level, all 11 traded lower with Real Estate the biggest one-day reversal after being the standout sector yesterday. Energy was no exception – we have become accustomed to the market rising on lower oil prices given the inflation read-through for equities more broadly, though that wasn’t the case today. On the index level, it was Financials doing most of the damage with the Big Four accounting for almost -40pts of ASX200 weakness between them.
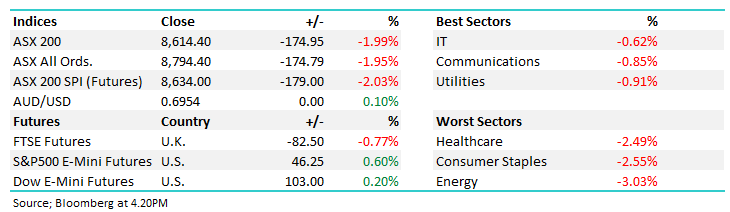
- ASX 200: -174.95pts / -1.99% to 8,614.40
- AUD/USD: 0.6954 / +0.10%
- Best sectors: IT -0.62%, Communications -0.85%, Utilities -0.91%
- Worst sectors: Energy -3.03%, Healthcare -2.49%, Consumer Staples -2.55%
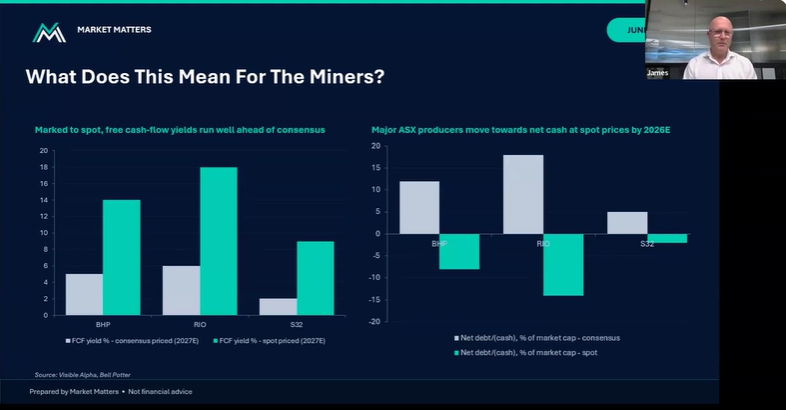
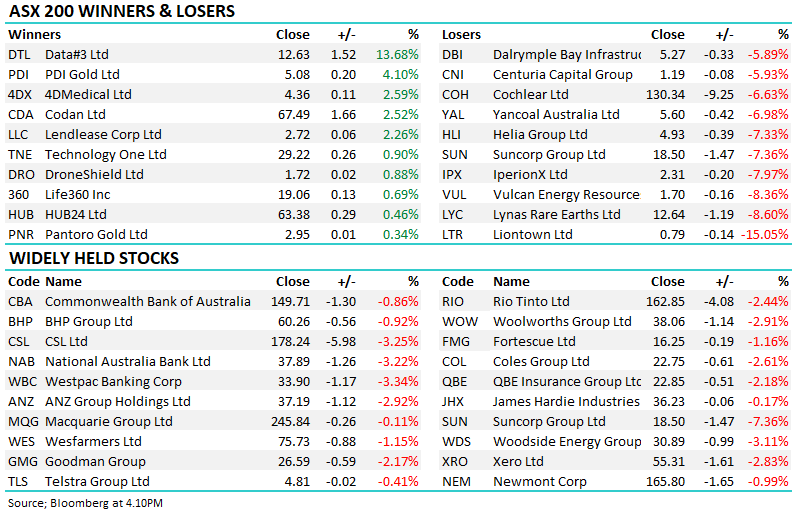
- Materials stocks were broadly softer, with BHP (ASX: BHP) -0.92% to $60.26, Rio Tinto (ASX: RIO) -2.44% to $162.85 and South32 (ASX: S32) -2.96% to $4.91 all retreating. BHP held in the Active Growth and Income Portfolios. S32 held in the Active Growth Portfolio.
- Real estate stocks gave back some of yesterday’s strong gains, with Goodman Group (ASX: GMG) -2.17% to $26.59, Charter Hall (ASX: CHC) -3.23% to $18.25, Scentre Group (ASX: SCG) -2.57% to $3.41 and Stockland (ASX: SGP) -3.71% to $4.15 all weaker as REITs finished as the second worst performing sector. GMG held in Active Growth Portfolio.
- Energy was the worst performing sector, with Woodside Energy (ASX: WDS) -3.11% to $30.89, Santos (ASX: STO) -2.67% to $8.39 and Beach Energy (ASX: BPT) -5.71% to $0.83 all under pressure as Brent crude slipped on recovering Middle East supply.
- Data#3 (ASX: DTL) +13.68% to $12.63 was one of the clear standouts, guiding to 1H FY27 gross profit growth of >15% and PBT growth of >40%, well ahead of expectations.
- Lynas Rare Earths (ASX: LYC) -8.60% to $12.64 fell sharply after announcing its $968m all-scrip acquisition of Meteoric Resources and the Caldeira rare-earths project in Brazil. The deal provides a substantial resource uplift, but the focus was on development costs, with the project requiring ~US$500m of capex.
- Yancoal Australia (ASX: YAL) -6.98% to $5.60 completed its US$1.85bn acquisition of an 80% interest in Kestrel, with earnings contribution beginning from today.
- Liontown Resources (ASX: LTR) -15.05% to $0.79 was whacked after four brokers slashed price targets on the stock after revealing heightened funding requirements for the Kathleen Valley project yesterday.
- Transurban (ASX: TCL) -1.74% to $13.01 agreed to pay $4.5bn to acquire CPPIB’s stakes in three Sydney motorways, taking its interest in Westlink M7/NorthConnex to 75% and WestConnex to 60.5%.
- Gold: US$4187, +0.7%
- Iron Ore: US$92.60 / -0.9%
- Oil: US$97.40 / -0.6%
- S&P 500 E-mini futures: +46.25pts / +0.60% | Dow E-mini futures: +103.00pts / +0.20% | FTSE futures: -82.50pts / -0.77%