- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
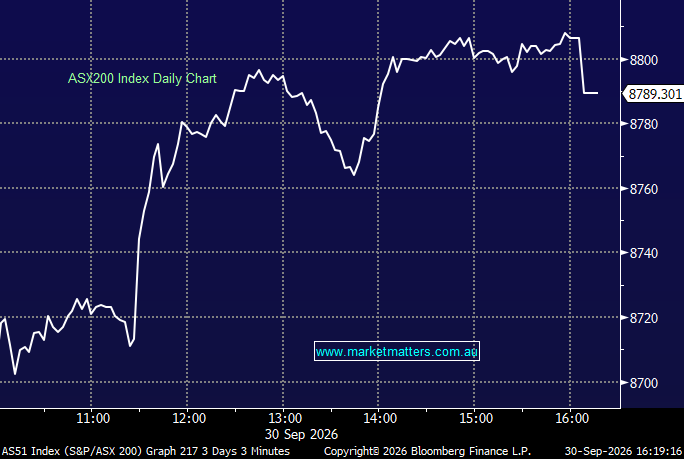
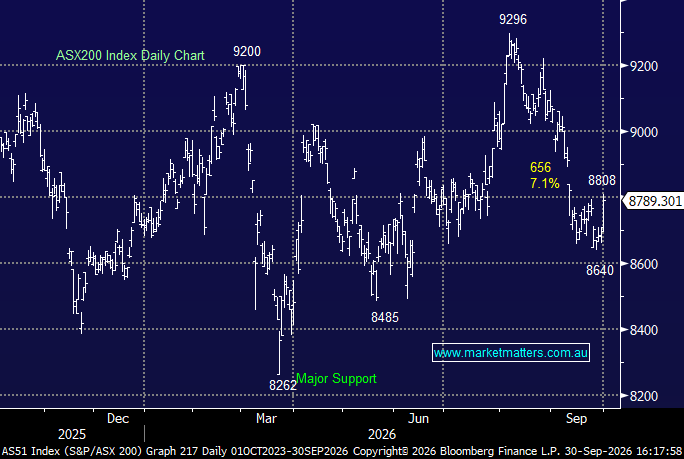
September finished with a much-needed relief rally as softer inflation data this morning and RBA Governor Michele Bullock’s less than hawkish commentary yesterday afternoon triggered a sharp rebound in beaten-up Real Estate, Discretionary and other rate-sensitive stocks. Resources and Energy also added to the index move, as all sectors finished higher for the day with the exception of Technology stocks. September’s sell-off had become increasingly driven by higher bond yields so today’s move effectively gave some relief on the discount-rate side as rate hike bets for the final RBA meeting in 2026 were pared back to ~40%.
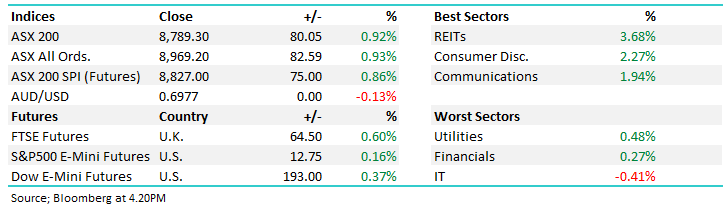
- ASX 200: +80.05pts / +0.92% to 8,789.30
- AUD/USD: 0.6977 / -0.13%
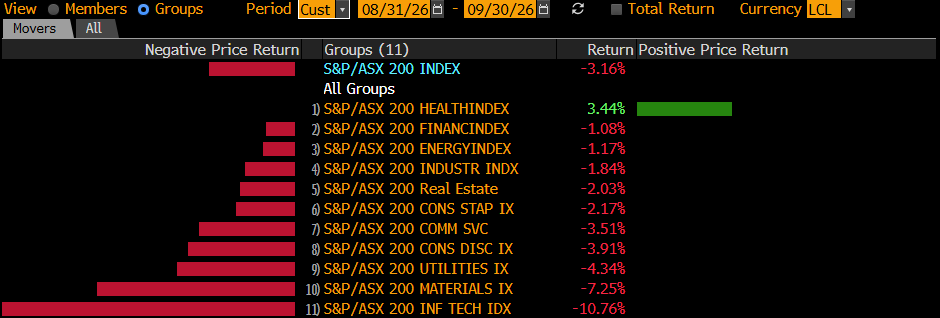
- Best sectors: REITs +3.68%, Consumer Disc. +2.27%, Communications +1.94%
- Worst sectors: IT -0.41%, Financials +0.27%, Utilities +0.48%
- August CPI data released at 11:30am was the key catalyst for the move today – headline inflation rose to 4.0% year-on-year from 3.5%, but came in below the 4.1% expected. More importantly for the RBA, trimmed mean inflation remained at 3.6%, while the monthly trimmed mean increased just 0.2%, below the 0.3% expectation.
- As expected, Real estate stocks were among the day’s biggest winners with the REIT sector leading all sectors – Lendlease (ASX: LLC) +11.30% to $2.66 was the standout, while Charter Hall (ASX: CHC) +6.43% to $18.86 and REA Group (ASX: REA) +5.85% to $157.50 also had strong sessions.
- Consumer Discretionary names have had a tough time given the ‘higher for longer’ assumption about rates, enjoying a solid bounce today with Super Retail Group (ASX: SUL) +1.18% to $12.85, JB Hi-Fi (ASX: JBH) +4.69% to $70.28 and Harvey Norman (ASX: HVN) +2.4% to $4.26 all moving higher. Domino’s Pizza (ASX: DMP) +6.32% to $20.53 was also a standout mover on the day.
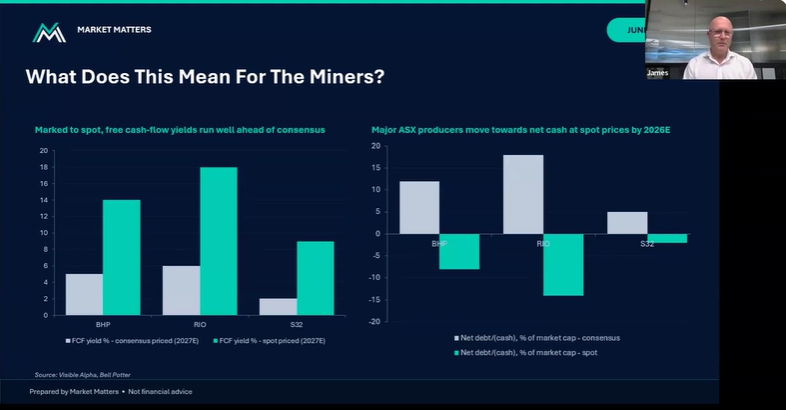
- Resources firmed, although the move was less pronounced than in property and discretionary. BHP Group (ASX: BHP) +0.31% to $60.82, Rio Tinto (ASX: RIO) +1.56% to $166.93 and South32 (ASX: S32) +0.8% to $5.06 were solid.
- There was also a positive read-through for the major iron ore producers, with UBS lifting its long-term iron ore price assumption to US$93/t from US$85/t, citing China’s strategic pivot towards manufacturing and exports, demographic growth across the Global South and favourable supply-side dynamics.
- Codan (ASX: CDA) +2.17% to $65.83 extended Tuesday’s huge rally, now up around 141% YTD, following its upgraded FY27 outlook and strong demand for its communications technology.
- DroneShield (ASX: DRO) +5.26% to $1.70 gained after securing a place on a US$500m US homeland defence contract vehicle, although no orders are guaranteed under the IDIQ arrangement.
- Austal (ASX: ASB) +5.65% to $4.49 continued higher amid the competing takeover interest surrounding the company.
- Northern Star (ASX: NST) +6.35% to $24.77 rose on reports Gold Fields may sweeten the cash component of its proposed takeover.
- Lendlease (ASX: LLC) +11.30% to $2.66 led the property rebound, with the company also progressing the divestment of its remaining 25.1% interest in the Keyton Retirement Living Trust returning $550m in cash to the balance sheet.
- Pinnacle Investment Management (ASX: PNI) -4.87% to $13.28 continued to trade under pressure as the Metrics Credit Partners audit delay and fund suspensions remained an overhang.
- Liontown Resources (ASX: LTR) -2.11% to $0.93 approved a $389m Kathleen Valley expansion, targeting steady-state production of around 780,000dmt a year from FY30, roughly 75% above the FY27 guidance midpoint.
- Brent: US$102.60, -2.6%, as Middle East crude flows recover.
- Gold: US$4,180, flat.
- Iron Ore: US$94.20/mt, +0.8%.
- Australian 3-year yield: ~4.92%, fell ~7bps.
- S&P 500 E-mini futures: +12.75pts / +0.16% | Dow E-mini futures: +193.00pts / +0.37% | FTSE futures: +64.50pts / +0.60%