- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
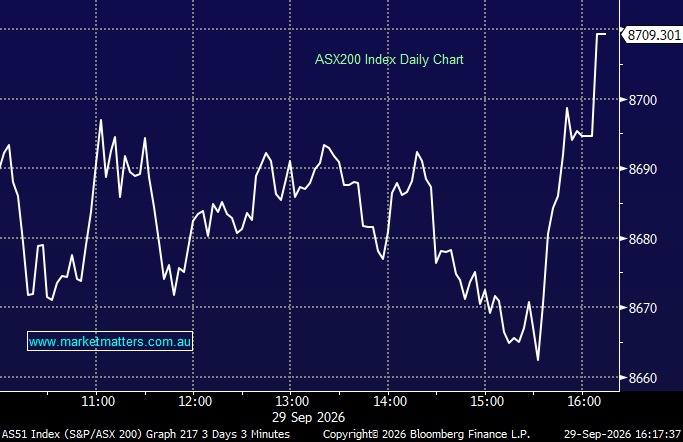
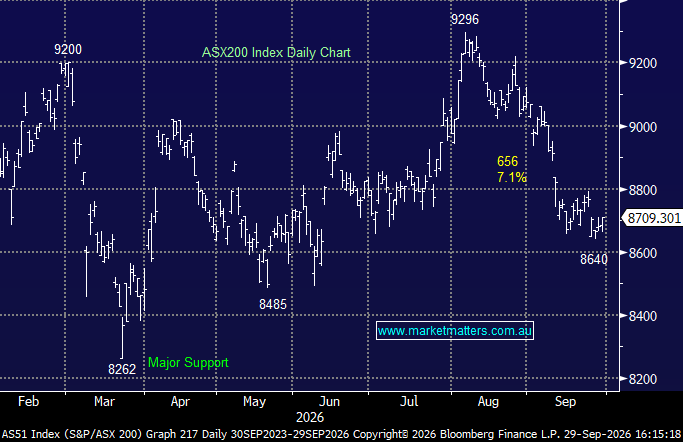
The ASX ended up notching a decent gain today after a choppy session leading up to the 2:30pm RBA decision. At the sector level, a strong rebound in Technology and Materials helped offset weakness across Energy, Real Estate and Financials ahead of the decision. The market initially dipped after the Board voted to raise rates by 25bps to 4.60%, however, commentary from Michele Bullock at the ensuing press conference was less hawkish than expected, triggering a quick ~30pt jump in the final minutes of trade. While further tightening remains on the table, Bullock pushed back against expectations for rates to head rapidly towards 5%+, emphasising that the next moves will be data-dependent – putting tomorrow’s inflation data firmly in focus.
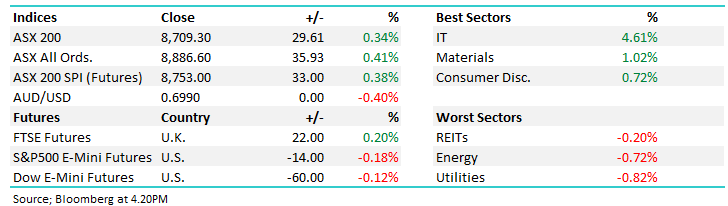
- ASX 200: +29.61pts / +0.34% to 8,709.30
- AUD/USD: 0.6990 / -0.40%
- Best sectors: IT +4.61%, Materials +1.02%, Consumer Disc. +0.72%
- Worst sectors: Utilities -0.82%, Energy -0.72%, REITs -0.20%
- The RBA lifted the cash rate 25bp to 4.60%, its fourth hike this year, citing stronger-than-expected inflation and the materialisation of upside risks.
- Bullock pushed back against expectations for a much more aggressive tightening cycle, specifically downplaying the idea that rates could need to rise another two times to 5.10%. She said if the three hikes already delivered are enough to bring inflationary pressures back down, “maybe there doesn’t need to be any more interest rate rises“.
- On stagflation, Bullock rejected the characterisation, pointing to inflation of 3.5% and unemployment of 4.6% as inconsistent with the traditional definition of very high inflation and very high unemployment.
- Bond yields were another focus, with Bullock saying the global rise in yields remains orderly rather than disorderly. However, she acknowledged the RBA is watching elevated asset prices closely, particularly in technology, given the potential risks associated with a disorderly bond-market pullback.
- Importantly, a recession is not the RBA’s base case, with Bullock saying the economy can continue to grow while monetary policy gradually brings demand and inflation back into balance.
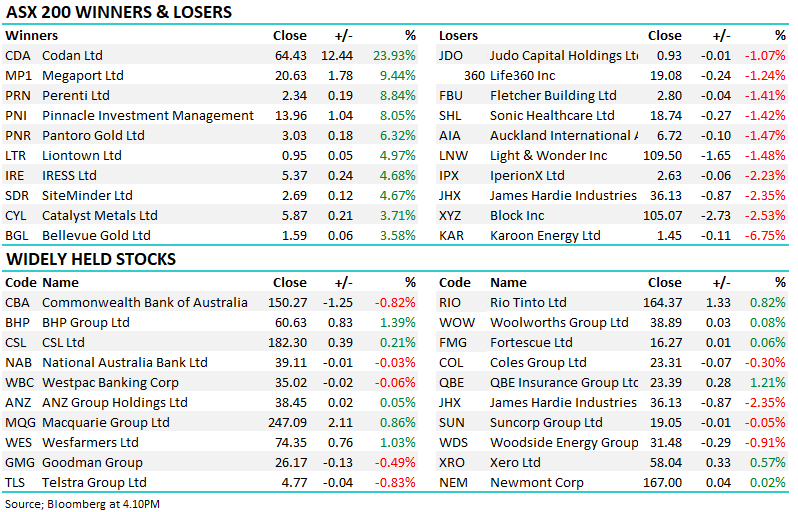
- Technology was the standout in the session, rebounding strongly after weeks of heavy selling. Codan (ASX: CDA) +23.93% to $64.43 hit another record following a major FY27 upgrade.
- Megaport (ASX: MP1) +9.44% to $20.63 announced three new AI infrastructure contracts with combined TCV of $978.6m, taking strategic TCV since April to around $2.3bn. FY27 revenue guidance was raised to $720–810m and EBITDA margin guidance to 42–44%.
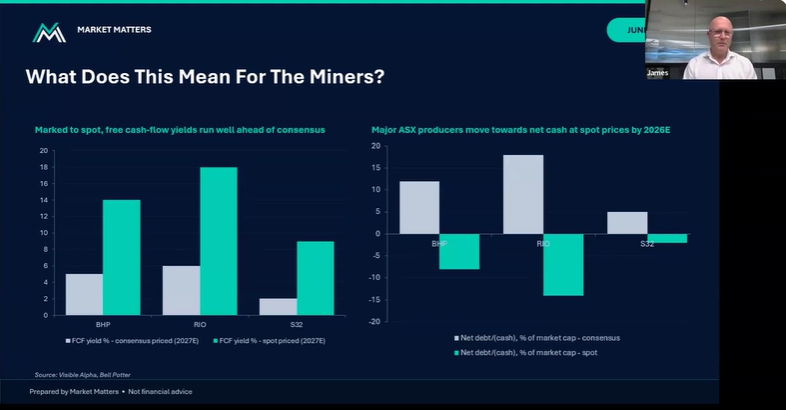
- Materials managed a modest gain despite weaker overnight commodity prices, with copper names relatively resilient. South32 (ASX: S32) +2.87% to $5.02, Aeris Resources and BHP (ASX: BHP) +1.39% to $60.63 as copper approached record highs on the back of a potential strike at Chile’s Centinela mine. BHP held in Active Growth and Income Portfolios. S32 held in Active Growth Portfolio.
- Pinnacle Investment Management (ASX: PNI) +8.05% to $13.96 bounced after UBS upgraded the stock to Buy, arguing that the recent 26% sell-off had more than discounted its exposure to Metrics Credit Partners. Metrics’ delayed audit reduced NTA across its suspended listed vehicles by 2–12%.
- Perenti (ASX: PRN) +8.84% to $2.34 secured more than $200m of new drilling and underground contracts, including around $185m of FY27 revenue from drilling contracts across Australia, the US and Canada.
- Catalyst Metals (ASX: CYL) +3.71% to $5.87 lifted Ore Reserves across the Plutonic Gold Belt to 2Moz, supporting a target of around 200koz of annual production for approximately 10 years.
- Adairs (ASX: ADH) -5.06% to $1.22 CEO and MD Elle Roseby resigned after two years in the role, with the board beginning a search for her successor. Focus on Furniture trading improved through the quarter, although the first half is expected to remain challenging.
- Household spending: was flat in August versus expectations for +0.4%, while annual growth slowed to 6.8% from 7.1% expected. Excluding fuel, spending actually fell 0.3%.
- Gold: around US$4,117.60/oz, little changed after falling 4% on Monday.
- Iron Ore: US$94/mt / -0.8%
- Copper: US$14,438/t, +0.2%, approaching its record high.
- Global Futures: S&P 500 E-mini -14.00pts / -0.18% | Dow E-mini -60.00pts / -0.12% | FTSE +22.00pts / +0.20%