Australian gold assets have become increasingly strategically attractive to offshore producers, with record/high gold prices generating acquisition firepower. Australia offers relatively low jurisdictional risk, and as discussed, buying existing mines and infrastructure is often faster and less risky than discovering and permitting new ounces. The Gold Fields approach for NST adds further evidence that global majors are actively looking at Australian gold exposure, although we believe this specific foray will fail.
- CMM is the pick for quality. It has the growth, the balance sheet and the jurisdiction that Gold Fields was clearly seeking with its NST bid. However, it will be hard for a suitor to get a deal over the line with management; a merger may be more likely.
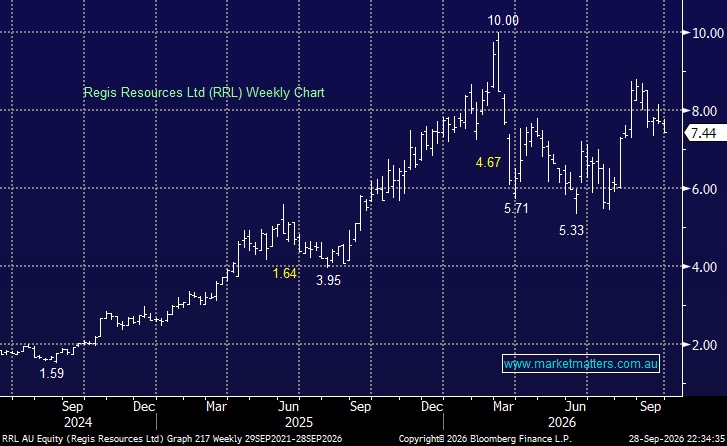
- RRL is the hardest call because it’s just as likely to be an acquirer as a target, but it needs to improve scale and may be more open to a bid compared to the likes of CMM.
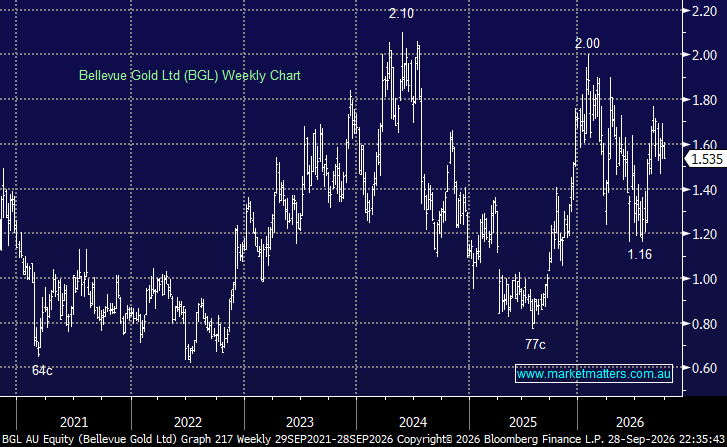
- We believe BGL is the most likely target and offers the most upside from a takeover.