- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
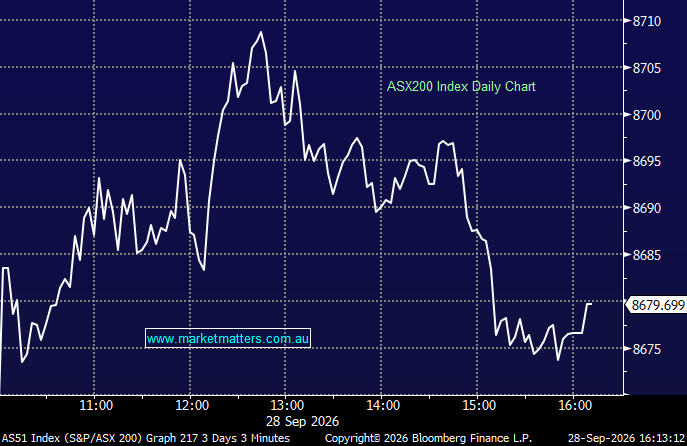
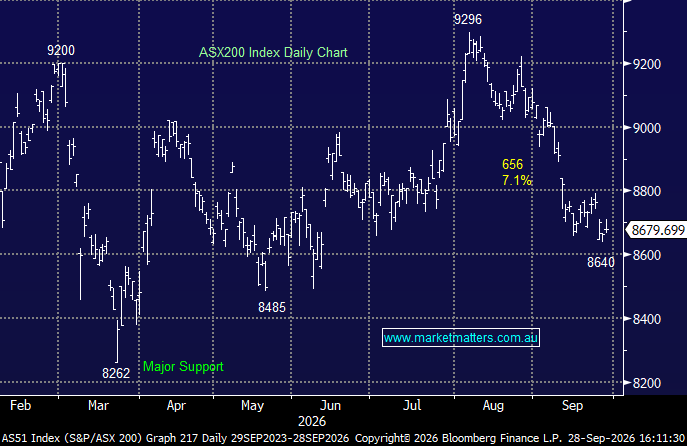
The local index bounced strongly this morning, recovering from a three-month low on Friday, poking its head above the 8700 level before giving most of it back through the afternoon. The modest gain was driven by banks and defensives rather than a broad-based recovery and while Financials, Healthcare and Utilities looked solid, higher oil prices and bond yields kept Technology and Materials under pressure ahead of tomorrow’s RBA decision.
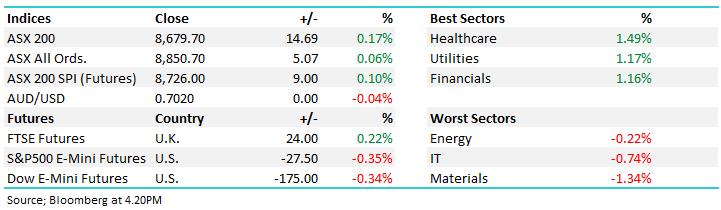
- ASX 200: +14.69pts / +0.17% to 8,679.70
- AUD/USD: 0.7020 / -0.04%
- Best sectors: Healthcare +1.49%, Utilities +1.17%, Financials +1.16%
- Worst sectors: Materials -1.34%, IT -0.74%, Energy -0.22%
- Financials led the market, with the major banks catching a bid ahead of tomorrow’s RBA decision. Markets are pricing around a 90% probability of a 25bp hike to 4.60%.
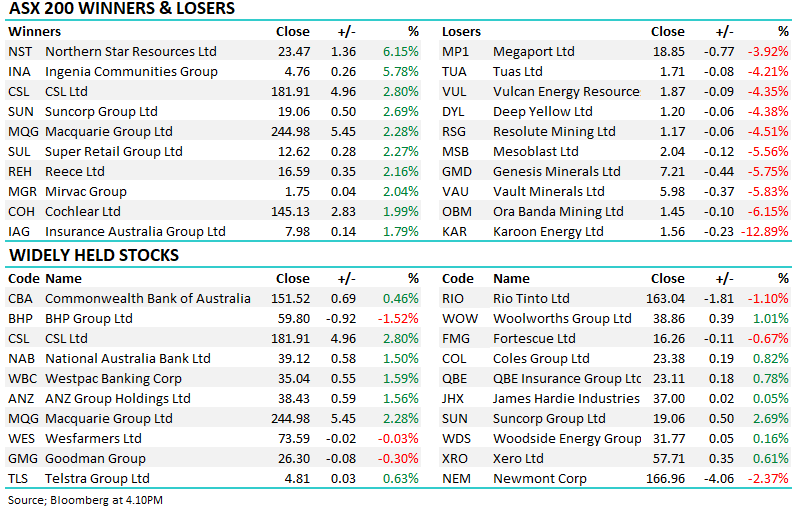
- Commonwealth Bank (ASX: CBA) +0.46% to $151.52, Westpac (ASX: WBC) +1.59% to $35.04, ANZ Group (ASX: ANZ) +1.56% to $38.43 and NAB (ASX: NAB) +1.50% to $39.12 all firmed ahead of the decision. ANZ held in Active Growth and Income Portfolios. WBC held in Active Income Portfolio.
- Healthcare and Utilities were also strong, CSL (ASX: CSL) +2.80% to $181.91, Cochlear (ASX: COH) +1.99% to $145.13, APA Group (ASX: APA) +1.32% to $10.77, Origin Energy (ASX: ORG) +1.01% to $10.95 – the defensive tilt was notable given the continued rise in bond yields and oil. APA held in the Active Income Portfolio.
- Northern Star (ASX: NST) +6.15% to $23.47 rallied after rejecting a non-binding ~$27/share cash + scrip Gold Fields takeover proposal, which valued the company at approximately $38.7bn.
- Ingenia Communities (ASX: INA) +5.78% to $4.76 rose after Warburg Pincus lifted its non-binding proposal to $5.25 per security, up from $5.05 and $4.75 previously. The proposal remains conditional and requires Ingenia to terminate its existing Peet transaction.
- Karoon Energy (ASX: KAR) -12.89% to $1.55 was the standout loser after a cable fault at its Baúna field forced another production downgrade. CY26 production guidance was cut 10% at the midpoint, while unit production costs were increased to US$15–16/boe.
- Pinnacle Investment Management (ASX: PNI) -1.97% to $12.92 came under pressure after its Metrics Credit Partners exposure became the latest concern in the private-credit space. Three Metrics funds were suspended ahead of audited results, with MRE’s NTA cut 12.2% and MXT’s NTA cut 2.0% following KPMG’s audit review. Pinnacle owns about 35% of Metrics’ holding company. Held in the Emerging Companies Portfolio.
- GPT Group (ASX: GPT) +0.45% to $4.43 CEO Russell Proutt bought $555,000 worth of shares last week, with the stock having fallen 17% over the past year.
- Brent crude: around US$105–106/bbl, rising as the US rejected Iran’s latest proposal to reopen the Strait of Hormuz.
- Gold: around US$4,169/oz / -2.7%
- Iron Ore: US$94.70/mt / -0.6%
- Global Futures: S&P 500 E-mini futures: -27.50pts / -0.35%, Dow E-mini futures: -175.00pts / -0.34% and FTSE futures: +24.00pts / +0.22%