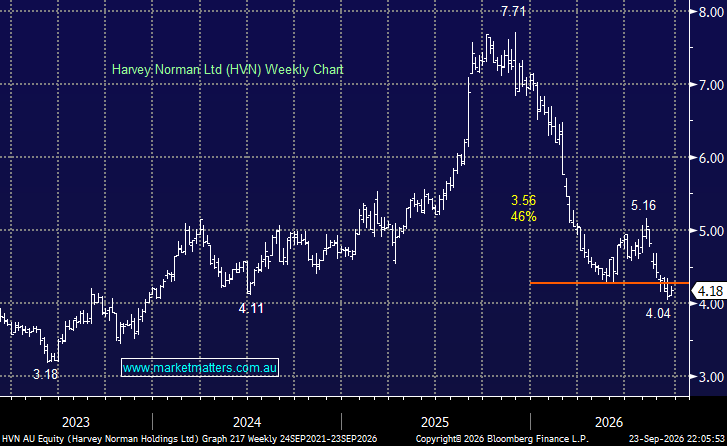
Gerry Harvey’s retail business has also almost halved over the last year, driven by a soft Australian consumer – being underweight the local consumer is becoming an increasingly crowded trade that may be correct for now, but could easily see a sharp snap back into Christmas. We covered HVN in detail earlier in the month here, and with the stock moving ~6% lower since then, it’s approaching our buy level.
Similar to ARB, and many of the Australian retail stocks, HVN’s fall has been driven far more by multiple compression than falling earnings, with the forward P/E contracting ~35% from 18.7x to 12.2x, compared with an 18.2% decline in forward EPS from $0.434 to $0.355. With earnings proving relatively more resilient, the share-price weakness primarily reflects a significant loss of investor confidence in the Australian consumer, rather than an equivalent collapse in underlying profitability.
- We can see HVN testing $5 if we see an aggressive rally into Christmas, ~25% above its recent low – a more than 6% fully franked yield will help patient shareholders.
MM is bullish towards HVN around $4
Add To Hit List