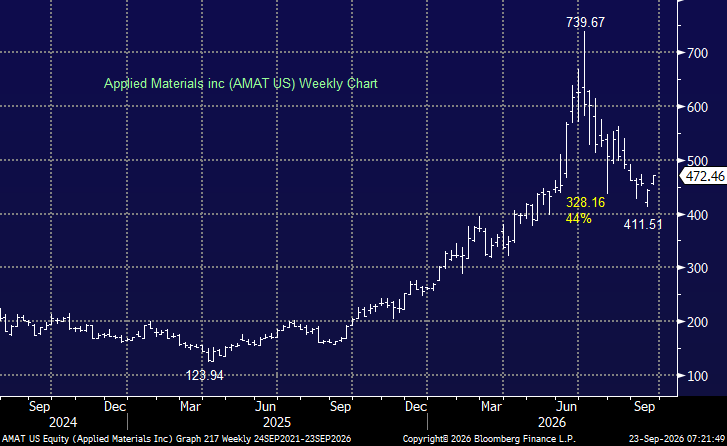
Applied Materials (AMAT) remains an interesting way to gain exposure to the AI semiconductor build-out, particularly after the recent ~40% pullback. The stock has fallen from above US$700 to around US$450, despite earnings expectations continuing to move sharply higher. That combination – strong earnings momentum with a weaker share price, has materially improved the risk/reward.
AMAT is one of the world’s largest semiconductor equipment manufacturers, supplying the machinery required to manufacture advanced chips. It doesn’t need to pick whether NVIDIA, AMD, Broadcom or another chip designer ultimately wins the AI race; it sells the equipment required by the company’s manufacturing increasingly complex semiconductors. And complexity is really the key to the thesis.
AI chips require more advanced transistor structures, significantly more high-bandwidth memory, increasingly complex packaging and more processing steps. As chip complexity rises, the amount of equipment required to manufacture each wafer also increases. More complexity means greater capital intensity, which means more opportunity for AMAT.
Earnings are already reflecting this with AMAT delivering record quarterly revenue of US$9.12bn, up 25% year-on-year, while earnings per share (EPS) increased 41% to US$3.50. Management has also guided to another strong quarter and expects growth to continue into 2027.
What is particularly interesting is how quickly consensus earnings are now moving higher. Bloomberg has adjusted EPS rising from around US$13 in FY26 to US$18.74 in FY27, US$23.78 in FY28 and more than US$26 in FY29. Revenue is expected to rise from roughly US$34bn in FY26 to more than US$60bn by FY29, while free cash flow is forecast to more than double between FY26 and FY27. Those are powerful numbers.
At first glance, AMAT still looks expensive on around 34x FY26 earnings. However, that multiple falls rapidly if consensus is right, to around 24x FY27 earnings and 19x FY28 earnings. For a company likely to deliver very strong earnings growth over the next few years, that valuation is not as stretched as it might look.
High Bandwidth Memory (HBM) remains one of the most important parts of the story. AI accelerators require enormous amounts of high-speed memory sitting alongside the processor, and HBM is considerably harder to manufacture than traditional DRAM. It requires more layers, more processing steps and more advanced packaging. AMAT therefore benefits not only from rising semiconductor demand, but from increasing equipment intensity per chip.
The same applies to advanced packaging. Historically, semiconductor performance improved largely by shrinking transistors. Increasingly, chipmakers are improving performance by combining multiple specialised chips using chiplets, 3D stacking and hybrid bonding, which is where AMAT is investing heavily.
In terms of share price, AMAT rallied from around US$150 in early 2025 to more than US$600 earlier this year before correcting back toward US$450. We generally prefer buying strong structural growth stories after a meaningful pullback rather than chasing them at the highs, and AMAT is starting to fit that framework.
The broker community remains very bullish, with Bloomberg showing a consensus 12-month target of ~US$661, implying close to 50% upside from current levels, with almost 90% of analysts carrying a Buy rating. We wouldn’t rely on broker price targets alone, but the key point is that earnings expectations remain strong even as the share price has fallen materially.
In terms of risk, China remains the most obvious one, with AMAT exposed to further US export restrictions and the longer-term rise of domestic Chinese semiconductor equipment suppliers. The semiconductor cycle is another risk; if AI capex slows, memory prices weaken or foundries delay new capacity, equipment orders can fall quickly. There is also execution risk embedded in the forecasts. Consensus is expecting revenue to climb from roughly US$34bn in FY26 to more than US$60bn by FY29, while earnings are expected to almost double. If that did not materialise, the stock would invariably continue to pull back.
Overall, we like the setup here. The structural thesis around AI, HBM and advanced packaging remains intact, earnings momentum is accelerating, and importantly, the stock has now corrected sharply from its highs. At around US$450, AMAT trades on roughly 24x FY27 earnings and 19x FY28 earnings, which looks increasingly attractive if current forecasts are achieved.
- AMAT would give us exposure to the AI semiconductor boom without needing to pick the winning chip designer. As chips become more complex, the equipment required to manufacture them becomes more valuable, and AMAT sits directly in that sweet spot. We are adding AMAT to our Hitlist.