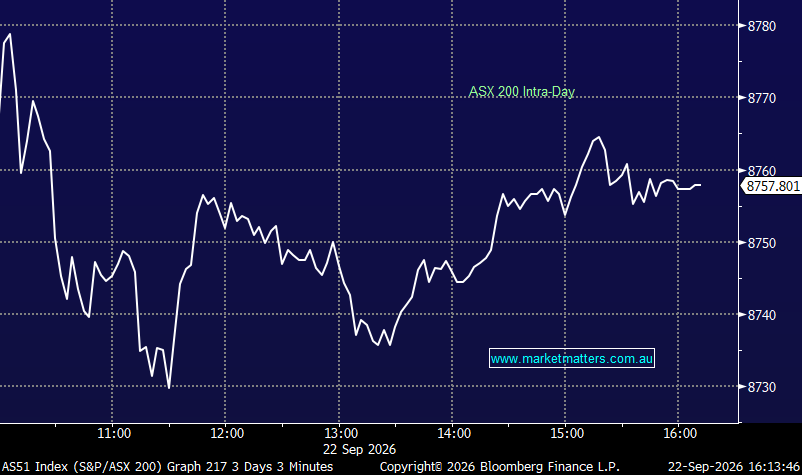
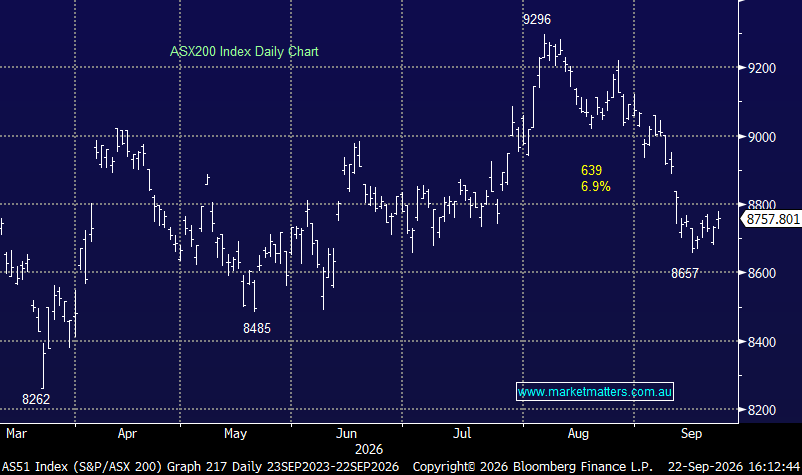
The ASX 200 finished modestly higher today, but the headline gain masks another fairly mixed session. The index jumped ~50 points at the open following a strong lead from Wall Street and renewed enthusiasm around the AI trade and a drop in Oil prices, before handing back some of those gains as the day progressed.
Technology led today’s move on the back of a similar trend overseas, while energy and utilities were the clear laggards as hopes or progress in US-Iran negotiations weighed on crude.
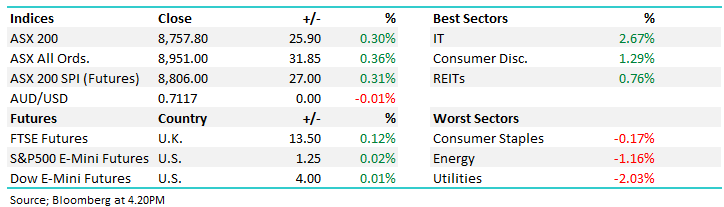
- ASX 200: +25.90pts / +0.30% to 8,757.80
- AUD/USD: 0.7117 / -0.01%
- Best sectors: Information Technology +2.67%, Consumer Discretionary +1.29%, REITs +0.76%
- Worst sectors: Utilities -2.03%, Energy -1.16%, Consumer Staples -0.17%
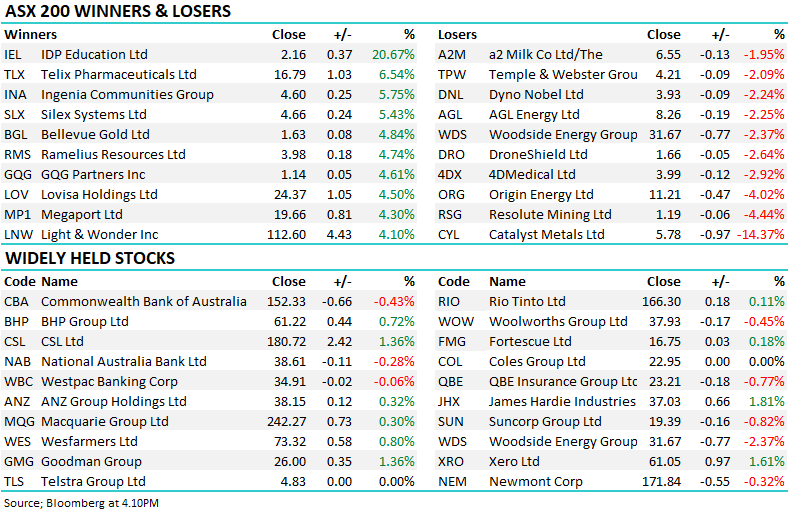
- IDP Education (IEL) +20.67% to $2.16 was the standout performer, bouncing sharply from heavily sold-down levels.
- Telix Pharmaceuticals (TLX) +6.54% to $16.79 continued its strong run following recent positive regulatory momentum and a more bullish note from Citi on their recent acquisition. RBC upgraded the stock to buy.
- Ingenia Communities Group (INA) +5.75% to $4.60 rallied strongly, while Silex Systems (SLX) +5.43% to $4.66 and Bellevue Gold (BGL) +4.84% to $1.63 were also among the stronger names.
- Ramelius Resources (RMS) +4.74% to $3.98 and GQG Partners (GQG) +4.61% to $1.14 added to the list of outperformers.
- Lovisa (LOV) +4.50% to $24.37, Megaport (MP1) +4.30% to $19.66 and Light & Wonder (LNW) +4.10% to $112.60 also finished firmly higher.
- The AI trade provided a positive lead from offshore, helping local growth names. Xero (XRO) +1.61% to $61.05, Goodman Group (GMG) +1.36% to $26.00 and CSL (CSL) +1.36% to $180.72 all advanced.
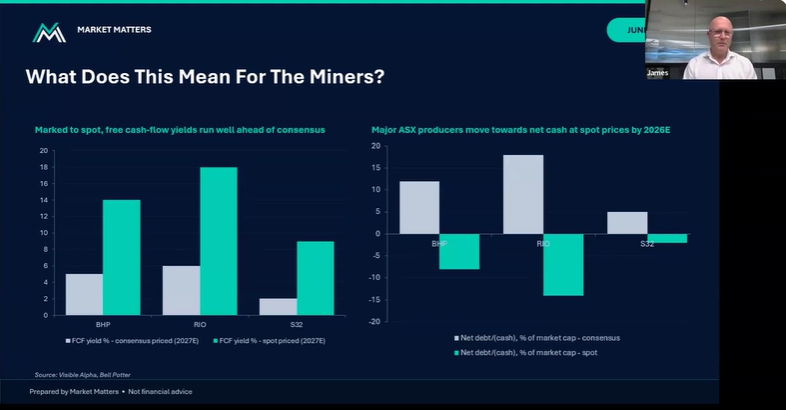
- BHP Group (BHP) +0.72% to $61.22 and Rio Tinto (RIO) +0.11% to $166.30 edged higher as copper extended its recent run on stronger Chinese demand, while Fortescue (FMG) +0.18% to $16.75 was little changed.
- Uranium names were generally firmer, reflecting renewed confidence in the AI power-demand thematic. Paladin Energy (PDN) +1.28%, Deep Yellow (DYL) +3.75% and NexGen Energy (NXG) +3.73% all advanced.
- The major banks struggled to add much after an early lift. Commonwealth Bank (CBA) -0.43% to $152.33, National Australia Bank (NAB) -0.28% to $38.61 and Westpac (WBC) -0.06% to $34.91 eased, while ANZ (ANZ) +0.32% to $38.15 finished modestly higher.
- Macquarie Group (MQG) +0.30% to $242.27 also edged higher.
- Energy was the main drag as hopes for US-Iran talks pressured crude prices. Woodside Energy (WDS) -2.37% to $31.67, Santos (STO) -1.39%, Origin Energy (ORG) -4.02% to $11.21 and AGL Energy (AGL) -2.25% to $8.26 all declined.
- Catalyst Metals (CYL) -14.37% to $5.78 was the weakest stock in the index, while Resolute Mining (RSG) -4.44%, 4DMedical (4DX) -2.92% and DroneShield (DRO) -2.64% also fell sharply.
- Temple & Webster (TPW) -2.09%, Dyno Nobel (DNL) -2.24% and a2 Milk (A2M) -1.95% were also among the weaker names.
- Bellevue Gold (BGL) +4.84% remained in focus after revealing that legacy hedging contracts cost the company almost $200m during FY26. Bellevue reported net profit of just $7.1m but said the figure would have been around $205m without the onerous hedging commitments struck with Macquarie in 2021. The company remains locked into selling a meaningful portion of production well below spot gold prices.
- Ramelius Resources (RMS) +4.74% gained, while Newmont (NEM) -0.32%, Northern Star (NST) -0.18% and West African Resources (WAF) flat were more subdued.
- Brent crude: around US$101/bbl, easing as hopes for renewed US-Iran negotiations reduced some of the immediate geopolitical risk premium.
- Gold: was down $US25 to around US$4,317/oz,
- Copper: continued to firm for a fourth consecutive session, supported by improving Chinese demand.
- S&P 500 E-mini futures: +1.25 points / +0.02%
- Dow E-mini futures: +30 points / +0.06%