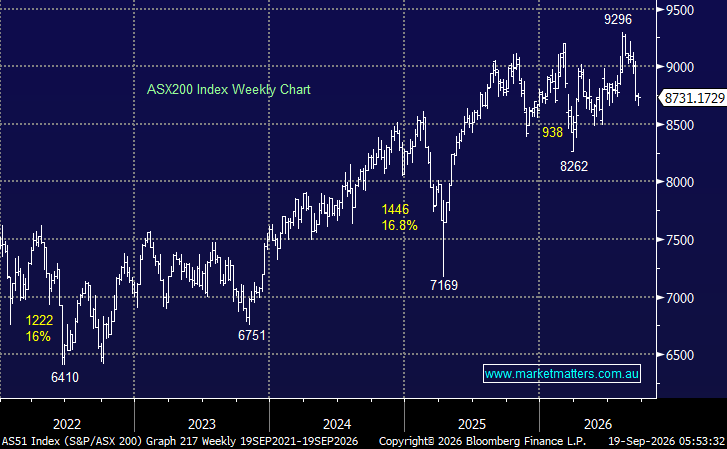
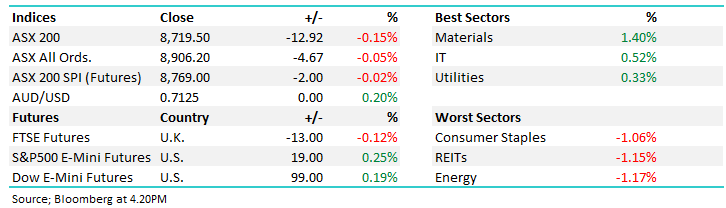
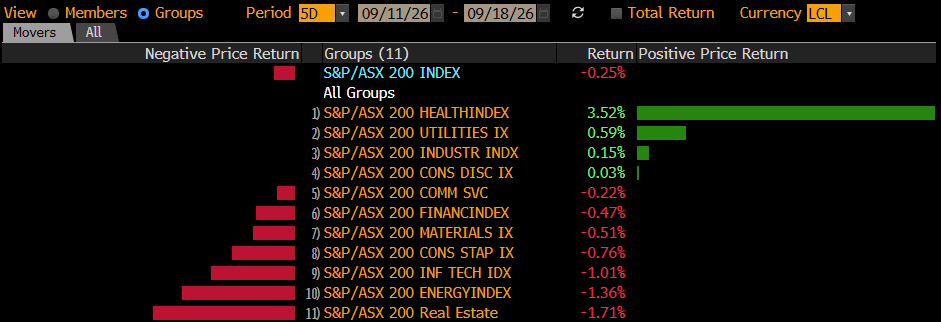
The ASX 200 slipped 0.1% last week, its 3rd consecutive weekly decline, but a welcome relief from the aggressive selling earlier in the month. With the Fed rate hike behind us, attention switched to the RBA on the 29th as rising bond yields continue to weigh on risk assets. We anticipate further weakness in the coming week (s), but the index is slowly gaining an air of a market “looking for a low.”
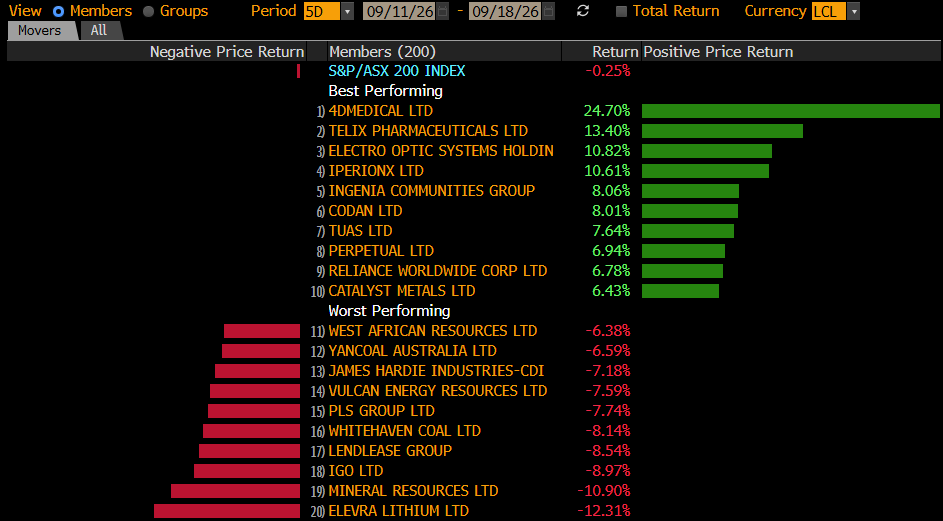
The best-performing stocks last week were an eclectic bunch, while the losers had a distinct lithium flavour.
Winners: Telix Pharma (ASX: TLX) +14%, IperionX (ASX: IPX) +14%, Electro Optic (ASX: EOS) +13%, Tuas (ASX: TUA) +11%, Codan (ASX: CDA) +11%, Ingenia (ASX: INA) +9%, Reliance Worldwide (ASX: RWC) +7%, and Perpetual (ASX: PPT) +7%.
Losers: Mineral Resources (ASX: MIN) -11%, Elevra Lithium (ASX: ELV) -10%, Lend Lease (ASX: LLC) -10%, IGO Ltd (IGO) -9%, Light & Wonder (ASX: LNW) -8%, Whitehaven Coal (ASX: WHC) -8%, PLS Group (ASX: PLS) -8%, and James Hardie (ASX: JHX) -7%.
Weekly snapshot: Last week saw the ASX continue to live up to its historical September weakness, testing early July lows:
- The lithium and uranium stocks started the week on the back foot as the headlines weighed on the sectors.
- Selling momentum picked up on Tuesday with the ASX 200 hitting a 3-month low as the banks and miners dragged the index below 8700.
- The banks rallied strongly on Thursday after the Fed hiked rates by 0.25%, although weakness in the materials sector reined in gains.
- The ASX limped into the weekend, surrendering early gains after Michelle Bullock signalled further rate hikes are possible, or even likely.
In the coming week, inflation and bond yields will remain in focus, with the US PMI and Jobs Report due. No major releases are due in Australia, but events around the US-Iran War will continue to be watched closely.
Overseas markets limped into the weekend with only tech and the “AI Trade” showing any signs of strength. In Europe, German DAX (-1.6%) and UK FTSE (-1.5%) experienced a tough Friday night as growth expectations deteriorated. In the US, the Dow retreated 0.2% while the S&P 500 gained +0.1% courtesy of strength in chipmakers, on a busy day with US$7 trillion of options value expiring.
- The SPI Futures are calling the ASX 200 to open down 0.6% on Monday, following the weakness in European bourses.