Hi Debbie,
CSL Ltd (CSL) re-rated higher after its FY26 result in August beat low expectations with revenue up across all three divisions and underlying earnings slightly ahead of expectations, plus there were no nasty surprises after a tough few years. Encouragingly, even after bouncing ~90% from its panic lows CSL is still trading on the cheap side of it’s historical valuation.
- We can see CSL bouncing another 10% back towards $200 but the “easy money” of this move is likely now in the rear-view mirror.
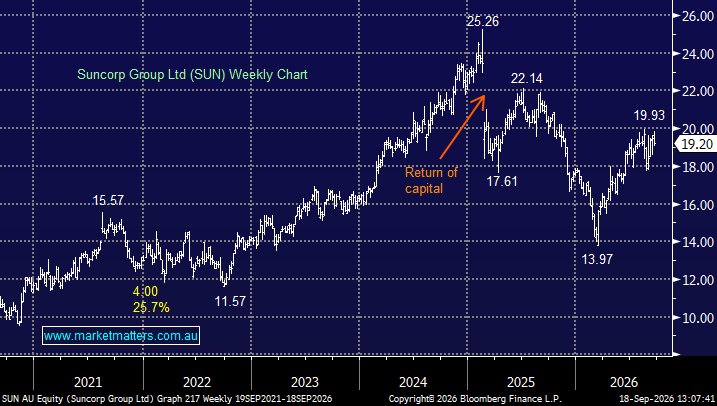
Suncorp (SUN) has already outperformed the ASX in 2026 with rising bond yields offering a tailwind, despite a mixed FY26 result here. In other words, support for SUN and other ASX insurers from bond yields is already priced into the sector.
We still regard the takeover angle as alive, but very much unconfirmed. The September reports suggest Tokio Marine’s work has progressed beyond the initial August speculation, but without an indicative proposal, price or ASX announcement, there is still a significant gap between “Suncorp is the preferred target” and an actual bid.
- For SUN shareholders, like ourselves, the takeover possibility is therefore potential cream on the cake as opposed to a done deal. We continue to see tailwinds for insurance stocks, and intend to hold our SUN position while they remain in place.
NB there was no specific news for Wednesday ~60c drop it was simple day-day order flow driven noise.