- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
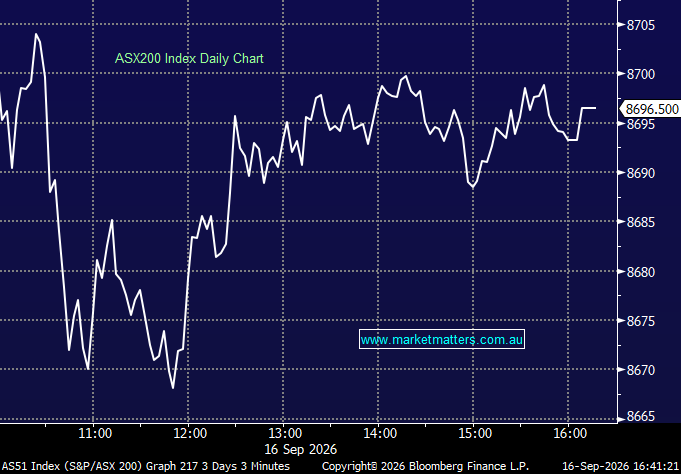
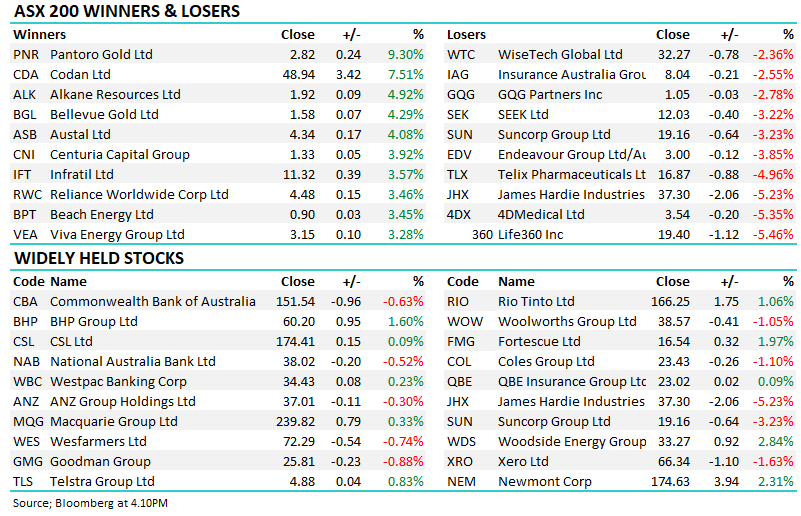
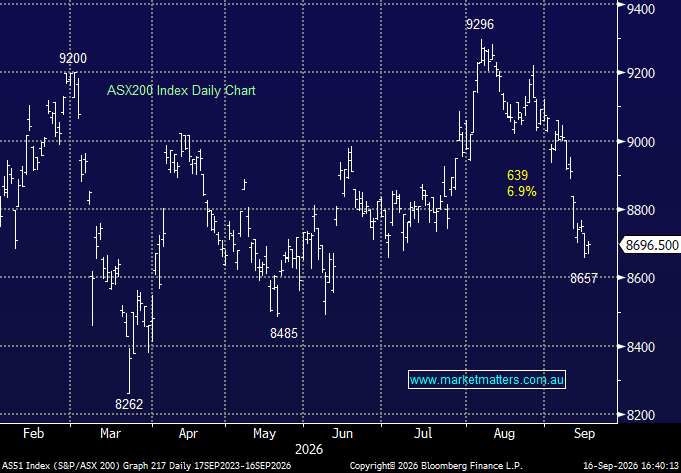
The ASX finished modestly higher today in a mixed session with energy the clear standout as elevated oil prices continued to support the sector, while parts of the broader resources complex attempted to stabilise after recent heavy selling. Banks and consumer staples struggled as a rotation out of ‘defensive’ areas of the market took place, though we’ll need to see a continuation of this through multiple sessions before we call a meaningful change in sentiment. Bond yields remain elevated on the back of higher oil prices, continuing to dominate sentiment, with the Federal Reserve meeting to decide the US cash rate tonight, +0.25% hike to 3.75% now almost fully priced into credit markets.
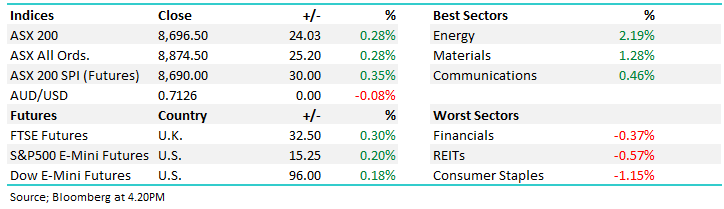
- ASX 200: +24.03pts (+0.28%) to 8,696.50
- AUD/USD: 0.7126, flat
- Best sectors: Energy +2.19%, Materials +1.28%, Communications +0.46%
- Worst sectors: Consumer Staples -1.15%, REITs -0.57%, Financials -0.37%
- Energy was the clear standout, with the ASX 200 Energy Index up around 2.6%, taking it within 2.5% of its April high – Woodside (ASX: WDS) +2.84% to $33.27, Viva Energy (ASX: VEA) +3.28% to $3.15, Karoon (ASX: KAR) +2.16% to $1.895, Ampol (ASX: ALD) +2.46% to $43.25 and Santos (ASX: STO) +2.11% to $8.73.
- Lithium remained the major lowlight. Chinese lithium carbonate futures fell another 3.5% to 124,900 yuan/t, down 12% in a week and 40% from the May high. PLS Group (ASX: PLS) -0.23% to $4.25 has now fallen 25% since the start of September and is only 3% away from a fresh YTD low. Liontown (ASX: LTR) -1.92% to $1.02, Vulcan Energy (ASX: VUL) flat at $2.24, IGO (ASX: IGO) -1.68% to $7.03 and Mineral Resources (ASX: MIN) flat at $54.32 were also lower. PLS held in the Active Growth Portfolio. LTR held in the Emerging Companies Portfolio.
- Gold miners performed well though the local stocks remain well off their highs – Capricorn Metals (ASX: CMM) +1.15% to $14.92 and Evolution Mining (ASX: EVN) +1.07% to $13.27 recovered modestly. Evolution held in the Active Growth Portfolio.
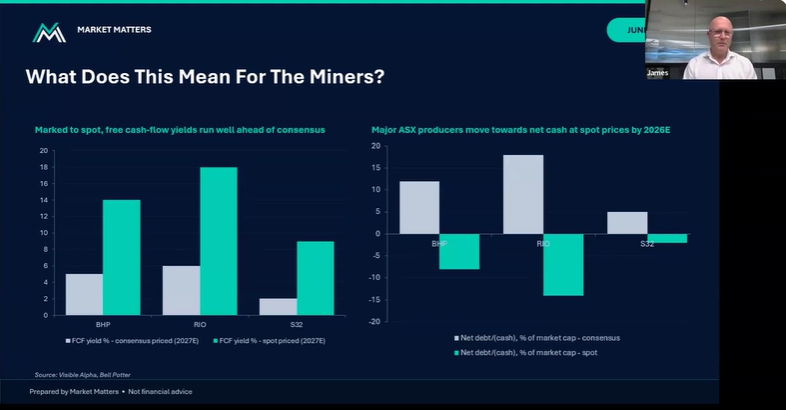
- Copper has stabilised, but the story has changed somewhat, trading around US$14,100/t after its recent record as rising LME inventories and the absence of new US tariff measures reduced the immediate supply-squeeze narrative. BHP (ASX: BHP) +1.60% to $60.20, Capstone Copper (ASX: CSC) +1.08% to $14.10 and Sandfire Resources (ASX: SFR) +2.90% to $21.26 were all firmer. BHP held in the Active Growth and Income Portfolios. SFR held in the Active Growth Portfolio.
- Infratil (ASX: IFT) +3.57% to $11.32 lifted FY27 earnings (EBITDAF) guidance, driven by stronger CDC Data Centres expectations with +4.3% earnings growth added at the midpoint following another 70MW of signed contracts.
- Reliance Worldwide (ASX: RWC) +3.46% to $4.48 rose after signing a binding scheme deed with Brookfield at US$3.38 per share, equivalent to around A$4.75. The deal represents a 31.5% premium to the undisturbed price (17 August), with a go-shop process running until October 15.
- James Hardie (ASX: JHX) -5.23% to $37.30 fell despite lifting FY27 free cash flow guidance to US$600m+. Sales and EBITDA guidance was unchanged, with the softer US housing backdrop and elevated freight and diesel costs weighing on sentiment.
- Codan (ASX: CDA) +7.51% to $48.94 was a strong individual performer.
- South32 (ASX: S32) +3.09% to $5.01 received attention after releasing a business update aftermarket yesterday, announcing its Hermosa zinc project is on track with 80% of growth capital already invested. The project remains on its revised US$3.3bn budget and timeline, with first breakthrough to the Taylor orebody targeted for November 2027.
- Pengana International Equities (ASX: PIA) +7.32% to $1.10 surged after settling litigation with its manager and appointing Antipodes as sub-investment manager, clearing the way for its buyback and portfolio transition.
- Global Lithium (ASX: GL1) was flat after delivering a significant improvement to the economics of its Manna project, with post-tax NPV doubling to $946m while pre-production funding requirements fell 59% to $180m.
- Gold: $4,333.05 / +0.95%
- Brent crude: $107.58 / -1.08%
- Iron Ore: $95.65 / +0.22%
- S&P 500 E-mini futures: +15.25pts / +0.20%
- Dow E-mini futures: +96.00pts / +0.18%
- FTSE futures: +32.50pts / +0.30%