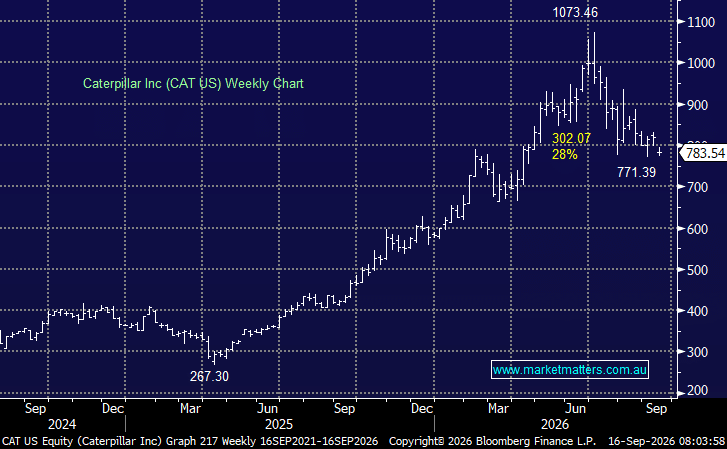
Caterpillar has been on our Hitlist for the International Equities Portfolio for some time. We like the business, we like the earnings trajectory, and importantly, we like the way the stock has behaved over the medium term. CAT has been in a powerful uptrend, rising from around US$270 eighteen months to a June high of US$1,073, before pulling back to around US$784 today. That is a correction of ~28% from the high, which has materially improved the risk/reward in our view.
- This is generally the type of setup we prefer – a fundamentally strong company in an established uptrend that has corrected, rather than a weak company simply getting cheaper.
The fundamental backdrop remains attractive. We have revenue increasing from around US$64bn in FY25 to US$77bn in FY26 and US$86bn in FY27, while adjusted EPS is forecast to rise from US$19.06 to US$27.17 and US$32.56 respectively. Free cash flow is also expected to grow strongly, from around US$7.5bn in FY25 to more than US$12bn in FY27.
That leaves CAT trading on roughly 29x FY26 and 24x FY27 earnings. It is not cheap in absolute terms, but the valuation has compressed significantly as the share price has pulled back while earnings expectations have continued to rise.
There are also several structural themes we like. Caterpillar provides exposure to ongoing investment in mining, infrastructure, energy and power generation, while its large installed equipment base and aftermarket parts and services business provide an important recurring earnings stream.
Mining electrification is another potentially important opportunity. The transition away from diesel does create some risk to Caterpillar’s traditional engine-related revenue and aftermarket servicing over time, but we think the opportunity could be larger than the risk.
Electrifying a mine involves far more than replacing a diesel engine with a battery. Miners need new trucks and loaders, batteries, charging systems, power infrastructure, fleet-management software and increasingly autonomous equipment. That has the potential to create a significant replacement cycle across global mining fleets over the next decade.
Caterpillar is well placed to participate because electrification is occurring alongside automation and digitisation. Its established position across mining equipment, autonomous haulage and fleet management gives it an opportunity to capture a greater share of overall mine-site spending as miners modernise their operations.
The key risk is execution. If battery-electric equipment requires less maintenance and fewer engine rebuilds, parts and servicing revenue tied to diesel powertrains could come under pressure. CAT therefore needs to ensure that growth in batteries, software, autonomous systems and electrical infrastructure more than offsets any erosion in traditional engine-related earnings.
We think the transition is more likely to broaden CAT’s addressable market than undermine it, particularly given the scale of capital expenditure required to electrify large mining operations. The market remains constructive as well, with consensus showing 17 Buy ratings, 10 Holds and no Sells, with an average 12-month target of ~US$1,012, almost 30% above the current share price.
CAT remains on our Hitlist for the International Equities Portfolio, and the recent pullback has increased our interest. The stock became extended following a very strong run into June, and we were reluctant to chase it. The subsequent correction below US$800 has reset the valuation and improved the risk/reward while the underlying earnings outlook remains strong.
We also like the company’s leverage to several long-duration investment themes, particularly mining and infrastructure spending. The shift towards electrified and increasingly autonomous mines adds another potential growth leg, even if it creates some disruption to the traditional diesel-engine model.
This is the type of price action we like to see when looking to initiate a position: a quality business with positive earnings momentum and a strong medium-term trend undergoing a meaningful correction. We are not trying to pick the exact low and would still like to see the shares find some support following the recent weakness.
- CAT is now approaching levels where we would be increasingly comfortable taking an initial position.