Vysarn has been a strong small-cap performer over the past 18 months, supported by solid operational execution, organic growth and a series of earnings-accretive acquisitions that have broadened the business beyond its original drilling operations. The latest proposed acquisition of NWG Enterprises/NewGround was intended to continue that diversification, but the transaction has now been mutually terminated after the parties were unable to agree on an extension to the completion date.
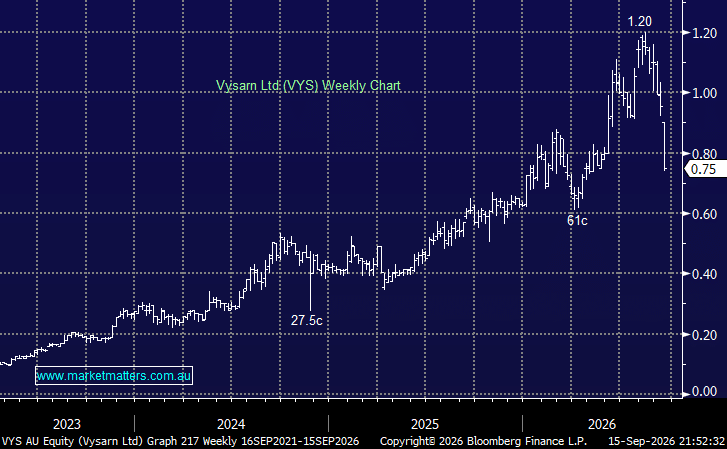
- The market has reacted sharply, with VYS falling to around 75c, down roughly 35% from its recent high near $1.16, dragging it’s market cap back down to ~$450mn.
Importantly, the deal falling over does not change the underlying attraction of the core business. Vysarn has developed into a broader water-services provider spanning hydrogeological drilling, test pumping, water management, engineering, wastewater treatment and consulting. We like the exposure this provides to ongoing resource development, particularly in Western Australia. Large mining projects require substantial investment in dewatering, groundwater management, environmental compliance and supporting infrastructure, making Vysarn an interesting picks-and-shovels exposure to mining investment without taking direct commodity-price risk.
- The business is also becoming more diversified, both operationally and through acquisitions. While NewGround would have added another leg to that strategy, its failure does not derail the broader investment case.
Consensus expectations still point to strong earnings growth. Revenue is forecast to rise from around $140m in FY26 to $183m in FY27, while EBITDA is expected to increase from around $29m to almost $40m. Adjusted EPS is forecast to rise from 2.8c to 3.6c, with further growth expected thereafter.
At 75c, VYS is trading on around 20–21x FY27 earnings and roughly 18x FY28 earnings. That remains above its longer-term average, so we would not call the stock outright cheap, but the valuation is now far more reasonable given the growth profile.
We think the reaction is starting to look overdone, although the price action still warrants some caution. Trading volumes have remained elevated through the sell-off, suggesting there is still meaningful stock being worked through the market and that the selling pressure may not yet be exhausted.
The failed acquisition is clearly a setback and removes one component of the near-term growth story, but the core business remains attractive, earnings growth is solid and we continue to like Vysarn as a proxy for resource development and the growing demand for water-management services.
Rather than trying to pick the bottom, our preference would be to let the shares settle, look for evidence that the heavy selling has been absorbed and wait for the stock to establish a level of support. If that occurs while the underlying earnings outlook remains intact, we think the risk/reward would become increasingly attractive. At around $1.15, expectations looked demanding. At 75c, the valuation is far more interesting.
- We are watching VYS closely and would become more constructive if the shares can find support around current levels.
MM is adding VYS to the Hitlist for the Emerging Companies Portfolio
Add To Hit List