- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
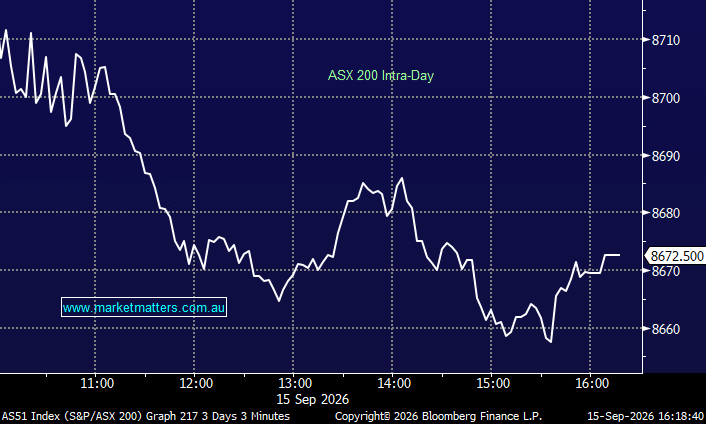
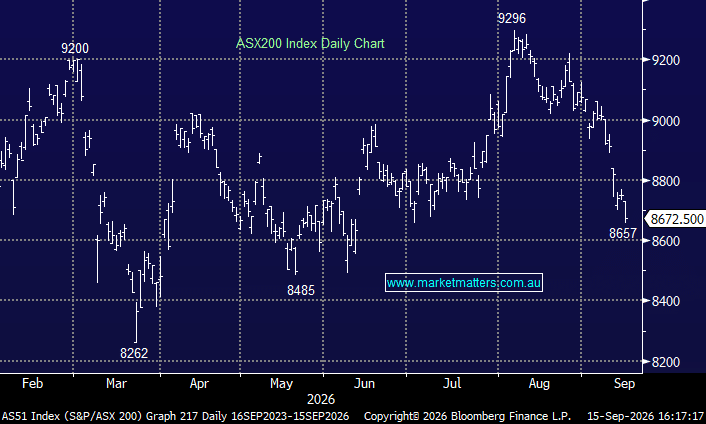
The ASX continued its slide today, falling to a fresh three-month low as banks and miners came under renewed pressure, extending the broader market weakness. The index is now down around 6.5% from its 6 August record high. Macro continues to drive the sell-off; news flow around individual companies is almost non-existent, with oil, bond yields, and expectations for further central bank tightening later this week dominating sentiment.
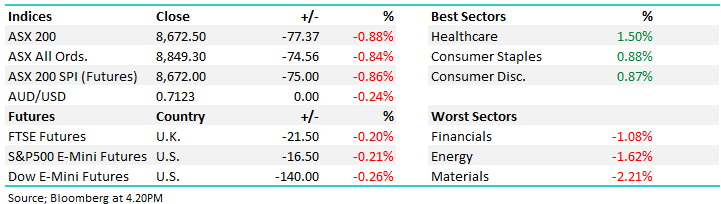
- ASX 200: -77.37pts (-0.88%) to 8,672.50
- AUD/USD: 0.7123, flat
- Best sectors: Healthcare +1.50%, Consumer Staples +0.88%, Consumer Disc. +0.87%
- Worst sectors: Materials -2.21%, Energy -1.62%, Financials -1.08%
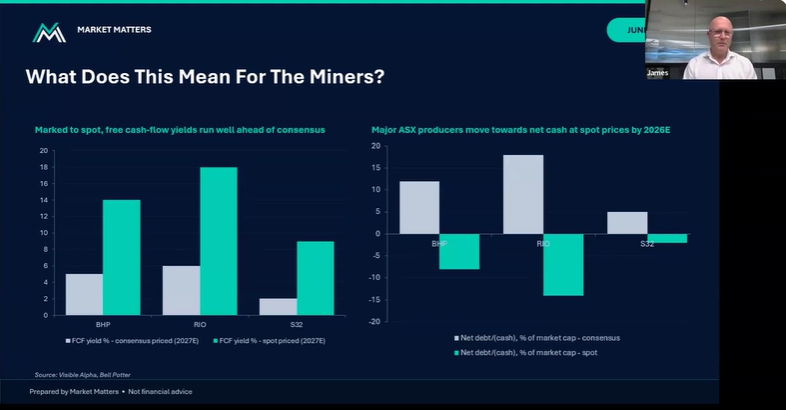
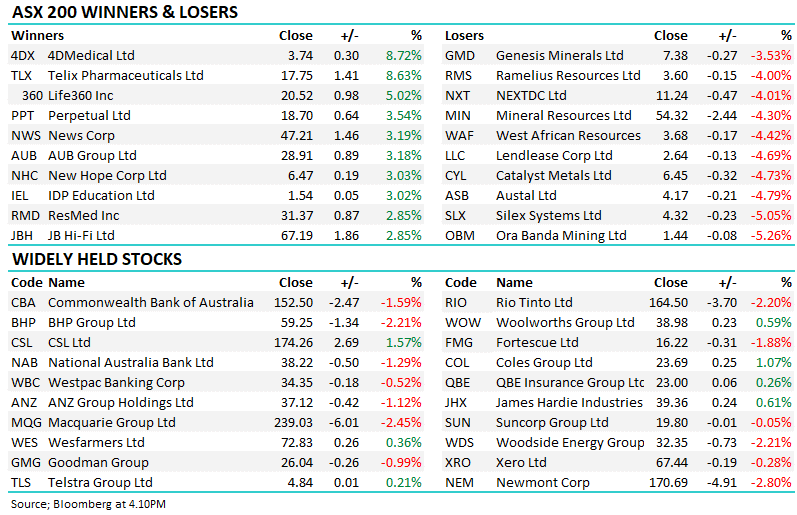
- Materials -2.21% was the biggest drag, with BHP (ASX: BHP) -2.21% to $59.25 and Rio Tinto (ASX: RIO) -2.20% to $164.50. The sector has now fallen for four consecutive sessions, reflecting the combination of higher yields, weaker copper and ongoing concerns around global growth. BHP held in the Active Growth and Income Portfolios.
- Financials -1.08% also weighed on the index heavily, with CBA (ASX: CBA) -1.59% to $152.50, NAB (ASX: NAB) -1.29% to $38.22, ANZ (ASX: ANZ) -1.12% to $37.12 and Westpac (ASX: WBC) -0.52% to $34.35. ANZ held in the Active Growth and Income Portfolios. WBC held in the Active Income Portfolio.
- Technology finally produced a meaningful bounce, rising around 1%, after being smashed over recent weeks. The sector had fallen 17.5% between 26 August and 14 September, so today’s move looks more like an oversold rebound than a confirmed trend reversal. Life360 (ASX: 360) +5.02% to $20.52, WiseTech (ASX: WTC) +1.88% to $33.05 and Megaport (ASX: MP1) +2.69% to $16.79 were among the session’s movers. WiseTech held in the Active Growth Portfolio.
- 4DMedical (ASX: 4DX) +8.72% to $3.74 and Telix Pharmaceuticals (ASX: TLX) +8.63% to $17.75 were the session’s two biggest winners on the ASX 200, continuing the healthcare sector’s recent run of relative strength.
- New Hope (ASX: NHC) +3.03% to $6.47 delivered a mixed result: underlying EBITDA of $514.3m was essentially in line, while NPAT fell 63% to $161m. The standout was a 30¢ fully franked final dividend. NHC held in the Active Income Portfolio.
- Nickel Industries (ASX: NIC) -1.26% to $0.785 was hit by an Indonesian drought, forcing its Excelsior Nickel Cobalt operation to run at only 30% of nameplate capacity while water shortages persist.
- Santos (ASX: STO) -2.06% to $8.55 signed a 10-year LNG sales agreement with POSCO beginning in 2030/31, while also agreeing to a 20-year non-binding deal to purchase 1Mtpa of LNG from Canada’s Ksi Lisims project. The transactions reinforce Santos’ strategy of building a flexible LNG portfolio around long-term energy security.
- China data added to the negative macro read, with retail sales rising just 0.4% year-on-year in August versus 0.8% expected, fixed-asset investment falling 7.2% and property investment plunging 19.9%. Industrial production was stronger at +5.2%, supported by exports and AI-related electronics demand, but domestic demand remains clearly weak.
- Gold: $4,287.16 / -0.29%
- Brent crude: $107.34 / +1.57%
- Iron Ore: $95.50 / -0.09%
- S&P 500 E-mini futures: -16.50pts / -0.21%
- Dow E-mini futures: -140.00pts / -0.26%
- FTSE futures: -21.50pts / -0.20%