- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
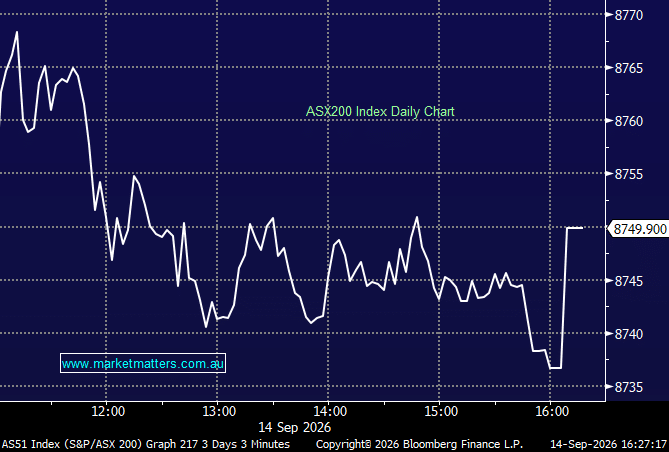
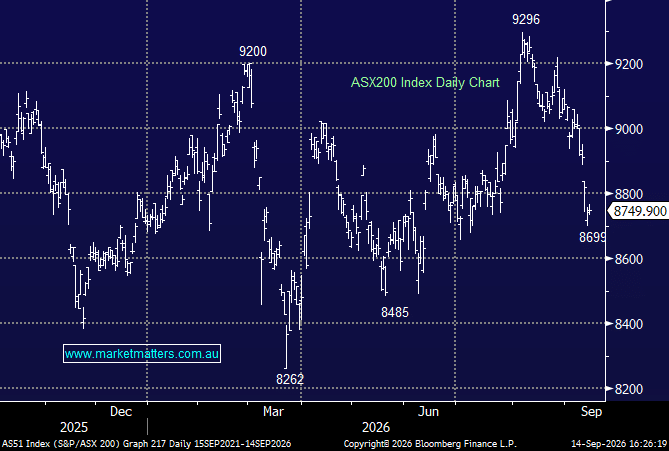
The ASX broke a four-day losing streak today, but only just, finishing essentially flat after an early gain of around ~0.3% faded through the afternoon. The session was another example of the market being driven by the macro rather than company-specific news, with oil, bond yields and shifting expectations for central-bank policy dominating sentiment. Brent crude traded above US$107 per barrel, up around 3% on the day and roughly 25% since late August which saw defensives and selected beaten-up consumer names outperforming, while Materials and Technology continued their weakness from the end of last week.
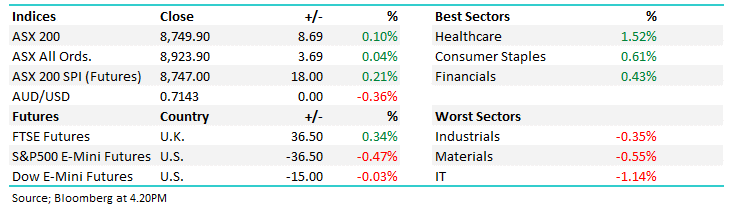
- ASX 200: +8.69pts (+0.10%) to 8,749.90
- AUD/USD: 0.7143, flat
- Best sectors: Healthcare +1.52%, Consumer Staples +0.61%, Financials +0.43%
- Worst sectors: IT -1.14%, Materials -0.55%, Industrials -0.35%
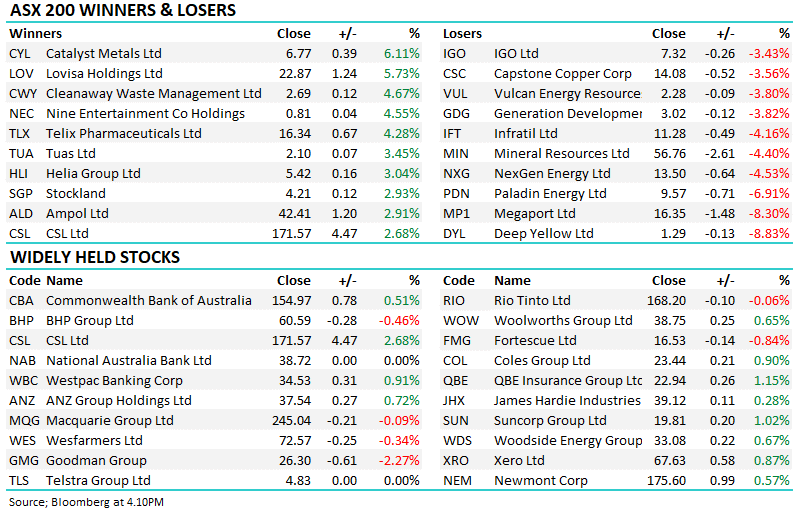
- Energy was again one of the few bright spots, supported by the renewed oil spike – Woodside (ASX: WDS) +0.67% to $33.08 gained around 1%, while Santos (ASX: STO) +1.63% to $8.73 reached a four-year high.
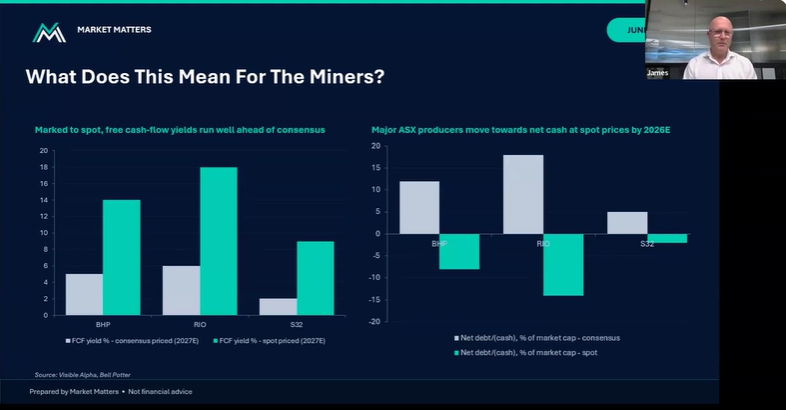
- Materials remained the major drag as iron ore slipped to a three-week low near US$96/t in Singapore with data suggesting Chinese steel mill profitability is weakening – BHP (ASX: BHP) -0.46% to $60.59 fell while Rio Tinto (ASX: RIO) -0.06% to $168.20 was broadly flat. BHP held in the Active Growth and Income Portfolios.
- Technology also remained under pressure, although there was some bargain hunting in beaten-up names. Xero (ASX: XRO) +0.87% to $67.63 and REA Group (ASX: REA) +2.32% to $158.00 bounced, while Megaport (ASX: MP1) -8.30% to $16.35 fell sharply. The Technology index has now given back almost all its ~22% rally between late July and mid-August. WiseTech (ASX: WTC) -0.76% to $32.44 was also softer. WiseTech & Xero held in the Active Growth Portfolio.
- Telix Pharmaceuticals (ASX: TLX) +4.28% to $16.34 was a standout, gaining after the FDA approved Pixclara, the first FET-PET imaging agent cleared in the US for brain cancer.
- Silex Systems (ASX: SLX) -2.15% to $4.55 fell in line with the broader lithium space, though announced an important commercial milestone, with their subsidiary Global Laser Enrichment (GLE) signing an exclusive agreement for Cameco to purchase all future production from the planned Paducah Laser Enrichment Facility. Silex held in the Emerging Companies Portfolio.
- Lovisa (ASX: LOV) +5.73% to $22.87 rallied after UBS upgraded the stock to Buy from Neutral with a $28 target. UBS sees international expansion as the key earnings driver, forecasting 121 net store additions in FY27, while upgrading FY27 and FY28 EPS forecasts by 5.1% and 4.8% respectively.
- Core Lithium (ASX: CXO) +13.9% to 39c was one of the more unusual movers, surging despite no new market-sensitive announcement, and against the tide for the lithium space – we’ll wait to hear more on this one.
- Minerals 260 (ASX: MI6) flat at $0.88 gained after securing a further $200m commitment from Franco-Nevada for the Bullabulling gold project, taking Franco-Nevada’s total investment to $420m. The package includes $170m of non-dilutive royalty funding and $30m of future equity.
- Cleanaway (ASX: CWY) +4.67% to $2.69 remained in focus as EQT reaffirmed its intention to proceed with its takeover proposal on unchanged terms, despite the expiry of hard exclusivity. Three parties also remain in the FleetPartners auction, with ORIX and the Sumitomo consortium both offering $4.65/share and SG Fleet at $4.55.
- Gold: $4,330.31 / -0.43%
- Brent crude: $106.74 / +2.04%
- Iron Ore: $95.70 / -0.85%
- S&P 500 E-mini futures: -36.50pts / -0.47%
- Dow E-mini futures: -15.00pts / -0.03%
- FTSE futures: +36.50pts / +0.34%