- Markets @ Midday: Listen here at lunchtime or find all Market Matters Podcasts on Spotify.
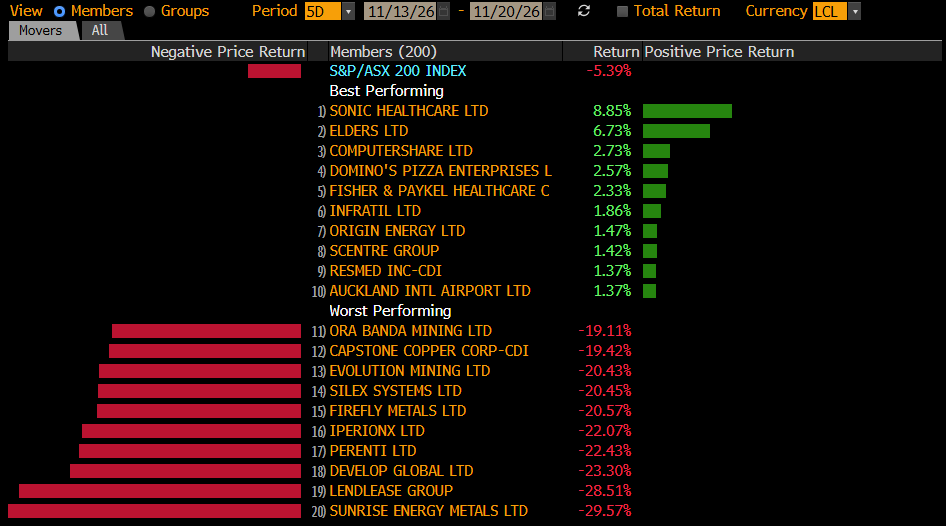
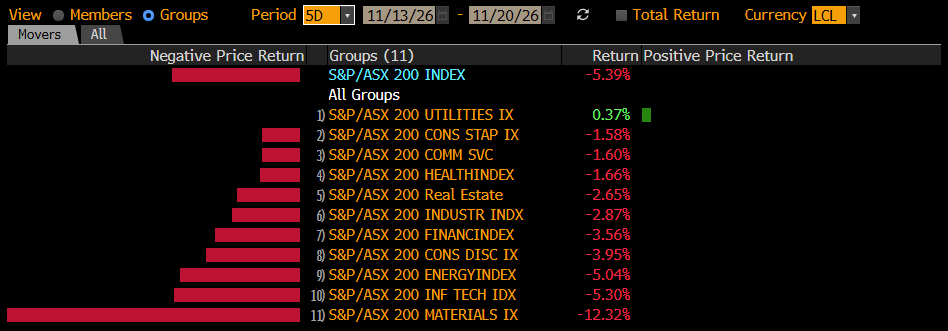
What a week! The ASX fell ~5.5%, extending its losing streak to seven consecutive sessions, while small caps fared even worse, down over 8%. It was a broad-based risk-off move, though resources really copped it, down 12.3% on mounting global growth concerns. While all sectors of the market traded lower, the more defensive areas – utilities, insurance, infrastructure and supermarkets – held up well, as you’d expect.
The weakness has been global; Over the last five days, the S&P 500 has fallen 5.5%, the Nasdaq is down 6.3%, oil prices have declined 5.5%, gold is down 9.5% and copper is off ~10%. These are significant moves across a broad range of asset classes, although we only need to go back to March this year, or more recently to August, to find similar periods of market weakness.
With the ASX 200 down 575pts from last week’s high, most equity portfolios will have struggled. At MM, our more defensive Income Portfolio is down ~3.4% this week, while the International Equities Portfolio has been partially cushioned by weakness in the AUD, down ~4.5%. Our Growth and Emerging Companies Portfolios have borne the brunt of the selling, both down ~8%.
Markets have a tendency to climb the stairs and take the elevator down, and that has certainly been on display this week. We know it’s little solace on a Friday afternoon after a tough week, but history tells us that stepping up during periods of heightened fear, rather than retreating, has generally served investors well. With this in mind, we made some small changes to the Growth Portfolio today, looking to capitalise on the recent weakness.
Some of the strongest market recoveries follow the sharpest falls, and this has certainly been a sharp one. While picking the bottom is notoriously difficult, maintaining perspective, staying disciplined and recognising the opportunities that indiscriminate selling can create remain central to our approach.
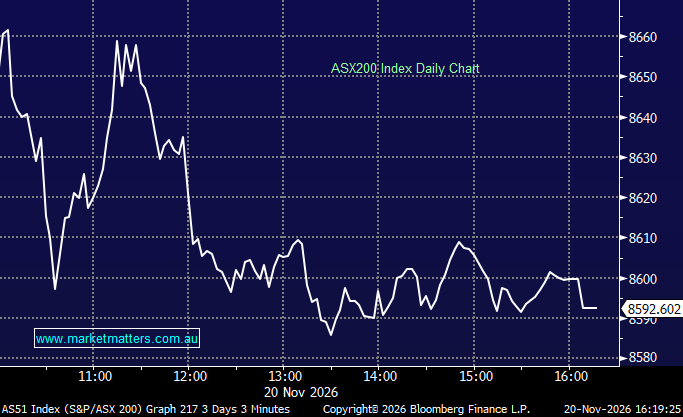
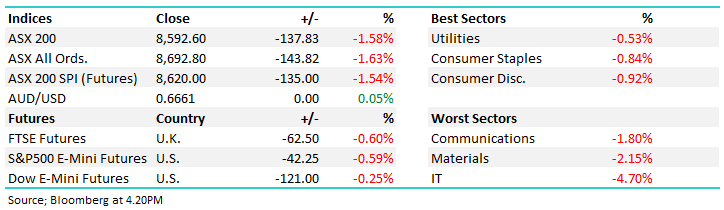
- ASX 200: Closed at 8,592.60, -137.83pts, -1.58%.
- AUD/USD: 0.6661, +0.05%.
- Best Sectors: Utilities -0.53%, Consumer Staples -0.84%, Consumer Discretionary -0.92%.
- Worst Sectors: Information Technology -4.70%, Materials -2.15%, Communications -1.80%.
- Anthropic’s record-breaking IPO overnight offered little relief to the AI trade or broader sentiment. The company closed its first session at US$97.17, up 17% on its US$83 IPO price, after opening 34% higher and reaching a market value of about US$1.77 trillion. However, the stock fell 3.6% in after-hours trading, after the S&P 500 recorded its sixth consecutive decline.
- The technology sell-off gathered pace as investors continued to reassess the scale of AI investment and the valuations attached to companies expected to benefit. The Nasdaq fell 2.25% overnight, and the local technology sector followed suit, with Megaport (ASX: MP1) -12.89% to $14.94, Life360 (ASX: 360) -7.21% to $20.60, Xero (ASX: XRO) -5.65% to $74.87 and Weebit Nano (ASX: WBT) -8.02% to $2.18. NextDC (ASX: NXT) -7.11% to $9.01, while TechnologyOne (ASX: TNE) -1.39% to $32.65. XRO held in the Active Growth Portfolio.
- Materials remained under heavy pressure, extending the sector’s losing streak as the sell-off in precious and base metals gathered momentum. Copper continued its slump to its lowest since March amid concerns about global demand and the sustainability of AI-related infrastructure spending which saw BHP (ASX: BHP) -1.80% to $51.40 lower while Rio Tinto (ASX: RIO) +0.04% to $135.05 and Fortescue (ASX: FMG) +2.13% to $13.44 bucked the broader weakness. BHP & RIO held in the Active Growth & Income Portfolios.
- Gold miners were particularly weak as bullion fell to its lowest level since September 2025 with Mineral Resources (ASX: MIN) -2.45% to $38.69, Evolution Mining (ASX: EVN) -4.78% to $10.36 and Newmont (ASX: NEM) -5.58% to $144.71 while PLS Group (ASX: PLS) +2.34% to $2.62 was one of the few bright spots. EVN held in the Active Growth Portfolio.
- Banks offered little protection against the broader risk-off mood, with all four major lenders finishing lower – Commonwealth Bank (ASX: CBA) -1.00% to $169.92, Westpac (ASX: WBC) -2.23% to $35.94, NAB (ASX: NAB) -1.31% to $36.24 and ANZ (ASX: ANZ) -1.08% to $38.58. ANZ held in the Active Growth & Income Portfolios. We sold WBC in the Active Growth Portfolio today, still holding it in the Income Portfolio.
- NextDC (ASX: NXT) -7.11% to $9.01 fell after shareholders delivered a second strike against its remuneration report, with 72.03% of proxy votes cast against the resolution. A proposed board spill was overwhelmingly rejected, with 95.75% of proxy votes against. The company also lifted FY27 revenue guidance to $485–500m and underlying EBITDA guidance to $260–275m, although both remain well below its August outlook following delays to power works at its Melbourne M3 data centre.
- Pro Medicus (ASX: PME) -2.49% to $187.76 was up early but fell through the session after announcing a US$128m, 10-year contract with New York City Health + Hospitals and allows for further upside through step-ups in pricing. Held in the Active Growth Portfolio.
- Sims (ASX: SGM) +0.78% to $19.40 was higher after upgrading first-half FY27 underlying EBIT guidance for its Sims Lifecycle Services division to $120–130m from $75–90m, citing opportunities created by data-centre component shortages.
- Orica (ASX: ORI) -3.88% to $20.57 fell as it confirmed it had progressed to the second stage of a competitive sale process for Syensqo’s mining-focused Technology Solutions business. No binding agreement has been reached, with Orica saying any potential acquisition must meet its return hurdles and capital management framework.
- Gold: Traded near US$3,538/oz / -2.40%.
- Iron Ore: US$90.55/mt / +0.22%.
- Brent crude: Traded near US$92.60/bbl / +0.5%/
- Futures: S&P 500 E-mini futures -42.25pts / -0.59% | Dow Jones E-mini futures -121.00pts / -0.25% | FTSE futures -62.50pts / -0.60%.